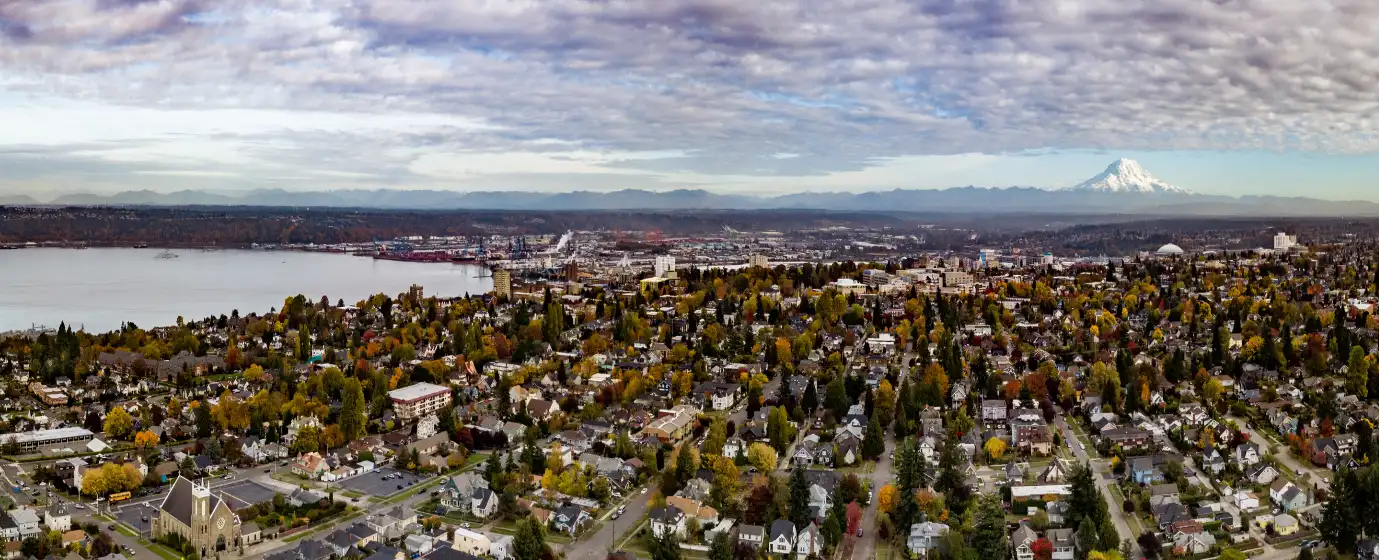
You've probably heard that Tacoma is the affordable alternative to Seattle. That framing is true — and it's also incomplete. Tacoma sits at the south end of Puget Sound, anchored by Interstate 5 and State Route 16, roughly 35 miles south of downtown Seattle. The city is legitimately more accessible in price than Seattle, but it is not cheap, and it is not slow. Redfin's Compete Score rated it 90 out of 100 — "most competitive" — as of July 2026. Coming in expecting a relaxed buyer's market is the single most common mistake first-timers make here.
The economic backbone of the South Puget Sound is a mix of federal military employment at Joint Base Lewis-McChord near Lakewood, two large regional health systems, and a robust public-sector workforce. That base of stable, mid-to-high income earners puts consistent floor-level demand under the housing market. Military families rotating in and out of the region create turnover — and buying windows — that don't exist in purely civilian markets. Tacoma Public Schools serves the city's families, and the presence of University of Washington Tacoma draws younger buyers who eventually put down roots here rather than commuting to Seattle. For an overview of Tacoma's full cost of living picture, including property tax context, that page covers it in depth.
The Zillow Home Value Index for Tacoma stood at $496,203 in July 2026 — well below Seattle's index figure of approximately $856,000, but still well above what a $500K price tag might imply if you're arriving from a Midwest or Sun Belt market. Inventory sat at roughly 1.5 months of supply in early 2026, compared to the 5–6 months that signals a balanced market. Average homes were selling in about 8 days and landing roughly 1% above list price. Hot properties went pending in around 4 days at about 3% over list. The math means your pre-approval, your offer strategy, and your understanding of closing costs have to be tight before you ever walk through a front door.
Whether you're relocating from San Francisco, finally making the move from an apartment in Federal Way, or buying your first home after years of watching the market from the sidelines, this guide covers what your budget actually buys in Tacoma, the step-by-step process from pre-approval to keys, an honest look at the cash you'll need at closing, and the specific mistakes that cost first-time buyers the most in this market.
The Tacoma First-Time Buyer Reality
At a Zillow Home Value Index of $496,203 (July 2026), Tacoma's entry point is not $350,000. That figure sometimes circulates among buyers who glance at older data or filter only for distressed listings. The realistic floor for a move-in-ready single-family home in most parts of the city is closer to the mid-$400,000s, and South Tacoma — the area that historically draws first-timers and younger families — reflects that range most directly.
The North End and Proctor area commands a premium for its craftsman architecture and water views toward Commencement Bay, pushing prices noticeably higher than the city-wide index. If your ceiling is tight, starting your search in the North End and being disappointed is a pattern agents see constantly. Know which part of the city your budget matches before you start touring.
What makes this market hard for first-timers specifically is the combination of low inventory and fast timelines. With roughly 326 active listings in the city as of early 2026, there simply aren't many chances to find a home, reconsider for a week, and come back with an offer. Homes receiving two or more offers in the first few days is the norm, not the exception. The buyers who move successfully here are the ones who already know their budget ceiling, have a pre-approval letter in hand, and have mentally worked through their contingency strategy before they fall in love with a listing.
The Homebuying Process in Tacoma, Step by Step
Step 1: Get Pre-Approved — Before You Tour Anything
In Tacoma, sellers and listing agents treat a pre-approval letter as a baseline requirement, not a courtesy. Without one, your offer won't be taken seriously, and in a market where homes go pending in 4–9 days, you won't have time to get approved after you find something you want. Washington State lenders typically take 5–7 business days to issue a pre-approval letter, and that letter is generally valid for 60–90 days.
Apply to 2–3 lenders at the same time, not sequentially. FICO scoring treats multiple mortgage inquiries submitted within a short window as a single inquiry, so shopping lenders simultaneously won't hurt your credit score — but it will give you real rate and fee comparisons that can save you thousands over the life of a loan. The lender who answers your calls fastest isn't necessarily offering the best terms.
Step 2: Identify Your Area and Budget Band
Tacoma's neighborhoods price and behave differently. South Tacoma and parts of Central Tacoma offer more accessible entry points for first-time buyers. Northeast Tacoma, close to the Puget Sound shoreline, runs higher. Knowing which area your budget realistically targets saves you from a demoralizing first month of offers on homes that were always out of reach.
Step 3: Work with a Local Agent Who Knows Offer Cadence
An agent who primarily works suburban Pierce County markets like Puyallup or Lakewood may not have the same pulse on how quickly Tacoma listings move or what escalation clauses are currently winning offers. In a market scoring 90 out of 100 on Redfin's Compete Score, offer strategy matters as much as offer price.
Step 4: Write a Competitive Offer — and Understand Your Contingencies
Washington State purchase agreements include standard contingencies for financing, inspection, and appraisal. In this market, sellers will sometimes push back on the length of inspection periods or the presence of financing contingencies. First-timers most often get this step wrong in one of two directions: they either waive too much to compete, or they add so many conditions that their offer reads as high-risk. The right balance is specific to the property and the competing offers — not a formula you can set in advance.
Step 5: Inspection, Appraisal, and Closing
Washington State does not require an attorney at closing; most transactions close through a title and escrow company. Closing typically takes 30–45 days once an offer is accepted, though some sellers will negotiate a faster timeline. The inspection period — usually 5–10 days — is where first-time buyers often discover deferred maintenance issues common in Tacoma's older housing stock: aging electrical panels, original plumbing in pre-1970s homes, or moisture intrusion in basements. Budget for inspection costs upfront and treat the results as negotiating information, not a reason to panic.
How Much Home Can You Afford in Tacoma
The table below shows approximate cash-to-close requirements at several realistic Tacoma price points using common loan structures. Closing costs are estimated at 2–3% of the purchase price, which is typical for Pierce County transactions — they include lender fees, title insurance, escrow fees, and prepaid items like homeowners insurance and initial escrow reserves. These are estimates; your actual figures will depend on your lender, the specific property, and negotiated seller concessions.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs | Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5%) — entry-level | $430,000 | $15,050 (3.5%) | $8,600–$12,900 | ~$24,000–$28,000 |
| Conventional (3%) — entry-level | $430,000 | $12,900 (3%) | $8,600–$12,900 | ~$22,000–$26,000 |
| FHA (3.5%) — near city median | $496,000 | $17,360 (3.5%) | $9,900–$14,900 | ~$27,000–$32,000 |
| Conventional (3%) — near city median | $496,000 | $14,880 (3%) | $9,900–$14,900 | ~$25,000–$30,000 |
| Conventional (5%) — mid-range | $525,000 | $26,250 (5%) | $10,500–$15,750 | ~$37,000–$42,000 |
| Conventional (10%) — above median | $575,000 | $57,500 (10%) | $11,500–$17,250 | ~$69,000–$75,000 |
Two things these numbers illustrate clearly: even at the entry level, you're looking at roughly $22,000–$28,000 in total cash to close — before any moving costs or immediate repairs. And at the 10% down tier, that cash requirement climbs steeply.
VA loans are worth flagging here in plain terms: if you or your spouse served in the military, a VA loan requires no down payment and no private mortgage insurance, which changes the cash-to-close picture dramatically. Given Joint Base Lewis-McChord's role in the South Puget Sound economy, a meaningful share of Tacoma's active buyers qualify. Verify eligibility with a VA-approved lender early — it's one of the most underused tools among first-time buyers who happen to qualify.
FHA loans carry an upfront mortgage insurance premium (currently 1.75% of the loan amount) that is typically rolled into the loan balance, plus an annual premium. Conventional loans at less than 20% down carry private mortgage insurance until you reach 20% equity. Neither of these costs is trivial — factor them into your monthly budget when evaluating what price range you can sustain, not just what you can close on.
Looking to buy in Tacoma? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Tacoma quote.
Common First-Time Buyer Mistakes in Tacoma
Mistake 1: Touring Homes Before Getting Pre-Approved
This is the most structurally damaging mistake a first-timer makes in this market. You find a house on a Thursday, fall in love with it, submit your pre-approval application Friday — and it's pending by Saturday morning with someone else's offer. Tacoma's average days-on-market of 8 days is a market-wide average; the homes first-timers typically want move considerably faster. Your pre-approval letter needs to exist before you open Zillow seriously, not after.
Mistake 2: Waiving the Inspection Contingency Without Understanding What That Means
In a competitive offer situation, some buyers waive inspection contingencies entirely to make their offer more attractive. This is a higher-stakes decision in Tacoma than in newer-construction markets. Much of the housing stock in South Tacoma, Central Tacoma, and the Stadium District dates to the mid-20th century or earlier. A pre-offer inspection — hiring your own inspector before you submit — is a better alternative to a full waiver: it lets you compete without contingencies while still understanding what you're buying. Waiving without any prior inspection on a 1950s home near South 38th Street or the Hilltop area is how first-timers end up with a $20,000 electrical surprise in month two.
Mistake 3: Ignoring School Boundary Lines When Buying Near a District Edge
Tacoma Public Schools boundary lines don't follow neighborhood names or zip codes cleanly. Two houses on the same block can feed into different schools depending on where the boundary runs. If school placement matters to your family — now or in the next few years — verify the specific address against the district's current boundary map before you make an offer, not after inspection. Boundaries do shift, but the district's official map is the right starting point. This step is easy to skip when you're moving fast, and it's almost impossible to undo once you've closed.
Mistake 4: Underestimating Total Cash Needed at Closing
First-time buyers frequently focus on the down payment number and treat closing costs as something they'll figure out later. In Pierce County, closing costs on a $496,000 purchase run approximately $9,900–$14,900, depending on the lender and title company. Add to that prepaid homeowners insurance, property tax escrow deposits, and the inspection fee — and "figuring it out later" often means a scramble to liquidate savings accounts the week before closing. Build closing costs into your planning from day one, not as an afterthought.
Local Expert Takeaway: Tacoma's first-time buyer market is competitive enough that your process matters as much as your price. Get pre-approved before you tour a single home, apply to at least two lenders simultaneously to compare real rates, and plan for $22,000–$32,000 in total cash to close at the city's median price point — not just the down payment. If you're connected to JBLM or have military service, verify VA loan eligibility immediately; it's one of the most significant financial tools available in this market and it's consistently underutilized. South Tacoma tends to offer the most accessible entry points for first-timers; the North End and Proctor area is aspirational territory for most initial budgets.
Quick Takeaways & FAQs
✅ Tacoma is meaningfully more affordable than Seattle while still offering Puget Sound access, a waterfront along Ruston Way, and a legitimate urban core — a real value proposition for first-time buyers priced out of the north end of the metro.
⚠️ With inventory at roughly 1.5 months of supply and homes averaging just 8 days on market, Tacoma is a seller's market in 2026 — first-timers who aren't pre-approved before they start touring will lose homes repeatedly before learning this lesson.
📍 Total cash needed at closing in Tacoma typically runs $22,000–$32,000 near the city median when you add down payment plus closing costs — budget for that full figure, not just the down payment percentage.
How long does mortgage pre-approval take in Washington State?
What credit score do I need to buy a home in Tacoma?
Is Tacoma still affordable compared to Seattle for first-time buyers?
Should I waive the home inspection contingency to win a Tacoma offer?
How much cash do I actually need to buy a home in Tacoma as a first-time buyer?
Moving to Washington?
Tell us what you need help with and we'll connect you with local resources.
