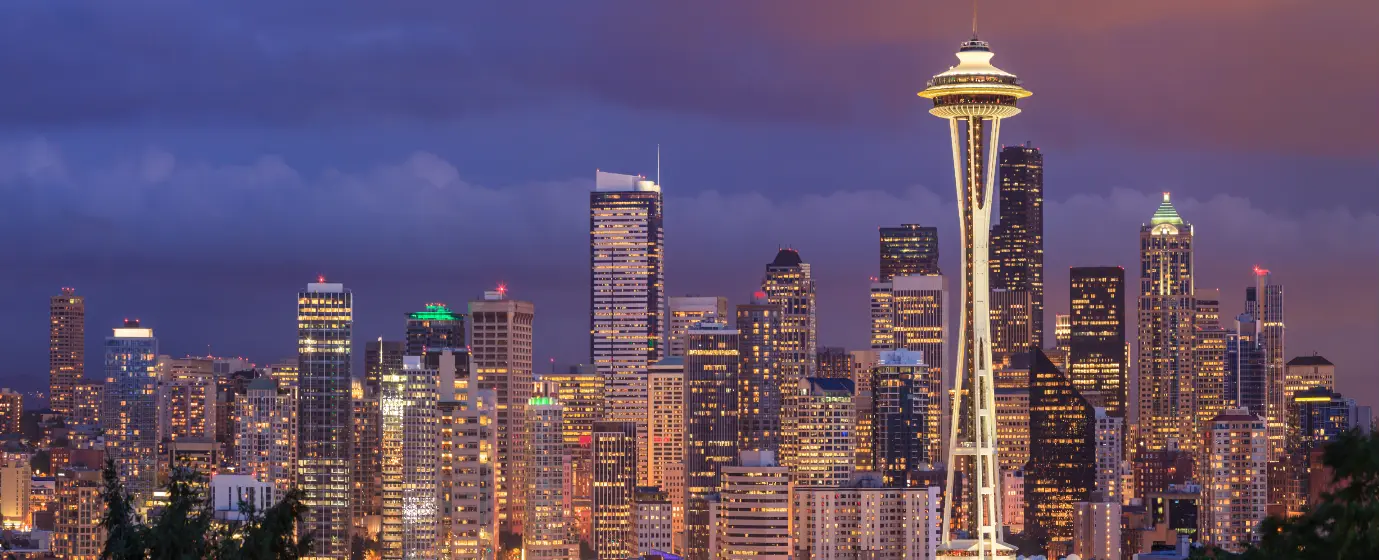
Seattle is one of those cities where the income looks great on paper until you price a house. Amazon, Microsoft, Starbucks, and the University of Washington have collectively pushed median household income to $123,860 — well above most U.S. cities — yet that purchasing power gets absorbed quickly by a housing market that sits in a tier of its own relative to most of the Pacific Northwest. The city is hemmed in by Puget Sound to the west, Lake Washington to the east, and a string of neighborhoods that resist density, which keeps supply tight and prices persistently high.
What surprises most relocators is how selectively expensive Seattle is. Utilities here are genuinely low — the municipal utility Seattle City Light runs rates well below the national average — and the absence of a state income tax puts real money back in your pocket every April. But groceries run noticeably above the national average, the 10.55% combined sales tax is one of the highest in the country, and a two-bedroom apartment rarely dips below $2,400 a month. The math depends heavily on whether you're renting or buying, and where your salary lands relative to the tech-wage floor that shapes so much of the local economy.
For buyers coming from Tacoma or Renton, Seattle's prices represent a significant step up. For anyone arriving from the San Francisco Bay Area or New York, the sticker shock runs the other direction — Seattle can feel comparatively reasonable, even with a typical home value that clears $865,000. The no-income-tax advantage is real, but it comes paired with a sales tax that recaptures some of that savings at the register and a capital gains excise tax that matters if you're selling appreciated assets.
Whether you're deciding between renting in Capitol Hill or buying in West Seattle, or weighing Seattle against Bellevue or Kirkland across the lake, the sections below break down Seattle's housing costs, rent versus buy math, everyday expenses, a comparison with nearby cities, and the full tax picture — so you can run the real numbers before you decide.
What It Really Costs to Live in Seattle
The honest overall posture: Seattle is expensive, but not uniformly so. The typical home value is $865,273 (Zillow Home Value Index, May 2026) — a figure that places Seattle in the same conversation as Portland, Denver, and Boston, and well above state markets like Spokane or the Tri-Cities. What drives that number is a combination of constrained geography, sustained tech-sector demand, and a comparatively small single-family housing stock relative to the population it serves.
Against the broader Washington State average, Seattle runs substantially higher. Against the cities directly across Lake Washington — Bellevue and Kirkland — it's actually close, sometimes cheaper for comparable square footage depending on the product type. Tacoma and Renton represent the most meaningful entry-level relief for buyers who need to stay within commuting distance. Beyond price, the no-income-tax structure and low utility costs partially offset Seattle's high sticker price, making the all-in monthly burden somewhat more manageable than the headline home value implies.
The cost ceiling here is set by tech compensation. When Amazon and Microsoft are the anchor employers, the buyer pool competing against you includes dual-income households earning $300,000 or more. That doesn't mean Seattle is inaccessible — first-time buyers do close here — but it means entry-level inventory moves fast and rarely sits long enough for indecision.
Housing: Rent vs. Buy in Seattle
The Buying Reality
Entry-level ownership in Seattle — older condos, smaller townhomes, houses in need of updating — typically starts in the high $500,000s to low $600,000s city-wide. The median sits at $865,273, which means the middle of the market is firmly in move-up or dual-income territory. Entry-level inventory tends to cluster in the southern and eastern portions of the city; for neighborhood-level specifics, the Best Neighborhoods guide breaks those down in detail.
The effective property tax rate in King County is approximately 0.83% — low by national standards. On a mid-range purchase, that rate keeps the annual tax burden more contained than buyers expect coming from states like Texas or Illinois where 2%–3% rates are common. The engine's mortgage calculator below will let you model the full payment at your specific price point and down payment.
The Renting Reality
Seattle's two-bedroom rent comes in at approximately $2,426 per month as of July 2026 (Apartment List Rent Index) — down about 2.7% year over year, a meaningful softening after years of sharp increases. One-bedrooms average closer to $1,944. That trend matters: Washington State's HB 1217, passed in May 2025, now caps annual rent increases on covered units at the lower of 7% plus inflation or 10% — for 2026, that cap works out to 9.683%, and landlords must give 180 days' notice before raising rent. It's real renter protection that didn't exist before.
Rent vs. Buy: When Each Makes Sense
Renting makes sense if you're new to the city and still learning which neighborhoods fit your life — Capitol Hill and Fremont feel fundamentally different from West Seattle or Wallingford, and choosing wrong on a purchase is costly. Buying makes sense if you have a firm anchor (a job, a school, a community) and a timeline of at least five years. The price-to-rent ratio in Seattle generally favors renting on a pure monthly-cost basis, but buyers betting on long-term appreciation have historically been rewarded here.
Everyday Costs Beyond Housing in Seattle
Two things about Seattle's non-housing costs catch relocators off guard — one pleasant, one not. The pleasant surprise: utilities. Seattle City Light, the city-owned electric utility, charges roughly 15 cents per kilowatt-hour, about 28% below the national average. Combined electricity, water, sewer, and trash runs an estimated $294 per month for a typical household — less than half the national average of $611. If you're arriving from California or the Northeast, your utility bills will feel almost fictional.
The less pleasant surprise: groceries. Seattle's grocery costs run approximately 10.7% above the national average. Shopping at PCC Community Markets or Whole Foods — both genuinely popular here — will push a household budget to $768 or more per month. Anchoring your weekly shop at WinCo, Grocery Outlet, or one of the city's Asian grocery stores brings that figure down meaningfully. Transportation costs split sharply depending on how you get around: a car-free household using an ORCA card on King County Metro, Link Light Rail, and the Seattle Streetcar can manage transit for around $99 a month at the flat $3.00 per-ride fare. Car owners should budget $500–$800 a month once gas, insurance, parking, and Washington's Regional Transit Authority (RTA) vehicle excise tax are combined. That RTA tax — assessed on a car's depreciated value — routinely surprises new residents: on a newer $35,000 vehicle, expect $500–$800 in additional charges at registration time, on top of standard fees.
| Category | Typical Monthly Cost | Notes |
|---|---|---|
| Housing (2BR Rent) | $2,200–$2,600 | Based on July 2026 Apartment List data; owners: use the mortgage calculator above for purchase estimates |
| Utilities | ~$294 | Electricity, water, sewer, trash combined; Seattle City Light rates ~15¢/kWh |
| Groceries | $350–$768 | Lower end reflects WinCo/Grocery Outlet; upper end reflects PCC/Whole Foods household |
| Transportation & Gas | $99–$800 | $99/mo ORCA-only; $500–$800/mo for car owners including RTA excise tax |
| Phone & Internet | $130–$200 | Gigabit internet widely available; phone plan varies by carrier |
| Dining & Entertainment | $200–$500 | Highly discretionary; Pike Place Market area and Capitol Hill run on the higher end |
| Miscellaneous / Personal | $150–$300 | Clothing, gym, subscriptions, incidentals — all estimates |
A car-free renter in a mid-range two-bedroom can expect a realistic all-in monthly budget (excluding housing) of roughly $1,100–$2,000, depending on lifestyle. Add housing, and the floor for a comfortable Seattle existence lands well above $3,500 a month for a single person.
Looking to buy in Seattle? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Seattle quote.
Seattle vs. Nearby Cities: Cost Comparison
| City | Median Home Price | Typical 2BR Rent | Cost vs. Seattle |
|---|---|---|---|
| Seattle | $865,273 | ~$2,426/mo | — Baseline — |
| Bellevue | ~$1,100,000–$1,200,000 | ~$2,700–$3,000/mo | Noticeably higher to buy; modestly higher to rent |
| Kirkland | ~$1,000,000–$1,100,000 | ~$2,500–$2,800/mo | Higher to buy; roughly comparable to rent |
| Shoreline | ~$750,000–$850,000 | ~$2,100–$2,400/mo | Slightly cheaper to buy; comparable to rent |
| Renton | ~$600,000–$700,000 | ~$1,900–$2,200/mo | Meaningfully cheaper to buy and rent |
| Tacoma | ~$400,000–$480,000 | ~$1,500–$1,900/mo | Substantially cheaper across the board |
Tacoma is the most common fallback for buyers priced out of Seattle — the tradeoff is a longer commute into the city, typically 45–60 minutes by car or Sounder commuter rail depending on traffic and destination. Renton offers the closest thing to a middle path: still within King County, linked by the Renton-to-Seattle corridor, and priced noticeably below the city median.
Taxes and the Bottom Line for Seattle
No Income Tax — But Read the Fine Print
Washington has no personal state income tax on wages or salary. You file nothing at the state level for ordinary income. For households moving from California, Oregon, or any state with a 5%–13% income tax bracket, this is a genuine and substantial financial difference — not marketing copy.
The catch is that Washington funds itself elsewhere. The combined Seattle sales tax rate is 10.55% in 2026 — Washington's 6.5% base rate plus 4.05% in city, county, and special-district levies, including a 0.1% public-safety levy that took effect January 1, 2026. That's among the highest combined rates in the country. Groceries and prescription drugs are exempt, which softens the blow for everyday household spending, but every restaurant meal, piece of clothing, and electronics purchase gets taxed at that rate.
Capital Gains and Property Tax
Washington taxes 7% on long-term capital gains above a $278,000 standard deduction for 2025, rising to 9.9% on gains above $1,000,000. This matters primarily for people selling appreciated stock or investment property — not for the typical W-2 Amazon or Microsoft employee, whose stock compensation is treated as ordinary income for federal purposes. Primary home sales are generally excluded.
The effective property tax rate sits at approximately 0.83% — genuinely low by national standards, and lower than what buyers in Texas, New Jersey, or Illinois are accustomed to paying. The Business & Occupation (B&O) gross-receipts tax applies to businesses rather than individuals, but self-employed residents and freelancers should factor it into their planning.
Who Seattle's Budget Fits — and Who Finds It a Stretch
At the typical home value noted earlier, Seattle is realistically a dual-income market for most buyers, or a single-income market for those at the higher end of the tech pay scale. The no-income-tax structure benefits high earners disproportionately — a household earning $250,000 saves far more than one earning $80,000, because the savings scale with income while the high sales tax is roughly flat. Renters in the $90,000–$130,000 income range can live comfortably in Seattle without owning; ownership at the median price point requires either significant savings, a high income, or both. The buyers who tend to find Seattle a persistent stretch are single-income households in service industries, teachers, and anyone whose salary hasn't been calibrated to tech-sector norms — the city's cost structure was largely built around Amazon's compensation floors, and everyone else is working around that reality.
Local Expert Takeaway: Seattle's cost structure has a specific logic to it: housing and sales tax are high, utilities and property taxes are low, and income tax is zero. The households that fare best here are dual-income tech workers who can walk or take Link Light Rail to work, shop at WinCo instead of PCC, and plan to hold a purchase for at least seven years. If you're renting and commuting by ORCA card, the monthly burn is more manageable than the headline home price implies. If you're buying solo on a non-tech salary and financing close to the typical home value, Seattle will require real financial discipline — the math works, but it doesn't leave much room.
Quick Takeaways & FAQs
✅ Washington has no state income tax on wages — a real, substantial advantage for high earners relocating from California or Oregon.
⚠️ The combined Seattle sales tax rate of 10.55% is among the highest in the country and partially offsets the income-tax savings, especially for lower-to-middle income households.
📍 Seattle City Light's electricity rates run roughly 28% below the national average, making utilities one of the most surprising budget wins in an otherwise expensive city.
What is the typical home price in Seattle right now?
How much does it cost to rent a two-bedroom apartment in Seattle?
Does Washington State have an income tax?
Are utilities expensive in Seattle?
How does Seattle's cost of living compare to Bellevue and Tacoma?
Moving to Washington?
Tell us what you need help with and we'll connect you with local resources.
