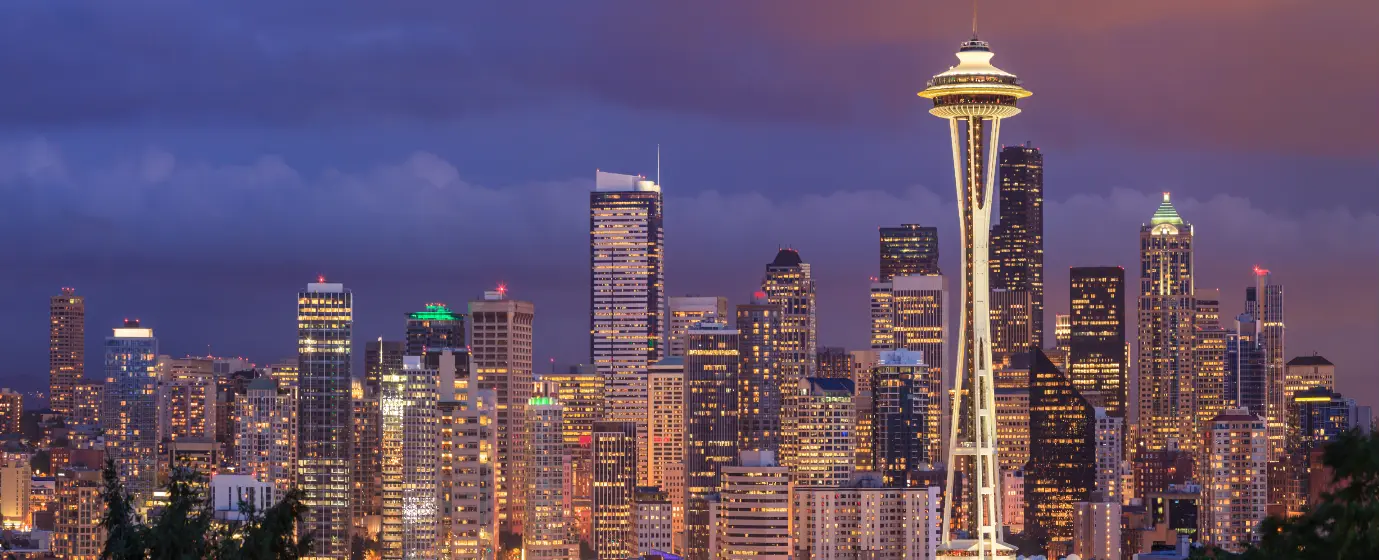
Maybe you've spent thirty years in a suburb and Seattle has always been the city you drove to on weekends. Maybe you're coming from California and the no-income-tax headline caught your attention. Or maybe you're already here, the kids have moved out, and you're trying to figure out whether this city — which can feel built for thirty-year-olds in tech — actually works in retirement. The honest answer is: it depends almost entirely on what you can afford and where you plan to live within it. The Zillow Home Value Index put the city's typical home value at $865,273 in May 2026. That number sets the stakes before you read anything else.
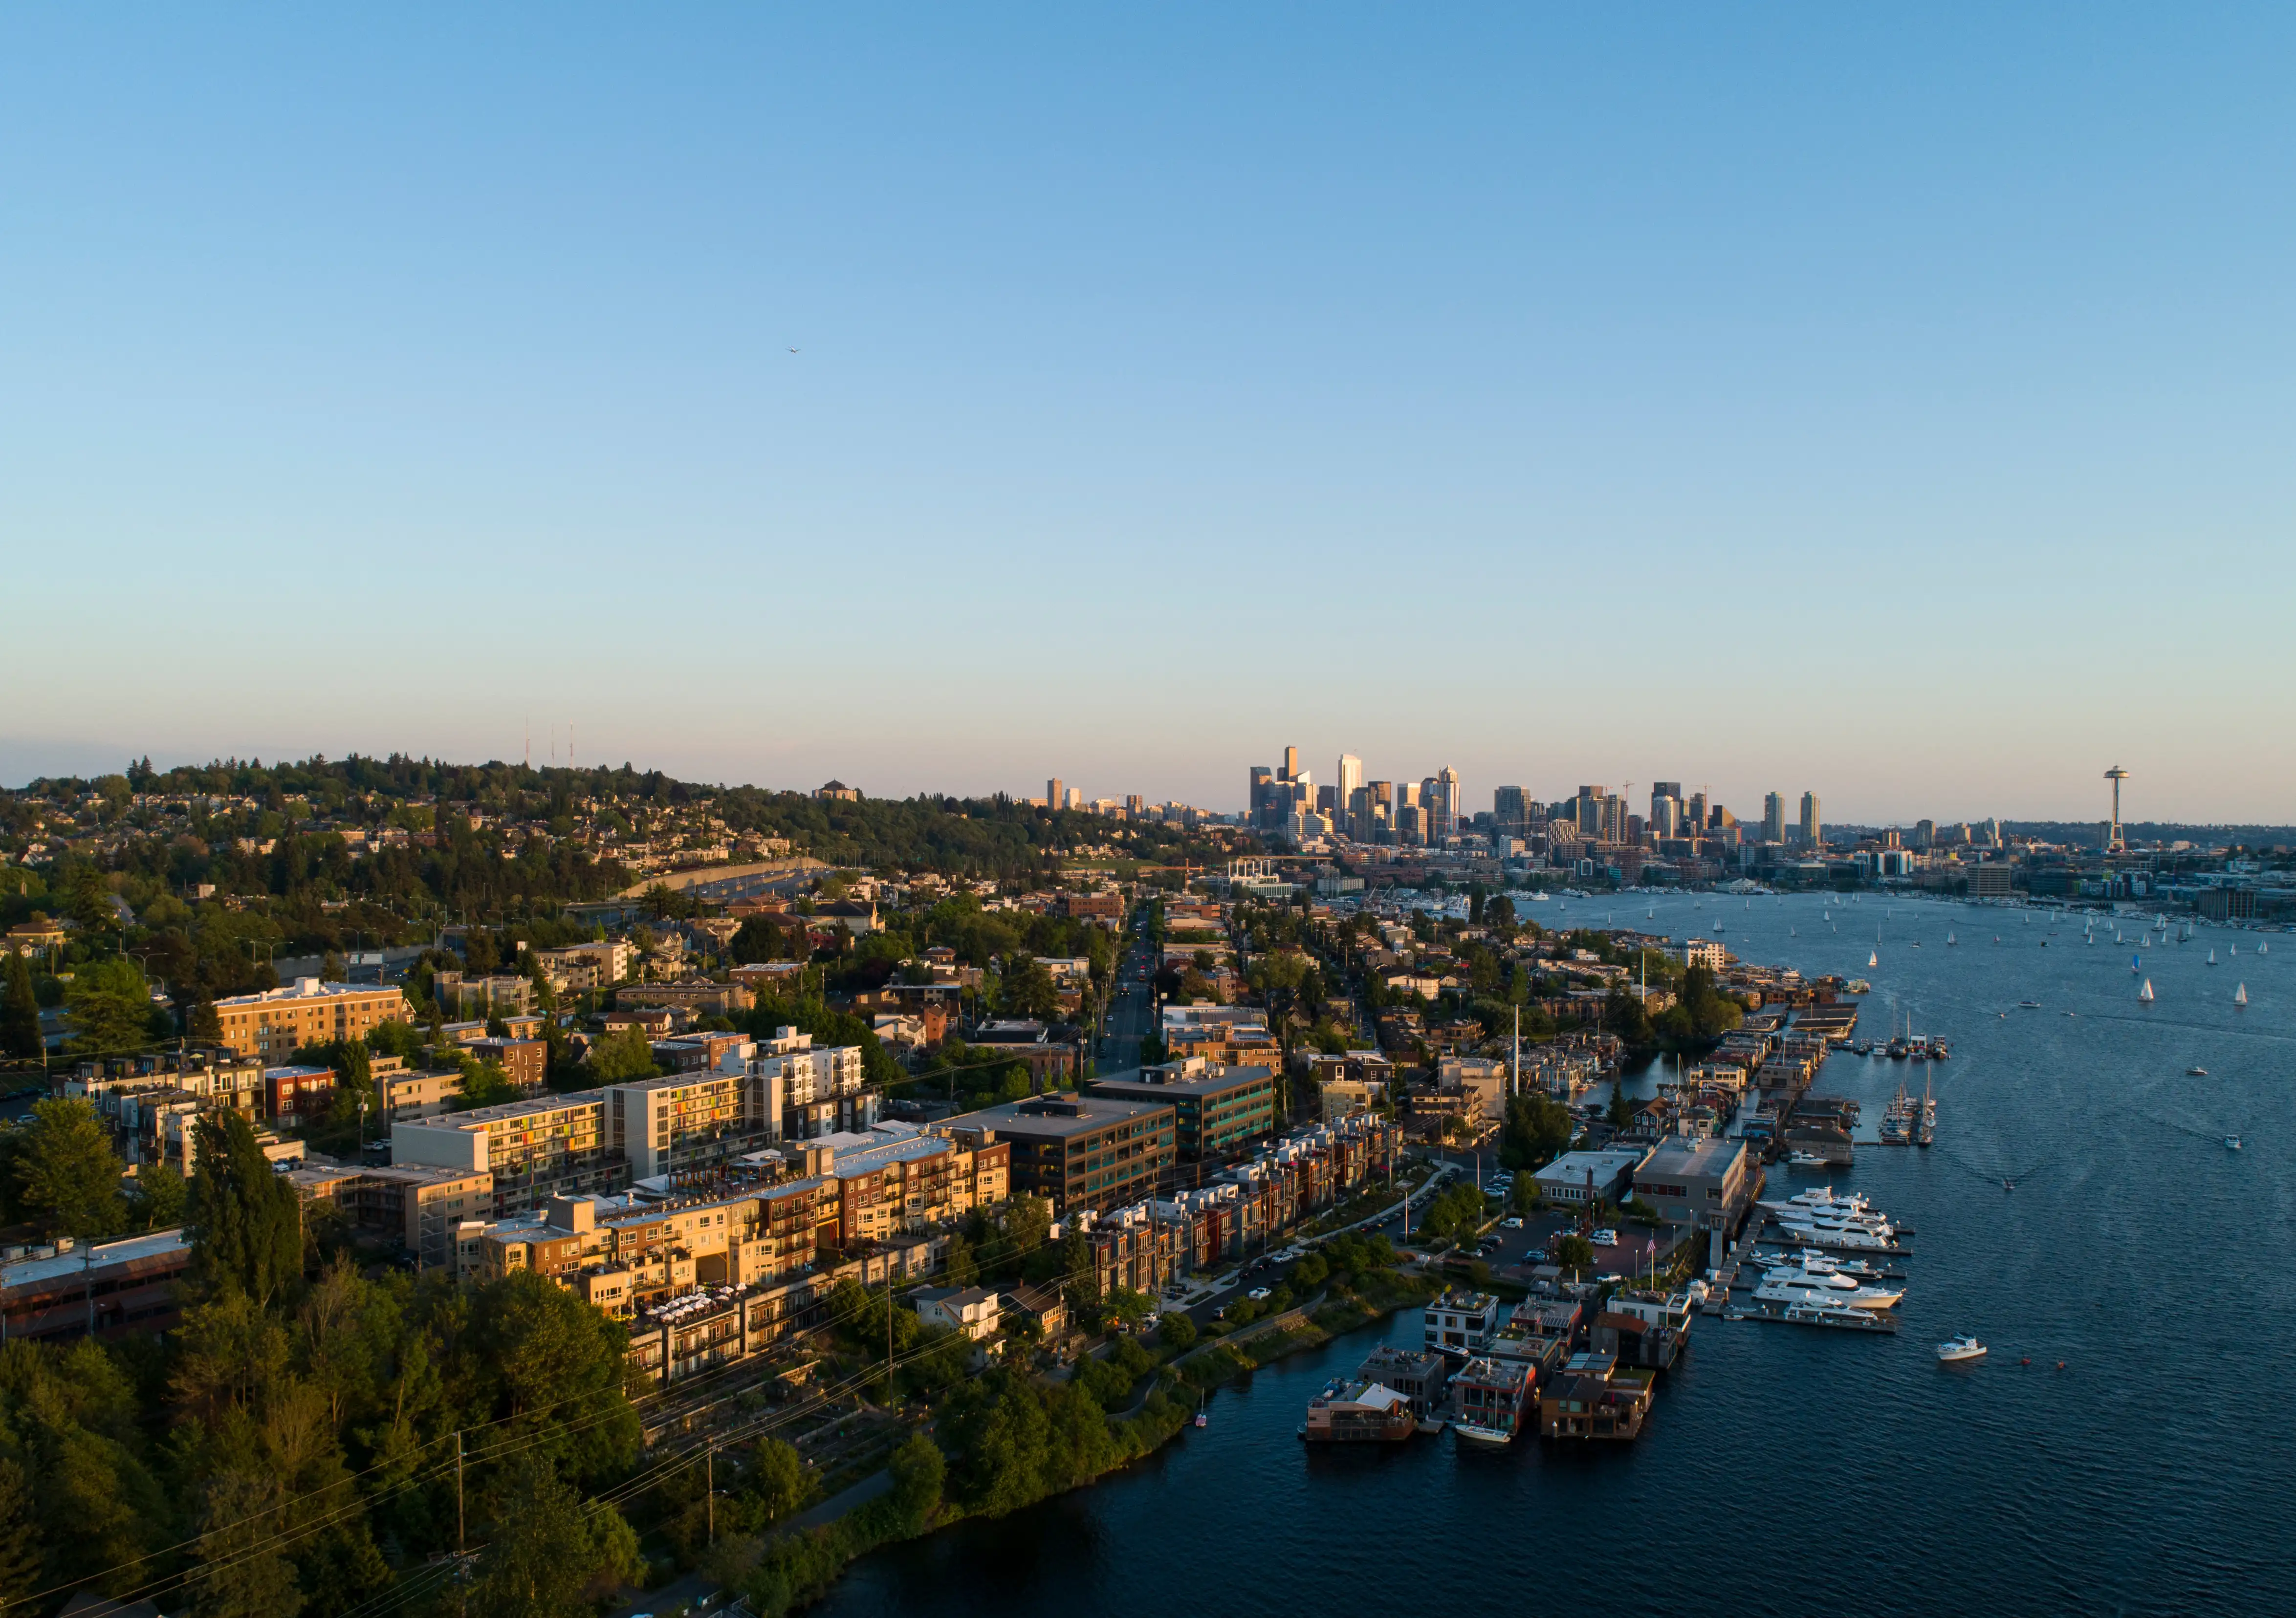
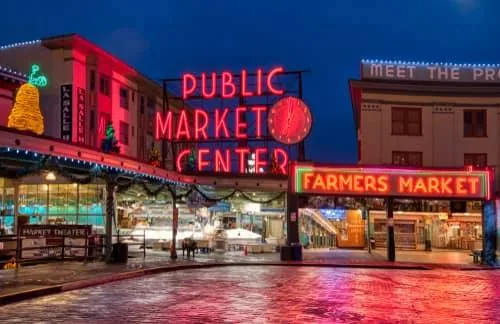
What Seattle offers retirees that few cities its size can match is a genuine combination of world-class medical infrastructure, zero state income tax on retirement income, and a transit network robust enough that car-free or car-light living is realistic in several neighborhoods. The Puget Sound waterfront, the Olympic Mountains on clear days, Pike Place Market on a Tuesday morning — these aren't brochure clichés if you actually live here. The city draws retirees who want urban density alongside natural access, people who miss the Pacific Northwest after years away, and couples who want to be close to family members working at Amazon or the University of Washington.
Cost of living is Seattle's most honest counterargument to itself. Housing sits roughly 104% above the U.S. average, and healthcare services run approximately 20% above the national average. Groceries cost about 11% more than the national norm. On a fixed income, Seattle demands either significant assets, meaningful equity from a prior home sale, or a willingness to right-size aggressively. Retirees who arrive expecting to stretch a moderate budget the way they might in Tacoma or Renton will find the math unforgiving. Those who arrive debt-free with home equity to deploy often find the city surprisingly livable — especially once they understand the transit discounts and the tax picture.
Whether you're seriously considering a move here or evaluating Seattle against other Pacific Northwest retirement options, the sections below cover healthcare access, the retiree tax picture, daily budget reality, walkability, downsizing pathways, and a clear-eyed comparison with nearby retirement destinations.
Why Retirees Are Choosing Seattle
The retirees who thrive here tend to share a few traits: they want a walkable urban life, they have the assets to absorb the cost, and they genuinely value proximity to top-tier medical care. Seattle is not a retirement destination you choose by default. You choose it deliberately, usually because something specific keeps pulling you back — family nearby, a physician you trust, or a neighborhood you already love.
Washington's zero state income tax on retirement income is a real and substantial reason people land here from California, Oregon, and other high-tax states. Social Security, pensions, IRA withdrawals, 401(k) distributions — none of it is taxed at the state level. For a couple drawing $90,000 a year in retirement income, that difference is material. Washington does levy a capital gains tax, but it applies only to taxable investment gains above a set threshold held outside retirement accounts, so the typical retiree living on Social Security and retirement-account draws won't owe it.
Seattle is probably not the right fit if your retirement budget is tight, you rely heavily on driving, or you're sensitive to gray weather from November through March. The city gets real winter darkness — not snow, but a low-ceiling overcast that lasts for months. Retirees who grew up in the Sun Belt often underestimate this. And the typical home value of $865,273 (Zillow Home Value Index, May 2026) means that the neighborhoods with the best walkability carry a price premium that squeezes fixed incomes. If cost flexibility matters more than urban amenities, Tacoma or Shoreline will serve you better without requiring you to leave the region.
Healthcare & Medical Access in Seattle
A Medical Infrastructure Built for Complexity
For most retirees, healthcare access is the single most consequential factor in a retirement location decision. Seattle's position here is genuinely strong. The city is home to one of the country's major academic medical centers — the University of Washington Medical Center — which operates multiple campuses including Harborview Medical Center, the only Level I trauma center in a multi-state region covering Washington, Wyoming, Alaska, Montana, and Idaho. That reach matters if you ever need emergency intervention or specialized surgical care.
Providence Swedish Health Services anchors much of the non-academic specialty care in the city, operating multiple hospitals and dozens of clinics across the metro area, including a well-regarded neuroscience institute and a cancer care network. Virginia Mason Franciscan Health adds another system with deep specialty depth, particularly in orthopedics and digestive disease — conditions that become more relevant as you age. For most complex diagnoses, you will not need to leave the city to find subspecialty care. That is not true of most places retirees consider in the Pacific Northwest.
Medicare Coverage and Plan Depth
King County's Medicare landscape is competitive. In 2026, Seattle residents could choose from 37 Medicare Advantage plans, with 15 carrying a $0 premium. Fourteen of those plans are rated four stars or higher by Medicare — a sign of real market quality, not just quantity. Approximately 53.6% of King County's 361,153 Medicare beneficiaries have enrolled in Medicare Advantage, suggesting that the plan quality is strong enough that most local seniors trust it over traditional Medicare alone.
The practical implication: if you're arriving from a rural area or a smaller metro, you'll find more plan options here, more in-network specialists, and shorter waits for diagnostic appointments than you may be used to. The downside is cost — Seattle's healthcare services run approximately 20% above the national average, and even with Medicare, out-of-pocket exposure on supplemental plans and prescriptions will be higher than in lower-cost metros. Budget accordingly.
What to Know Before You Move
Establish care early. Seattle's primary care shortage is real — popular practices in walkable neighborhoods like Wallingford or Green Lake often have waiting lists for new patients. If you have existing specialists, verify in-network status before you commit to a plan. And if advanced cardiac or oncology care is already on your radar, confirm which UW Medicine or Swedish campus is closest to where you plan to live — a 15-minute drive from Queen Anne to Harborview is very different from a 45-minute trip from West Seattle on a bad day.
The Retiree Budget in Seattle
Washington's Tax Advantage Is Real
Washington has no personal income tax, full stop. Every dollar of Social Security, pension income, IRA withdrawal, and 401(k) distribution arrives in your account without a state income tax line. For retirees moving from states like California, Oregon, or Minnesota, this shift alone can meaningfully change the math on how far retirement income stretches. Washington's estate tax exemption rose to $3,000,000 per person as of July 1, 2026 — high enough that most retirees' estates will fall well below the threshold where state estate tax applies.
The effective property tax rate in Seattle sits at approximately 0.83% — moderate by national standards. On a cost-of-living basis, though, Seattle runs approximately 44% above the national average overall, with housing the dominant pressure point. The tax efficiency Washington offers is real, but it does not offset the premium cost of Seattle housing on its own. Retirees who benefit most from the tax picture are those who arrive with significant equity from a prior home sale — enough to buy into the Seattle market without carrying a mortgage into their seventies.
Daily Life on a Fixed Income
Groceries running 11% above the national average sounds manageable, and for most retirees it is. The larger budget pressures in daily Seattle life are dining, parking (if you keep a car), and the occasional necessity of paying premium prices for any contractor or home-service provider. Seniors 65 and older qualify for a reduced flat fare on King County Metro transit via a regional senior discount card — Medicare cardholders automatically qualify. That discount makes transit practical for everyday errands in neighborhoods with good bus service, and it meaningfully reduces the cost of city life for retirees willing to lean on it. Full cost-of-living figures and rent ranges are covered on the cost-of-living page.
Looking to buy in Seattle? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Seattle quote.
Walkability, Community & Staying Active in Seattle
The Walking Reality
A July 2025 study named Seattle the most walkable city in the United States, finding five major landmarks — including Pike Place Market, the Seattle Great Wheel, and Kerry Park — within a 1.4-mile loop coverable in about 32 minutes. That is a meaningful credential. It is also worth reading carefully: Seattle's walkability is real in its flat or gently graded corridors and genuinely difficult in its hillier sections. Capitol Hill's steep streets, Queen Anne's dramatic elevation changes, and the climb from the waterfront into Pioneer Square are not theoretical — they are physically demanding routes that some retirees find limiting over time.
Capitol Hill carries a Walk Score of 93 and is served by Link Light Rail, putting daily errands, medical appointments, and cultural venues within reach without a car. Green Lake and Wallingford offer a flatter, quieter version of walkable Seattle life — the 2.8-mile path ringing Green Lake is one of the city's most used outdoor amenities and draws a genuinely multigenerational crowd, including a visible contingent of older adults walking, cycling, and socializing. Ballard's main commercial strip gives retirees independent bookshops, seafood markets, and coffee shops within a few blocks of quieter residential streets. For more on trails and parks, see the parks and recreation page.
Senior Centers and Community Life
Seattle's Department of Parks and Recreation operates several senior centers across the city, including Bitter Lake Community Center, Rainier Community Center, and the Central Community Center near Capitol Hill. These are not afterthoughts — they offer fitness classes, social programming, computer access, and meal programs. The senior center in Greenwood draws a particularly active crowd for its arts programming and low-key social calendar.
SDOT's Senior Programming, launched in 2019 and expanded in 2023, partners with nonprofit Hopelink and senior centers citywide to offer transit education for older adults in culturally appropriate and language-appropriate formats. For retirees arriving from outside the region who feel uncertain about navigating King County Metro and Link Light Rail, this is a tangible on-ramp. Seattle also has robust volunteer infrastructure through organizations like Senior Services of Seattle-King County, which connects retirees with community engagement opportunities across the city.
What Locals Don't Warn You About
After six months here, many newly retired Seattle residents say the same thing: the social scene is harder to break into than they expected. The city has a reputation — sometimes called the "Seattle Freeze" — for polite but slow-to-warm social dynamics. Senior centers help. So do neighborhood-specific events like the Ballard Farmers Market or the weekend programming at the Seattle Center near Queen Anne. Joining intentionally matters here more than in cities where neighbors introduce themselves on day one.
Right-Sizing: Downsizing in Seattle
The Condo Opportunity
Seattle's condo market went through a notable correction in early 2026, creating a window for downsizers that the prior few years didn't offer. Buyers seeking walkable urban buildings — the kind where the pharmacy and the coffee shop are on the ground floor — found less bidding-war pressure than had defined the market since 2021. That doesn't mean condos are cheap; in Capitol Hill, Belltown, and South Lake Union, well-maintained one- and two-bedroom units still carry price tags that reflect Seattle's overall housing premium. But the negotiating dynamic shifted toward buyers, which matters if you're arriving with equity and a clear sense of what you want.
Single-level living in Seattle proper is harder to find in detached housing than in most Sun Belt retirement markets. The city's hillside lots and older housing stock mean that many smaller homes have split entries, basement levels, or steep driveways that become inconvenient as mobility changes. Retirees who prioritize single-level, step-free living often find condos or newer townhome buildings to be the more practical path — particularly in neighborhoods like Columbia City, where newer mixed-use construction includes elevator-access units at somewhat more accessible price points than Capitol Hill or Queen Anne.
55+ and Active-Adult Options
Purpose-built 55+ communities within Seattle's city limits are limited compared to suburban markets or sunnier retirement destinations. The city has several continuing care retirement communities (CCRCs) and independent living campuses — including well-established options in the central neighborhoods near Wallingford and the medical district — that offer tiered care from independent living through assisted care on a single campus. These are not inexpensive options; monthly fees at this tier of community in Seattle typically reflect the city's overall cost premium.
Retirees open to the broader metro area find more variety. Shoreline, just north of the city limits along Aurora Avenue, has seen active-adult condominium development at lower price points than Seattle proper, with King County Metro access that makes downtown Seattle reachable without a car. Kirkland and Renton both have 55+ communities within 30 minutes of Seattle's medical centers. If the goal is to stay close enough to Seattle's healthcare infrastructure while right-sizing at a more manageable cost, the inner-ring suburbs are worth serious evaluation alongside the city itself.
Seattle vs Nearby Retirement Destinations
| City | Cost vs Seattle | Primary Hospital | Walkability | Senior Living Depth | Overall Retirement Fit |
|---|---|---|---|---|---|
| Seattle | Baseline | UW Medical Center / Harborview / Swedish | Excellent in flat corridors; hilly in others | Moderate — CCRCs strong, 55+ communities limited | Walkable Transit Best for asset-rich, urban-lifestyle retirees |
| Bellevue | About the same, sometimes pricier | Overlake Medical Center | Good in downtown core; car-dependent in suburbs | Strong — several established senior communities | Luxury Quiet Best for those who prefer suburban calm with city access |
| Kirkland | Noticeably cheaper than Seattle | EvergreenHealth (Kirkland campus) | Moderate — waterfront walkable, outer areas less so | Good — growing 55+ inventory on Eastside | Views Value Best for retirees prioritizing Lake Washington setting and Eastside convenience |
| Shoreline | Noticeably cheaper | Close access to Seattle systems via I-5 | Moderate — Aurora corridor improving with transit | Growing — newer active-adult condo development | Value Commuter Best for budget-conscious retirees who still want Seattle healthcare proximity |
| Renton | Meaningfully cheaper | Valley Medical Center (UW Medicine affiliate) | Limited outside downtown core | Solid — established 55+ communities in south King County | First-time downsizers Value Best for retirees prioritizing space and affordability over urban walkability |
| Tacoma | Substantially cheaper | MultiCare Tacoma General / St. Joseph Medical Center | Good in Stadium District and downtown; patchy elsewhere | Strong — diverse senior living stock at lower price points | Value Nature Best for retirees who want Pacific Northwest lifestyle without Seattle pricing |
On pure cost, Tacoma is the most compelling alternative to Seattle proper — it offers genuine downtown walkability, a growing arts and dining scene, and senior living options at price points that make a fixed income feel far less strained. Shoreline wins on proximity: you keep nearly all of Seattle's healthcare access while paying meaningfully less for housing, and the planned light rail expansion along the north corridor will eventually tighten that connection further.
Kirkland and Bellevue suit retirees who prefer the Eastside's quieter suburban character and don't mind driving more, but neither solves the cost problem the way Tacoma or Renton does. If advanced specialty care is a priority and you want to stay in a true urban environment, Seattle itself — specifically its condo market and established CCRCs — remains the strongest single option in the region. The question is whether the budget supports it.
Local Expert Takeaway: Seattle rewards retirees who arrive with a clear plan, not just a general preference for the Pacific Northwest. The zero-income-tax advantage is real, the medical infrastructure at UW Medical Center and Swedish is genuinely world-class, and neighborhoods like Green Lake and Wallingford offer flat, transit-served daily life that works without a car. But the typical home value — $865,273 as of mid-2026 — means that right-sizing aggressively, whether into a condo in Columbia City or a continuing care community near Wallingford, is not optional for most retirees. Establish primary care early, get your senior transit discount card on day one, and don't underestimate how much the city's social culture rewards intentional community-building over waiting for neighbors to knock.
Quick Takeaways & FAQs
✅ Washington has no state income tax on Social Security, pensions, or retirement-account withdrawals — a meaningful advantage for retirees relocating from California or Oregon.
⚠️ Seattle's cost of living runs approximately 44% above the national average, and even the city's 2026 condo correction hasn't made walkable urban neighborhoods affordable on a modest fixed income.
📍 Seniors 65+ qualify for a reduced flat fare on King County Metro buses and Link Light Rail via a regional senior discount program — Medicare cardholders qualify automatically.
Is Seattle a good place to retire on a fixed income?
What hospitals and medical systems serve Seattle retirees?
Does Washington State tax retirement income?
What are the best neighborhoods in Seattle for retirees?
Are there 55+ or active-adult communities in Seattle?
Moving to Washington?
Tell us what you need help with and we'll connect you with local resources.
