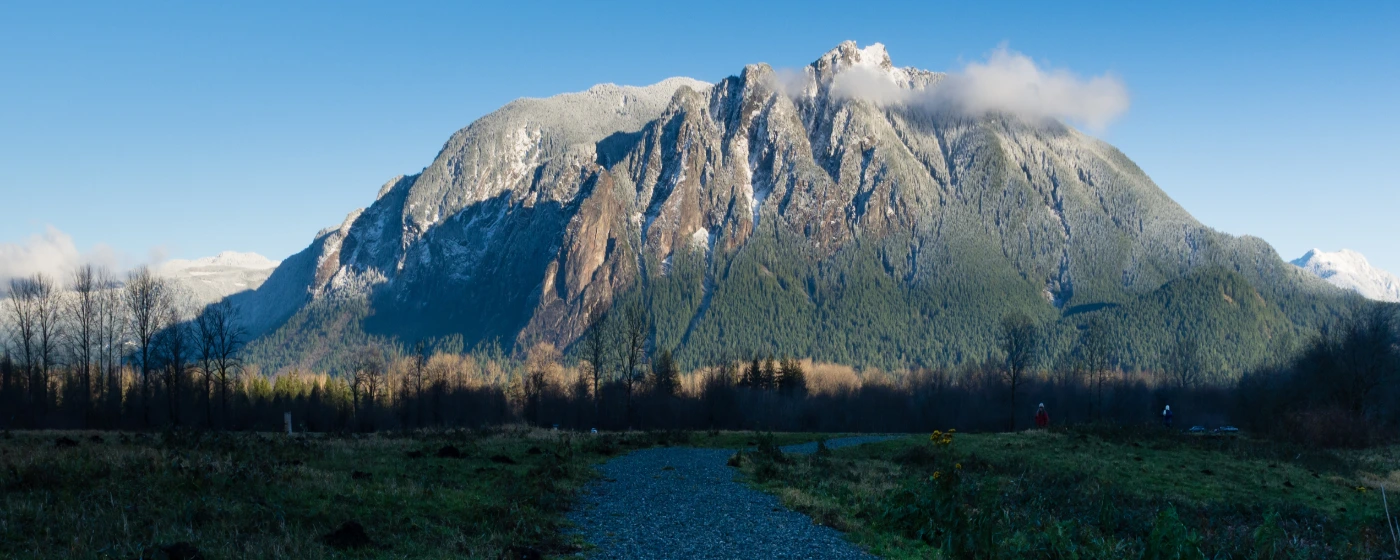
Maybe you've been priced out of Bellevue or Issaquah, and someone mentioned North Bend as the place where you can still get a single-family home with a yard and a mountain view. Maybe you drove out on I-90 one weekend and fell for it — the Cascade foothills rising behind the outlet stores, the small-town pace twenty minutes past the suburbs. The reality is more complicated than the scenery suggests. North Bend is one of the most competitive small markets in King County, and coming in without a clear-eyed budget is the fastest way to waste months of weekends.
The city sits at the base of Mount Si along I-90, roughly 45 minutes east of Seattle and Bellevue — close enough for a daily commute, far enough that you're trading urban convenience for elbow room and elevation. With just over 8,000 residents, it functions more like a small town with big-city price pressure than a classic suburb. The combination of foothills scenery, relatively lower density, and strong local schools consistently draws families with school-age children, adding another layer of competition to an already thin inventory.
Cost of living here is emphatically not a discount on Seattle — it is an alternative lifestyle at a similar price point. The median household income in North Bend is $175,109, and the buyers who succeed in this market are typically financially prepared well before they start touring homes. For a full breakdown of taxes, utilities, and day-to-day costs, see the cost of living in North Bend page.
Whether you're committing to the foothills or still weighing your options, this guide covers the first-time buyer reality in North Bend, the step-by-step purchase process, a concrete budget snapshot, and the specific mistakes that trip up newcomers to this market.
The North Bend First-Time Buyer Reality
The median sold price in North Bend is $1,287,230 (Redfin, May 2026). That number lands most first-time buyers in a tight spot: it pushes well past what many people picture when they think of a foothills escape from Seattle prices. Entry-level in this market — think older construction, smaller square footage, or a condo — starts closer to the $750,000–$850,000 range, and competition at that tier is fierce.
Redfin scores North Bend's market 76 out of 100 on its Compete Score, rating it "very competitive." Homes are selling in approximately 29.5 days on market. Inventory is razor thin: at any given moment, roughly 81 homes are listed across all types, with only about 13 being single-family homes. When a reasonably priced property hits the Northwest Multiple Listing Service (NWMLS), it doesn't sit.
What does that mean practically? A first-time buyer who hasn't done their financial homework before stepping into a showing is already behind. The buyers winning offers here have a pre-approval letter in hand, know their ceiling, and can move in days — not weeks. Nearby Snoqualmie offers more inventory and a somewhat different price profile, and is worth comparing before you narrow your search exclusively to North Bend.
The Homebuying Process in North Bend, Step by Step
Step 1: Get Pre-Approved — Before You Tour Anything
In North Bend, sellers and listing agents expect to see a pre-approval letter before they'll take your offer seriously. In this market, it's often expected before you even schedule a showing. Pre-approval is not the same as pre-qualification: a lender actually reviews your credit, income, employment history, debt load, and assets — not just your self-reported estimates. The resulting letter states the loan amount you qualify for and is typically valid for 60 to 90 days.
You can apply to multiple lenders within roughly a 45-day window with minimal impact on your credit score — rate-shopping is smart. Once you've compared offers, commit to one lender to lock a rate. Bring W-2s, recent pay stubs, two months of bank statements, and tax returns from the past two years to speed the process.
Step 2: Find a Local Agent and Define Your Search
Not all agents know the difference between Tanner and Tannerwood, or why the Si View area draws different buyers than Cascade Canyon. An agent with active experience in the 98045 zip code will flag HOA structures you might not anticipate, and know which listings are likely to attract multiple offers within 48 hours.
Step 3: Make an Offer — Fast and Clean
When a home you like hits the NWMLS in North Bend, you typically don't have the luxury of sleeping on it for a week. Offers in competitive situations often include escalation clauses — a mechanism that automatically increases your bid up to a ceiling if competing offers come in. Talk through escalation strategy with your agent before you need it, not during an active offer weekend.
Step 4: Inspection and Appraisal
Washington State offers buyers a standard inspection contingency, and first-timers should almost never waive it — more on that in the Mistakes section. Budget for a general home inspection ($450–$600 in this market range) plus any specialist inspections your inspector recommends: sewer scope, radon, or structural review for older construction. The appraisal is lender-ordered and protects both you and the bank from overpaying; if a home appraises below purchase price, you'll need to negotiate, cover the gap in cash, or walk.
Step 5: Closing
Washington is a title-company-escrow state, not an attorney-close state. Your escrow officer coordinates the final paperwork, title transfer, and disbursement of funds. Closing typically takes 30–45 days from accepted offer. You'll do a final walkthrough 24–48 hours before signing to confirm the home's condition hasn't changed since inspection.
The step first-timers most often underestimate: how much cash they need on closing day beyond the down payment. Closing costs typically run 2–3% of the purchase price in Washington — a figure that can catch buyers off guard at this price point. Budget for it from the start.
How Much Home Can You Afford in North Bend
The table below shows estimated cash requirements at different purchase prices, using two common loan structures. These are illustrative estimates — actual figures will vary based on your lender, credit profile, and negotiated seller concessions. The interactive mortgage calculator below the table lets you run your own numbers with current rates.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (2–3%) | Est. Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5%) — entry condo/townhome | $750,000 | $26,250 (3.5%) | $15,000–$22,500 | ~$41,000–$49,000 |
| Conventional (3%) — entry single-family | $850,000 | $25,500 (3%) | $17,000–$25,500 | ~$43,000–$51,000 |
| Conventional (5%) — mid-range single-family | $1,000,000 | $50,000 (5%) | $20,000–$30,000 | ~$70,000–$80,000 |
| Conventional (10%) — near-median home | $1,100,000 | $110,000 (10%) | $22,000–$33,000 | ~$132,000–$143,000 |
| Conventional (10%) — at city median | $1,287,230 | $128,723 (10%) | $25,745–$38,617 | ~$154,000–$167,000 |
| Conventional (20%) — at city median, no PMI | $1,287,230 | $257,446 (20%) | $25,745–$38,617 | ~$283,000–$296,000 |
A 20% down payment eliminates private mortgage insurance (PMI), which meaningfully reduces your monthly payment on a home at this price. Buyers putting down less than 20% on a conventional loan will carry PMI until they reach that equity threshold.
Washington has no state income tax, which improves take-home pay relative to many markets buyers relocate from. Property taxes in North Bend run at an effective rate of approximately 0.83% — see the cost of living page for the full tax picture.
Looking to buy in North Bend? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a North Bend quote.
Common First-Time Buyer Mistakes in North Bend
Waiving the Inspection Contingency to Win an Offer
When homes sell in under 30 days and multiple-offer situations are common, first-timers sometimes feel pressured to waive inspection to compete. In North Bend — where older construction in areas like Downtown North Bend and Si View can carry deferred maintenance, and where sewer lines serving hillside properties deserve professional evaluation — skipping an inspection is a risk that almost never pays off for a first-time buyer. There are ways to signal strength without abandoning your right to know what you're buying: a pre-inspection on publicly accessible systems, or a shorter inspection period rather than a full waiver, can help your offer stand out while preserving critical protections.
Shopping Without Pre-Approval
This bears repeating because it happens constantly. Buyers fall in love with a home on E North Bend Way or in the Riverbend area, then spend two weeks scrambling to get a pre-approval letter — only to find the seller already accepted another offer. Listing agents here will sometimes decline to schedule showings for buyers without documentation in hand. In a market with only roughly 13 single-family homes listed at any given time, the window between a listing going live and an offer being accepted can be measured in days, not weeks.
Underbudgeting for Closing Costs
First-time buyers often fixate on saving the down payment and forget that closing costs add another 2–3% on top. On a $1,000,000 purchase, that's an additional $20,000–$30,000 due at the closing table — cash that can't come from the mortgage itself. Buyers who don't budget this separately sometimes have to scramble or renegotiate at the last minute. Start saving for both figures simultaneously, from day one.
Not Accounting for North Bend's Seasonal Realities Before Making an Offer
North Bend's foothills location brings genuine winter weather that surprises buyers who moved from closer-in suburbs. A January snowstorm can strand you on a hillside driveway that looks perfectly manageable in August. Before you make an offer on any property with a steep driveway or an elevation above the valley floor, drive it in the rain — and talk to your agent about what winters actually look like for that specific street. What reads as seclusion on a sunny weekend tour can feel like isolation by February.
Local Expert Takeaway: North Bend rewards buyers who do the work upfront. Get pre-approved before you book a single showing, know your true cash-at-close number (down payment plus closing costs), and do not waive your inspection on a foothills home just to win a bidding war. The buyers who move slowly on preparation and quickly on offers — rather than the reverse — are the ones who actually close here. Before diving into your next search weekend, it's worth walking the North Bend Premium Outlets area to get a feel for where the town centers itself — that geographic anchor tells you a lot about which neighborhoods actually suit your daily rhythms.
Quick Takeaways & FAQs
✅ North Bend's entry-level single-family market starts around $750,000–$850,000, but with only roughly 13 single-family homes listed at any given time, buyers without pre-approval often miss the homes they want before they can even schedule a tour.
⚠️ Closing costs in Washington typically run 2–3% of the purchase price — on a $1,000,000 home that's up to $30,000 on top of your down payment, a number many first-timers don't budget for until it's too late.
📍 North Bend's hillside properties and older Si View construction deserve specialist inspection attention — a sewer scope and structural review are worth the extra cost before you commit at this price point.
What is the minimum down payment to buy a home in North Bend, WA?
How competitive is the North Bend housing market for first-time buyers?
Should I get pre-approved before touring homes in North Bend?
What are typical closing costs when buying in North Bend?
Is North Bend a good place to buy as a first-time homebuyer compared to nearby Snoqualmie or Issaquah?
Moving to Washington?
Tell us what you need help with and we'll connect you with local resources.
