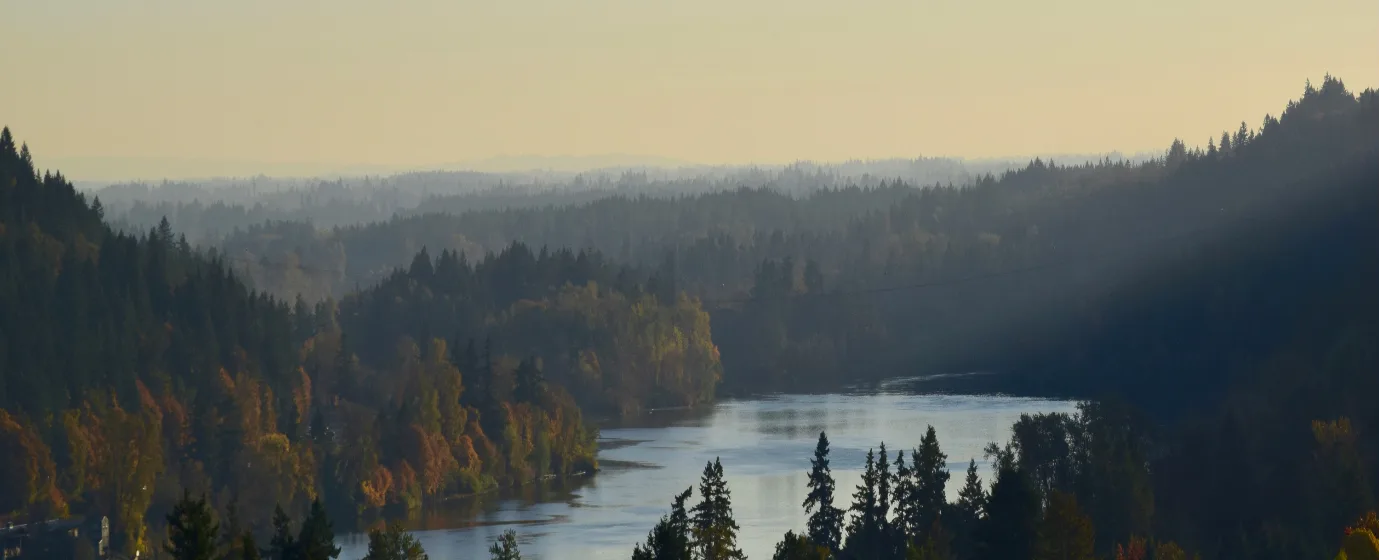
Maybe your company sends you toward Portland and someone tells you West Linn is where the families with school-age children end up. Maybe you've been watching Lake Oswego prices and someone mentions the city just across the Tualatin River. Either way, arriving at West Linn's numbers for the first time tends to produce the same reaction: genuine sticker shock, followed quickly by the recognition that the lifestyle here — Willamette River access, trails threading through neighborhoods, a walkable historic district, and one of the Portland metro's more respected school districts — commands a real premium. That tension between what you want and what it costs is the central fact of buying here as a first-timer.
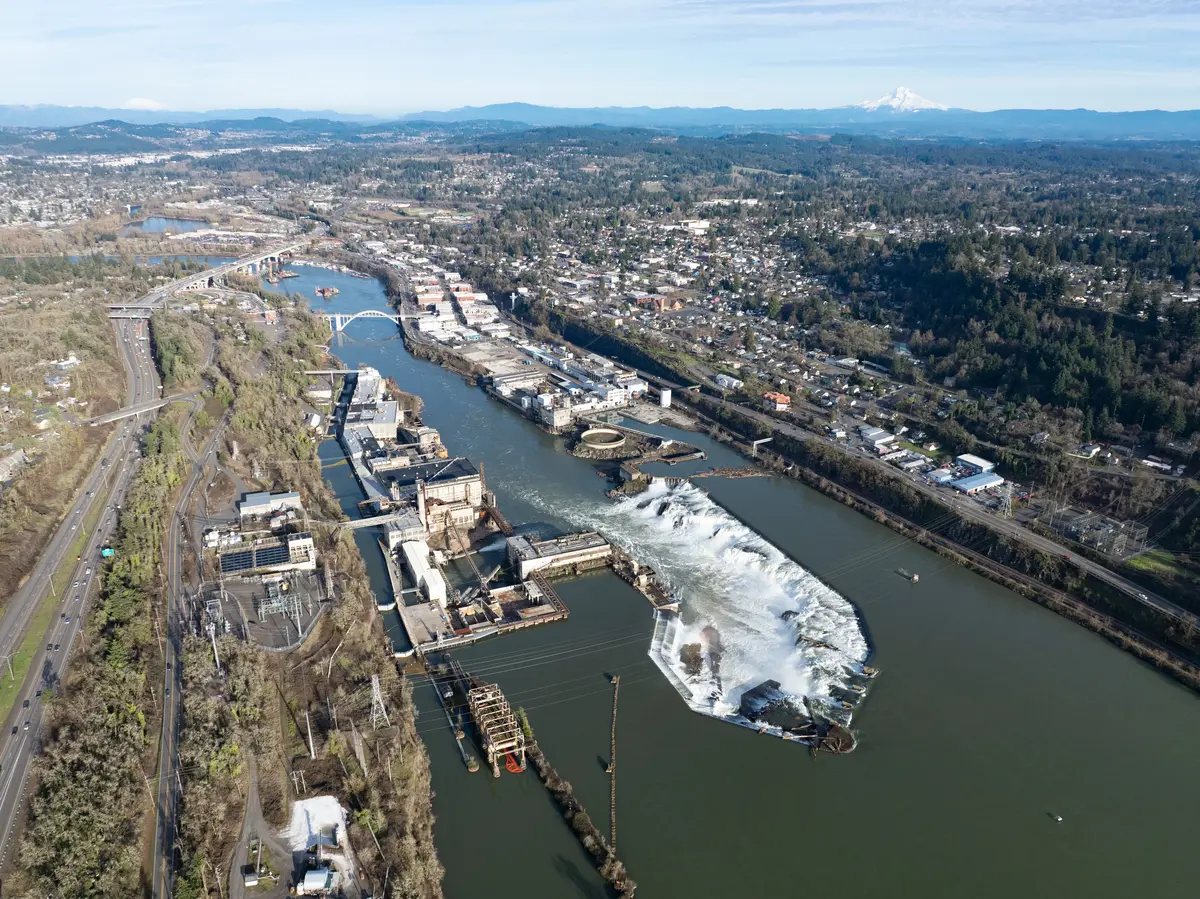
West Linn is a city of 27,601 people spread across 7.6 square miles of Clackamas County, sitting along both the Willamette and Tualatin Rivers about 25 minutes to Portland. The West Linn-Wilsonville School District, which holds an A rating, according to Niche, draws families who put education at the top of their list. The city's major employers are the school district itself, the City of West Linn, and Clackamas County — a public-sector foundation that reflects how thoroughly this is a community people move to for quality of life, not necessarily because work is headquartered here. Remote workers and Portland commuters make up a meaningful share of buyers.
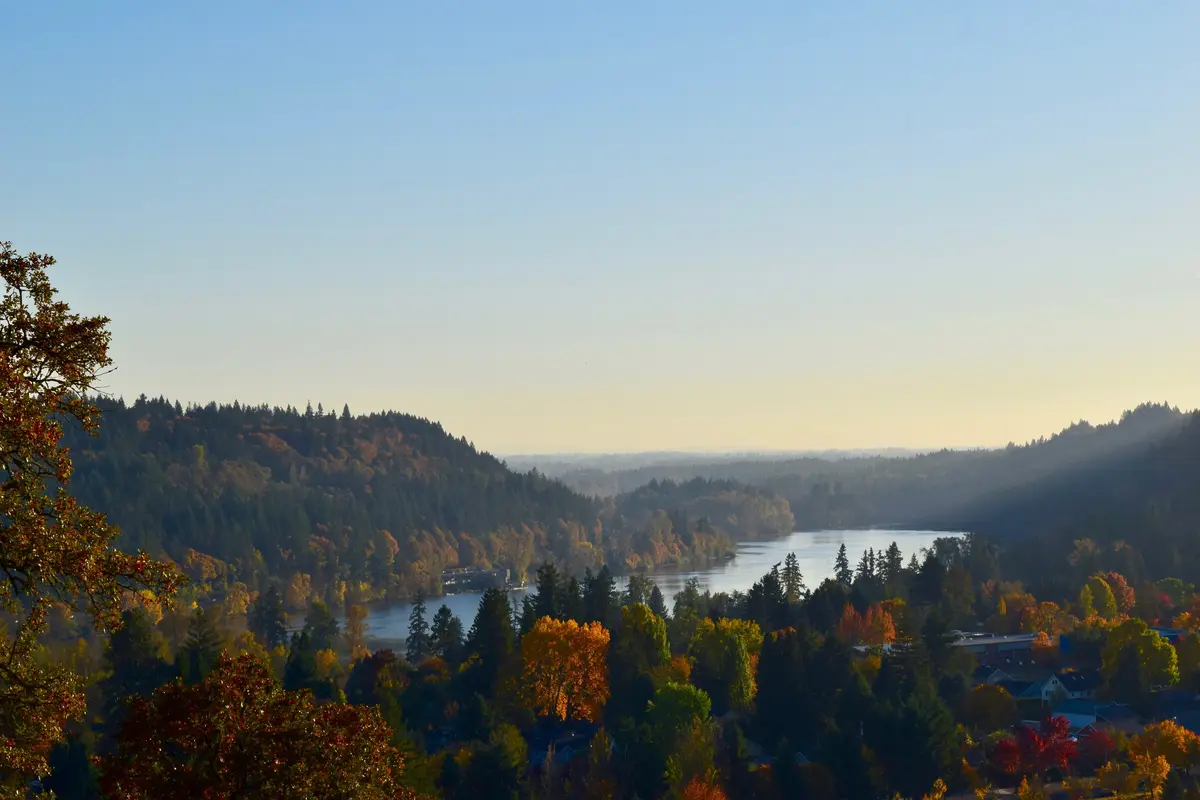
The typical home price in West Linn is $779,602 (Zillow Home Value Index, July 2026), and that figure sits well above what the city's median household income of $146,507 can comfortably carry — a gap that shapes every first-timer's strategy here. Oregon City and Tualatin are noticeably lower, and many first-timers seriously weigh those markets before committing to West Linn. The payoff for staying is tangible: Mary S. Young State Park runs along the Willamette, the Camassia Natural Area protects one of the rarest plant habitats in the Pacific Northwest, and the Historic Willamette district gives the city a genuine sense of place that newer Portland-area suburbs rarely achieve.
Whether you are weeks from making an offer or still building your down payment, the sections below break down what your budget actually buys here, how the buying process works in this specific market, what the cash requirements look like across realistic scenarios, and the mistakes that cost first-timers the most.
The West Linn First-Time Buyer Reality
The honest starting point: the typical home price in West Linn is $779,602 (July 2026), and true entry-level inventory — homes priced below $600,000 — is scarce. When it appears, it tends to be older construction in Bolton or Sunset, and it moves. Buyers who arrive expecting Portland-suburbs pricing comparable to Gresham or Troutdale leave disappointed; West Linn prices closer to what you would find in Lake Oswego, though noticeably below it.
The market is described by local agents and market trackers as somewhat competitive. Homes regularly attract multiple offers, and well-priced homes in West Linn's most desirable pockets still generate real competition. That means your pre-approval letter is not a formality — it is your entry ticket.
The negotiating environment is more buyer-friendly than it was during the peak years of the pandemic surge, but you are walking into a market where the typical purchase price is high enough to require genuine financial preparation. The gap between a median income and the income needed to carry a mortgage at this price point is real enough to demand honest budgeting before you fall in love with a listing. For a deeper look at how West Linn prices sit relative to the metro, see the cost of living breakdown.
The Homebuying Process in West Linn, Step by Step
Step 1: Get Pre-Approved — Before You Tour Anything
In West Linn, this step is not optional and it is not something you can do in parallel with shopping. Listing agents here expect to see pre-approval documentation before scheduling serious showings on competitively priced homes. A pre-qualification letter — the softer, unverified version — will not carry the same weight. Your lender will need full income verification, tax returns, and asset documentation before issuing a genuine pre-approval.
Step 2: Define Your Search by Neighborhood and School Boundary
West Linn's neighborhoods are geographically distinct, and school boundaries within the West Linn-Wilsonville district do not always follow the lines buyers assume. Bolton, Robinwood, and Hidden Springs are different communities with different commute patterns, different price tiers, and different elementary school assignments. Sort this out with your agent before you fall for a home in a boundary you did not intend. The full picture on schools lives on the schools page.
Step 3: Make an Offer — With Appropriate Contingencies
Even in a buyer-friendly market, stripping your offer of every protection to look competitive is a mistake in West Linn. An inspection contingency is not a negotiating handicap — it is your primary defense against discovering that a hillside home's drainage system or an older Bolton-area foundation needs costly attention. The financing contingency protects you if appraisal or loan approval hits a snag. Waiving both is a strategy for cash buyers, not first-timers.
Step 4: Inspection and Appraisal
West Linn's hillside topography means inspectors look hard at drainage, retaining walls, and slope stability — issues you will not encounter in the same way buying in flatter Portland suburbs. Budget the time to understand what your inspector finds, not just whether they flag it. The appraisal matters too: if the purchase price comes in above the appraised value, the gap becomes your problem — either renegotiate, make up the difference in cash, or walk away.
Step 5: Closing
Oregon closes in escrow, not at a traditional closing table, and the final walkthrough, signing, and funding can happen on different days. Expect the process from accepted offer to keys to take 30 to 45 days with a conventional or FHA loan. The step most first-timers underestimate is the final cash-to-close figure, which includes more than just the down payment — covered in the next section.
How Much Home Can You Afford in West Linn
The table below maps out realistic cash requirements at several price points in the West Linn market. Closing costs are estimated at 2–3% of the purchase price — a realistic range for Clackamas County that covers lender fees, title, escrow, and prepaid items. These are estimates, not quotes; your actual figures depend on the specific lender, loan program, and transaction details. The interactive calculator below the table lets you model a monthly payment at your actual numbers.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (2–3%) | Approx. Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5%) — entry-level search | $575,000 | $20,125 (3.5%) | $11,500–$17,250 | ~$32,000–$37,000 |
| Conventional (3%) — entry-level search | $575,000 | $17,250 (3%) | $11,500–$17,250 | ~$29,000–$35,000 |
| FHA (3.5%) — near city median | $680,000 | $23,800 (3.5%) | $13,600–$20,400 | ~$37,000–$44,000 |
| Conventional (3%) — near city median | $680,000 | $20,400 (3%) | $13,600–$20,400 | ~$34,000–$41,000 |
| Conventional (10%) — typical market range | $779,602 | $77,960 (10%) | $15,600–$23,400 | ~$93,000–$101,000 |
| Conventional (20%) — avoids mortgage insurance | $779,602 | $155,920 (20%) | $15,600–$23,400 | ~$171,000–$179,000 |
A few things the table does not show: FHA loans carry an upfront mortgage insurance premium of 1.75% of the loan amount, which is typically rolled into the loan rather than paid at closing, but adds to your total borrowing. Conventional loans with less than 20% down carry private mortgage insurance (PMI) as a monthly cost until you reach sufficient equity. West Linn's effective property tax rate of 0.98% is modest relative to many Oregon suburbs, but on a home near the city median, the annual figure is real — the calculator below gives you a working estimate.
Looking to buy in West Linn? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a West Linn quote.
Common First-Time Buyer Mistakes in West Linn
Shopping Before Pre-Approval
This one costs first-timers in two ways in West Linn. First, you lose homes: agents for competitive listings will not hold a showing for an unverified buyer when pre-approved buyers are already lined up. Second, you fall for homes outside your real range. At prices well above $700,000, the difference between what you qualify for and what you can comfortably afford is not a rounding error — get the pre-approval letter in hand before you tour a single home.
Waiving the Inspection Contingency to Compete
West Linn is not a flat-lot suburban grid. Homes in Rosemont Summit, Skyline Ridge, and the hillside pockets above Robinwood sit on sloped lots where drainage, retaining walls, and foundation conditions vary significantly. A general inspection contingency is not a dealbreaker in this market for a financed buyer — but discovering a failing retaining wall after closing most certainly is. Keep the inspection contingency; negotiate timeline instead if the seller wants speed.
Ignoring the School Boundary Before Making an Offer
The West Linn-Wilsonville School District draws families from across the Portland metro precisely because of its reputation. But boundary lines within the district matter — elementary school assignments vary by street, and some neighborhood pockets feed into different attendance zones than the larger surrounding area would suggest. Confirm the specific assignment for any address before your offer goes in. This matters as much at resale as it does for your own children. The schools page has the full district picture.
Underestimating the Total Cash Required
First-timers consistently budget for the down payment and forget the rest. In West Linn, closing costs alone run $13,000 to $23,000 on a typical transaction. Add prepaid homeowners insurance, the initial escrow reserve for property taxes, and any rate-buydown points your lender recommends, and the cash-to-close figure is often $10,000 to $20,000 higher than buyers expect. Plan your savings target around the full figure — the table in the previous section gives you a realistic range for each scenario.
Local Expert Takeaway: West Linn rewards the first-time buyer who does their homework before they fall in love with a listing. Bolton and Sunset are where the fact sheet puts the city's below-median entry points; the Historic Willamette neighborhood brings walkable streets and a genuine sense of place that newer suburbs in the metro cannot replicate. The hillside homes that make this city beautiful also carry inspection realities that flat-suburb buyers are not used to — slope stability and retaining walls deserve real attention here. Get a pre-approval that reflects your full financial picture, budget for total cash to close rather than just the down payment, and confirm school boundaries before you make an offer. Those three habits separate the buyers who close here from the ones who regroup and try again.
Quick Takeaways & FAQs
✅ West Linn's West Linn-Wilsonville School District holds an A rating from Niche, making it one of the strongest draws for families entering the Portland metro market as first-time buyers.
⚠️ The typical home price of $779,602 (July 2026) is well above what the city's median household income can easily support, so honest pre-purchase budgeting — including full closing costs — is non-negotiable.
📍 Bolton and Sunset sit below the city-wide median price tier, making them the most realistic entry points for first-time buyers in West Linn — but inventory under $600,000 is limited and moves quickly when it appears.
What is the minimum down payment to buy a home in West Linn?
How competitive is the West Linn housing market for first-time buyers?
Which West Linn neighborhoods are most accessible for first-time buyers?
Do I need a real estate agent to buy a home in West Linn?
How long does it take to close on a home in West Linn?
Moving to Oregon?
Tell us what you need help with and we'll connect you with local resources.
