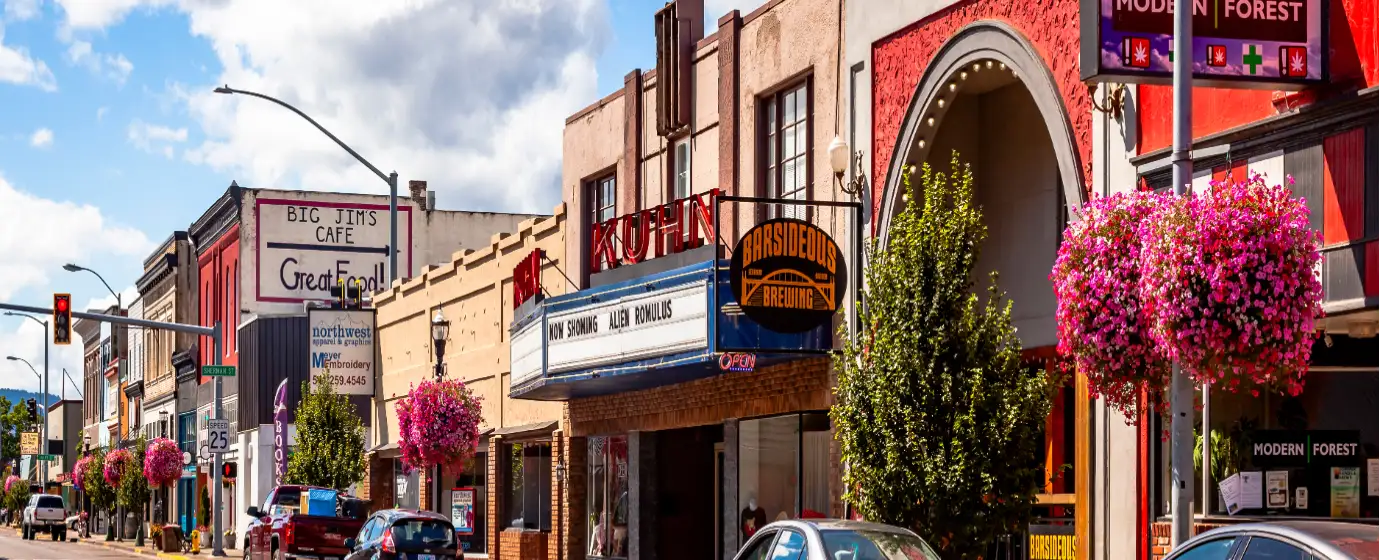
Maybe you've been renting in the Willamette Valley and watching prices in Corvallis or Albany climb out of reach. Lebanon — a city of 19,950 along US-20 in Linn County — is where a lot of first-time buyers land when they do the math and realize they can still afford a house here. The typical home price of $397,559 (Zillow Home Value Index, July 2026) is noticeably lower than in Corvallis and somewhat lower than in Albany, which makes Lebanon one of the more accessible entry points for buyers who work in the broader mid-valley region. But accessible doesn't mean easy, and the gap between what the median household income supports and what a home actually costs here is real — something this guide addresses directly.
Lebanon's economic anchors are institutional: a regional hospital, two colleges, the city government, and the school district make up the bulk of local employment. Many residents also commute — it's about 20 minutes to Albany, OR, where additional job options open up. The community has a genuine small-city feel: the annual Lebanon Strawberry Festival, dating to 1909, still draws the whole town to Cheadle Lake Park each June, and Historic Main Street has the bones of a walkable downtown. For first-time buyers, that community character matters as much as the price tag.
On the cost side, Lebanon sits at a meaningful affordability threshold. The full cost-of-living breakdown puts the numbers in context, but the short version is that Oregon has no sales tax, property taxes here run at an effective rate of approximately 0.87%, and the gap between renting and owning has narrowed enough that buying makes financial sense for buyers who can clear the down payment hurdle. The challenge is cash — not the mortgage payment, but what you need to bring to closing.
Whether you've been thinking about this for a year or just started looking at listings, the sections below walk through what a first-timer's budget actually buys in Lebanon, the step-by-step process under Oregon's escrow system, a concrete budget table, and the most common mistakes buyers make here — so you don't have to learn them the hard way.
The Lebanon First-Time Buyer Reality
The typical home in Lebanon was priced at $397,559 as of July 2026 (Zillow Home Value Index). That figure puts ownership within range for buyers who have saved seriously — but it also exposes the central tension: the median household income here is roughly $43,000 below what you'd need to comfortably carry a purchase at that price. For most first-timers, that means buying at the lower end of the market, not the middle of it.
A genuine entry tier exists. Downtown Lebanon has a mix of Craftsman bungalows and older single-family homes along the historic core — many have been renovated, and the building stock is older with the character that comes with it. South Lebanon, the city's largest residential zone, is a mix of owner-occupied homes built mostly between 1970 and 1999, and it sits right at the city median. If you need something newer, the Cheadle Lake area has seen more recent subdivision development with modern floor plans — but newer construction commands a premium and stretches most first-timer budgets.
One thing that surprises many buyers after six months in Lebanon: the financing gap is the real obstacle, not the competition. Unlike Portland-area markets or even Salem, Lebanon rarely sees the kind of frenzied multi-offer situations that force buyers to waive everything. But lenders still want to see solid credit, documented income, and — most importantly — enough cash to cover both the down payment and closing costs. Buyers who show up pre-approved and cash-ready tend to move smoothly; buyers who underestimate the cash-to-close number are the ones who stall out. See the neighborhood guide for more on how the different areas of Lebanon compare in character and housing stock.
The Homebuying Process in Lebanon, Step by Step
Step 1: Get Pre-Approved Before You Tour
Oregon is an escrow state — closings are handled by title companies and escrow companies, not attorneys, and no lawyer is required at any stage of your transaction. The process is straightforward, but it moves on a timeline that rewards preparation. Get your pre-approval letter in hand before you set foot in a house. Sellers in Lebanon take offers from pre-approved buyers more seriously, and you'll save yourself the frustration of falling in love with a home you can't yet prove you can buy.
Step 2: Choose a Local Lender and Know Your Loan Type
FHA loans are the most common path for first-timers in Lebanon. With a credit score of 580 or above, you can put as little as 3.5% down; buyers with scores between 500 and 579 typically need 10% down. The current FHA loan limit for Linn County is well above Lebanon's typical purchase price, so the limit is not a constraint here for most buyers. Conventional loans with 3% down are also viable for buyers with stronger credit profiles. Your lender will help you compare the total cost of each path, including mortgage insurance, which applies to both programs at low down payments.
Step 3: Shopping and Making an Offer
Oregon's standard purchase contract is the OREF 001 Residential Sale Agreement. Your agent will walk you through it, but the key contingencies to understand before you sign anything are the inspection contingency and the financing contingency. Both protect you — and waiving either one, especially in a market where you're stretching your budget, carries real risk. Well-priced homes in Lebanon do attract interest, so be ready to move when you find the right one, but do not let a sense of urgency push you into skipping protections.
Step 4: Inspection, Appraisal, and the Escrow Period
After an accepted offer, the clock starts on your escrow period — typically 30 to 45 days for a financed purchase in Oregon. Schedule your home inspection promptly; this is the step first-timers most often delay, and delays compress the rest of the timeline. Your lender will order an appraisal to confirm the property value supports the loan. If the appraisal comes in below purchase price, you'll need to negotiate with the seller, cover the gap in cash, or walk away under your financing contingency.
Step 5: Closing
Closing in Oregon happens at a title company or escrow company. You'll review and sign the closing disclosure — which breaks down every fee — at least three business days before your closing date. Bring certified funds or wire your cash to close in advance. Once documents are signed and funds are confirmed, the deed is recorded with Linn County and the home is yours. Recording fees in Linn County generally run between $100 and $300 for the deed and mortgage documents combined.
One step first-timers consistently underestimate: reading the closing disclosure carefully when it arrives. The figures on that form are final, and surprises there — a prepaid insurance reserve, a prorated property tax, prepaid interest — are not negotiable at the table. Review it the day it lands.
How Much Home Can You Afford in Lebanon
Oregon buyer closing costs generally run 2% to 5% of the purchase price, covering loan origination, appraisal, escrow and title fees, homeowners insurance reserves, property tax prepayments, and prepaid interest. The table below shows what different purchase prices cost to get to the finish line — down payment plus estimated closing costs — so you can see the full cash-to-close picture before you start touring.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (2–5%) | Cash Needed at Table |
|---|---|---|---|---|
| FHA 3.5% — entry tier | $280,000 | $9,800 (3.5%) | $5,600–$14,000 | ~$15,400–$23,800 |
| Conventional 3% — entry tier | $280,000 | $8,400 (3%) | $5,600–$14,000 | ~$14,000–$22,400 |
| FHA 3.5% — mid market | $350,000 | $12,250 (3.5%) | $7,000–$17,500 | ~$19,250–$29,750 |
| Conventional 3% — mid market | $350,000 | $10,500 (3%) | $7,000–$17,500 | ~$17,500–$28,000 |
| FHA 3.5% — city typical | $397,559 | $13,915 (3.5%) | $7,951–$19,878 | ~$21,866–$33,793 |
| Conventional 5% — city typical | $397,559 | $19,878 (5%) | $7,951–$19,878 | ~$27,829–$39,756 |
All closing cost figures are estimates; your lender's loan estimate will show your actual numbers within three business days of application. The engine's mortgage calculator below lets you adjust purchase price, down payment, and rate to model your monthly payment at current rates.
One practical note on eligibility: some first-time buyer programs define the term more broadly than you might expect — ask your lender which first-time buyer loan options you qualify for, including whether your ownership history in the last few years affects your eligibility. Completing a HUD-approved homebuyer education course is required for most assistance programs and is genuinely useful regardless; approved online options are widely available if you want to work through the material at your own pace.
Looking to buy in Lebanon? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Lebanon quote.
Common First-Time Buyer Mistakes in Lebanon
Shopping Before Pre-Approval
This is the most common first-timer error in any market, and Lebanon is no exception. Sellers here expect a pre-approval letter with any serious offer. More importantly, you need to know your actual price ceiling before you spend weekends touring homes — it's easy to anchor psychologically to a price point you can't yet prove you can finance, and then struggle to adjust when the lender's numbers come back different.
Underbudgeting Cash to Close
The down payment gets all the attention, but closing costs are what catch buyers off guard in Oregon. Budget for 2% to 5% on top of your down payment, and keep that cash liquid — not in a brokerage account that takes three days to settle, not earmarked for moving expenses. A buyer who has the down payment saved but can't cover the full cash-to-close number will stall out in escrow. Plan for the high end of the closing cost range until your lender gives you a precise estimate.
Waiving the Inspection Contingency
Lebanon's housing stock includes a substantial share of homes built between 1970 and 1999, particularly in South Lebanon and around the Santiam Place area. Older homes can carry deferred maintenance, aging roofs, or outdated electrical panels that don't show up on a walk-through. Waiving your inspection contingency to strengthen an offer is a risk that experienced buyers sometimes take knowingly — first-timers almost never have enough context to make that call safely. Keep the contingency, complete the inspection promptly, and use the results to negotiate or walk away informed.
Ignoring the Commute and School Boundary Reality
Lebanon is not Albany. If your job is in Corvallis, you're looking at a commute via OR-34 on top of the drive to Albany. That's manageable for some households and a real daily grind for others — work out what that means for your mornings before you commit to a specific part of town. On the schools side, the Lebanon Community School District serves the city, holds a C rating according to Niche, and school attendance boundaries do matter for families with kids at different grade levels. A neighborhood that puts your children in a better-fit school can be worth the difference in price; a boundary line can also split siblings into different buildings. Check the specific attendance zone for any address you're seriously considering, and link that research to the schools page for the full district picture.
Local Expert Takeaway: Lebanon's first-time buyer window is real but requires honest preparation on the cash side. The $397,559 typical home price (July 2026) is accessible by Willamette Valley standards, but closing costs in Oregon run 2–5% on top of your down payment — and that total cash-to-close number is what most first-timers underestimate. Get pre-approved before you tour a single home, keep your cash liquid through closing, and hold your inspection contingency on any older property in South Lebanon or Downtown. The buyers who move smoothly here are the ones who show up with their paperwork done and their cash ready, not the ones who made the highest offer.
Quick Takeaways & FAQs
✅ Lebanon's typical home price of $397,559 (July 2026) is noticeably below Corvallis and somewhat below Albany, making it one of the more accessible entry points for first-time buyers in the mid-Willamette Valley.
⚠️ The median household income in Lebanon falls roughly $43,000 short of what's needed to carry the typical home price — most first-timers should budget carefully and plan to buy at the lower end of the market rather than the middle.
📍 Oregon is an escrow state with no attorney required at closing, but buyer closing costs of 2–5% on top of the down payment catch many first-timers off guard — build that full cash-to-close number into your savings target from day one.
What is the typical home price for first-time buyers in Lebanon, Oregon?
What loan options are available for first-time buyers in Lebanon, OR?
How much cash do I actually need to close on a home in Lebanon?
Do I need a real estate attorney to buy a home in Oregon?
Can I qualify as a first-time buyer in Oregon if I've owned a home before?
Moving to Oregon?
Tell us what you need help with and we'll connect you with local resources.
