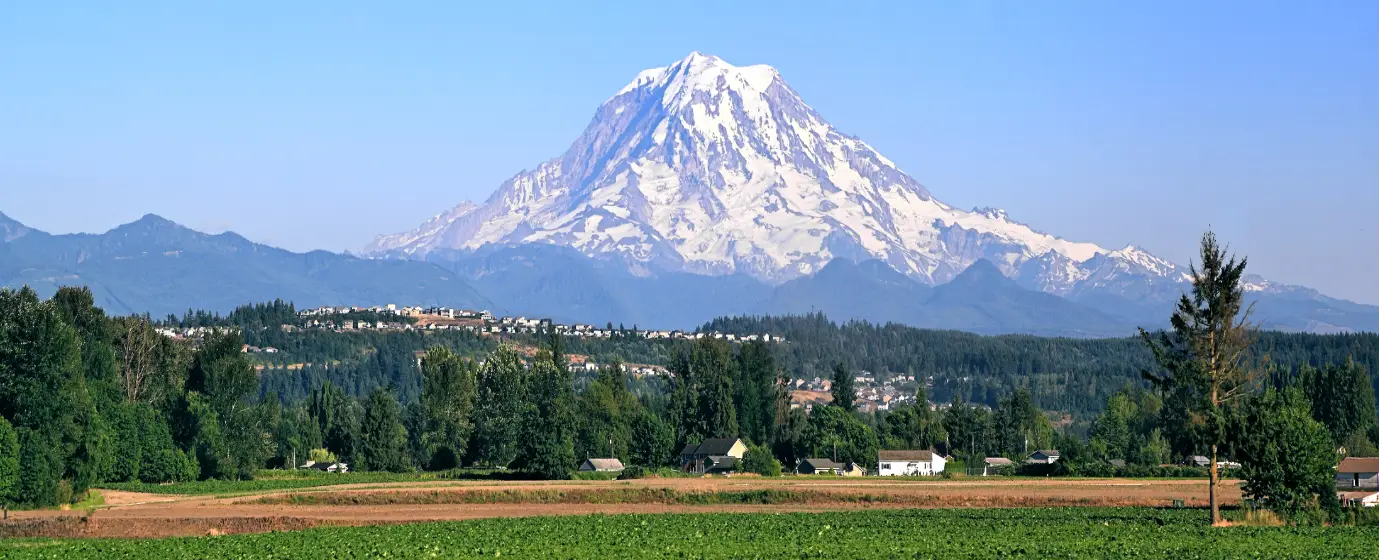
Maybe you've been priced out of Bellevue or Issaquah and someone mentioned Maple Valley. Maybe you've done the math and realized your Renton or Kent budget stretches considerably further out SR-169. Either way, you've landed on a city where the Zillow Home Value Index hit $759,950 in June 2026 — real money for a first-time buyer, but noticeably below what comparable square footage runs on the Eastside. The catch is that Maple Valley's relative affordability is the city's worst-kept secret, which means first-timers compete against move-up buyers who already have equity and know how to write a clean offer.
The economic pull here is real. Amazon operates a logistics and delivery station locally, Fred Meyer anchors the Four Corners commercial district, and a significant share of residents commute northwest on SR-169 for work. The median household income here sits at $152,885, which tells you something about who's already buying in this zip code and what you're competing against. For more on how income and taxes stack up across the full cost picture, see the cost-of-living page.
The housing stock itself skews newer than what you'd find in Kent or Renton proper — most of Maple Valley developed in master-planned subdivisions from the 1990s onward, so you're more likely to encounter a home with updated systems and an open floor plan than a 1960s ranch that needs rewiring. That's a meaningful advantage for first-timers who can't absorb a surprise repair bill in year one. Day-to-day life centers on the Four Corners area for errands, Lake Wilderness Park for weekends, and a pair of independent cafés — Village Coffee on Witte Rd SE and Creative Coffee Brewing on Maple Valley Black Diamond Rd SE — for the kind of slow Saturday mornings that make a longer Seattle commute feel worth it.
Whether you're still deciding or already scheduling showings, the sections below break down what your budget actually buys here, how the Maple Valley buying process works step by step, what to put in your budget spreadsheet, and the specific mistakes that most often derail first-time buyers in this market.
The Maple Valley First-Time Buyer Reality
The Zillow Home Value Index for Maple Valley sat at $759,950 in June 2026 — and that figure deserves honest context before you build a budget around it. That's a city-wide composite. Entry-level inventory — older townhomes and smaller single-family homes on the edges of established subdivisions — can open closer to the high $500s or low $600s. But those homes sell fast and draw multiple offers. See the cost-of-living page for the full price context.
The competitive reality is harder to sugarcoat: as of May 2026, Maple Valley had approximately 81 active listings and about 2.3 months of supply — that's a seller's market. Homes were selling in roughly 13 days with a sale-to-list ratio of approximately 98.5%, meaning sellers were getting close to full asking price. Two competing offers per listing is the average, which means a clean first-time offer is the exception, not the rule.
What this means practically: the buyer who wins in Maple Valley has already done their financial homework. They know their ceiling, they have a lender letter in hand, and they're not asking the seller to wait while they schedule a second showing. First-timers who approach this market the way they'd approach buying a used car — browsing casually, asking questions along the way — tend to lose two or three offers before they adjust their process. That adjustment period costs time, and in a market moving at 13 days, time is the one thing you don't have.
The Homebuying Process in Maple Valley, Step by Step
Step 1: Get Pre-Approved — Not Just Pre-Qualified
Pre-qualification is a lender's estimate based on what you tell them about your finances. Pre-approval is a conditional commitment based on verified documents — pay stubs, tax returns, bank statements, a hard credit pull. In Maple Valley, as throughout Washington's competitive markets, sellers expect to see a pre-approval letter before they take your offer seriously.
This is the step first-timers most often get wrong. They spend two weekends touring homes on Maple Valley Black Diamond Rd SE or in the Wilderness Village area, fall in love with something, and then discover during the offer process that their pre-approval takes three business days to obtain. By then, the home is under contract. Get pre-approved before your first showing, full stop.
Step 2: Define Your Search Area and Address-Level Details Early
In Maple Valley, the difference of a few blocks can affect which services and amenities are within easy reach, what a home's future resale pool looks like, and how much land or lot size you're getting for a given price point. Confirm the specific address details — not just the general area — for anything that factors into your decision before you make an offer.
Step 3: Shopping and Making an Offer
With 13-day average days on market, you'll need to be ready to write an offer within 24–48 hours of seeing a home you want. Your offer should include your pre-approval letter and, where possible, an escalation clause if you're competing in a multi-offer situation. Lean on your agent's knowledge of recent comparable sales in specific subdivisions like Elk Run or Maple Ridge Highlands — sellers in those areas know what their neighbors got and will expect you to as well.
Step 4: Inspection and Appraisal
Waiving inspection entirely is the move that most often haunts first-time buyers in fast markets. A shorter inspection period — say, five business days instead of ten — is a reasonable concession in a competitive offer. Eliminating inspection entirely on a home you've never owned before is a different calculation altogether. Maple Valley's 1990s-and-later housing stock is generally in better shape than older inventory, but "newer" is not the same as "no issues."
The appraisal is ordered by your lender, not you. If the home appraises below the contract price and you've waived the appraisal contingency, you're on the hook to cover the gap in cash. Know before you waive whether you have that cash available.
Step 5: Closing
Washington is an escrow state — a neutral escrow company handles the closing, and you typically won't sit across a table from the seller. Closing typically takes 30–45 days from accepted offer. Budget time off work for the final walkthrough (usually 24 hours before closing) and the signing appointment itself, which can run 60–90 minutes.
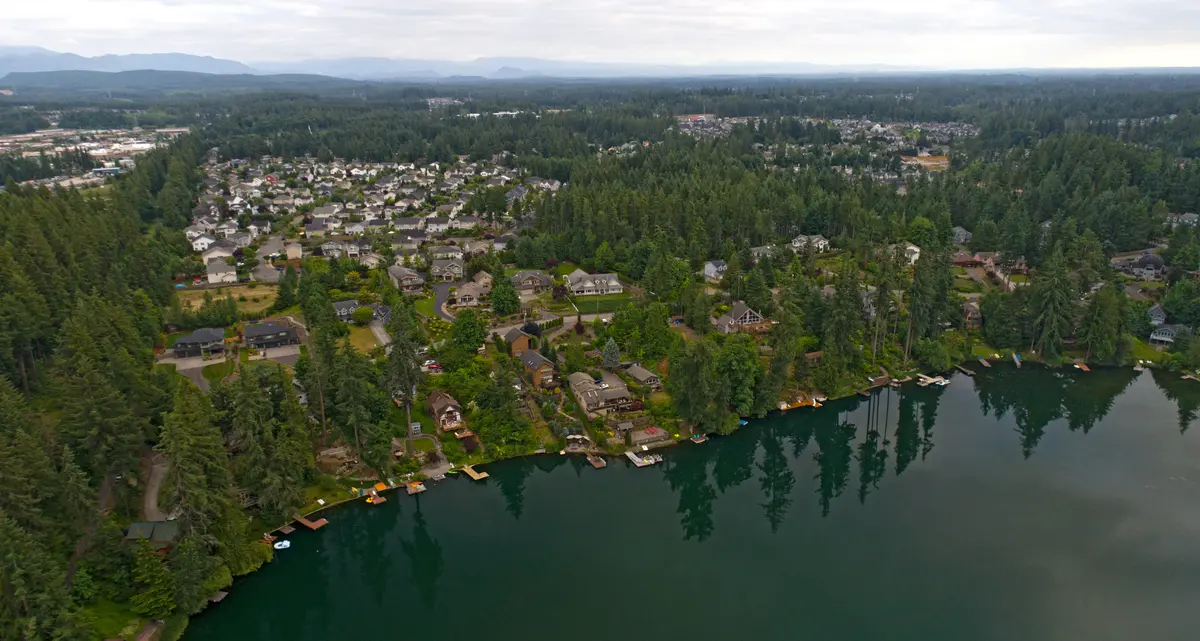
How Much Home Can You Afford in Maple Valley
The table below uses approximate estimates based on current Maple Valley price bands. Closing costs are estimated at 2–3% of the purchase price, which is a typical range in King County — your actual figure will depend on your lender, title company, and any negotiated seller concessions. These are estimates for planning purposes only; your lender will provide a Loan Estimate with exact figures once you're in the process.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs | Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5% down) — entry-level home | $580,000 | ~$20,300 (3.5%) | ~$11,600–$17,400 | ~$32,000–$38,000 |
| Conventional (3% down) — entry-level home | $580,000 | ~$17,400 (3%) | ~$11,600–$17,400 | ~$29,000–$35,000 |
| Conventional (5% down) — mid-range home | $680,000 | ~$34,000 (5%) | ~$13,600–$20,400 | ~$48,000–$54,000 |
| Conventional (10% down) — near-median home | $760,000 | ~$76,000 (10%) | ~$15,200–$22,800 | ~$91,000–$99,000 |
| Conventional (10% down) — larger/newer home | $850,000 | ~$85,000 (10%) | ~$17,000–$25,500 | ~$102,000–$110,500 |
| Conventional (20% down) — near-median, no PMI | $760,000 | ~$152,000 (20%) | ~$15,200–$22,800 | ~$167,000–$175,000 |
Conventional loan programs — including options with as little as 3–10% down — are the most common financing tool in this market, with FHA a strong alternative for buyers with thinner down payments or credit scores still building toward the 700 range.
One budget line first-timers consistently underestimate: prepaid items. Beyond closing costs, you'll owe prepaid homeowner's insurance, prepaid interest for the days between closing and your first payment, and initial escrow reserves. These can add several thousand dollars on top of closing costs — confirm the full "cash to close" number, not just the down payment, well before you write your first offer. The 30-year fixed rate averaged 6.65% for the week of August 20, 2026 (Freddie Mac), so it's worth asking your lender about rate lock timing.
Looking to buy in Maple Valley? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Maple Valley quote.
Common First-Time Buyer Mistakes in Maple Valley
Shopping Before Pre-Approval
Touring homes in Wilderness Village or around Lake Sawyer before you have a pre-approval letter isn't harmless reconnaissance — it's a setup for frustration. You'll form emotional attachments to homes you can't offer on competitively, and you'll waste your agent's time on showings that can't go anywhere. In a market where homes average 13 days before going under contract, the buyers who win are the ones who can act the same day they fall in love with something.
Waiving Inspection Without Understanding What You're Waiving
In hot offer situations, some first-timers waive inspection entirely because a competing buyer did. The smarter approach in Maple Valley: offer a shortened inspection period (five to seven business days) rather than no inspection at all. Most of the subdivision homes here were built post-1990, which helps, but deferred maintenance, drainage issues in lower-lying lots, and aging HVAC systems still show up regularly. An inspection isn't just about negotiating credits — it's how you decide whether to proceed at all.
Treating Your Down Payment as Your Full Cash Need
The down payment is the number that gets all the attention. First-time buyers consistently undercount what comes alongside it: closing costs (typically 2–3% of the purchase price in King County), prepaid homeowner's insurance, prepaid interest, and initial escrow reserves. On a $700,000 purchase with 5% down, the down payment is $35,000 — but total cash to close can run $55,000–$65,000 once everything is included. Ask your lender for a full Loan Estimate before you make your first offer so there are no surprises at the closing table.
Underestimating How Fast Maple Valley Moves
Buyers who tour on Saturday and plan to think it over until Wednesday regularly find the home under contract by Monday morning. At 13 days average on market and a sale-to-list ratio near 98.5%, this is not a market that rewards deliberation. If you need a week to feel comfortable with a decision of this size, that's worth knowing about yourself before you start — it may mean adjusting your process rather than your target city. The buyers who succeed here typically have their financial picture locked down so completely that the only remaining question is whether they like the house.
Local Expert Takeaway: Maple Valley rewards the buyer who does the work before they start touring. Get a full pre-approval letter — not a pre-qualification estimate — from a lender familiar with King County before you set foot in a home in Elk Run or Maple Ridge Highlands. The market moves in under two weeks on average, and the sellers near Four Corners who are fielding two or three offers aren't waiting for you to catch up on paperwork. Do the financial groundwork first, know your true cash-to-close number including prepaids and escrow, and if a shortened inspection period is on the table, negotiate the timeline rather than waiving protection entirely.
Quick Takeaways & FAQs
✅ Maple Valley's housing stock skews newer than most of the Seattle metro — post-1990 master-planned subdivisions dominate, which generally means fewer surprise repair bills for first-time buyers.
⚠️ Entry-level homes in Maple Valley sell in roughly 13 days on average, and waiting even a weekend to decide typically means losing — have your pre-approval and your ceiling locked in before your first showing.
📍 Sellers in Maple Valley expect a full pre-approval letter — not a pre-qualification — before they take an offer seriously; skipping this step is the single fastest way to lose a home you want.
What credit score do I need to buy a home in Maple Valley?
How competitive is the Maple Valley housing market for first-time buyers?
Is FHA or conventional financing better for buying in Maple Valley?
How long does it take to close on a house in Maple Valley?
Can I negotiate closing costs with the seller in Maple Valley?
Moving to Washington?
Tell us what you need help with and we'll connect you with local resources.
