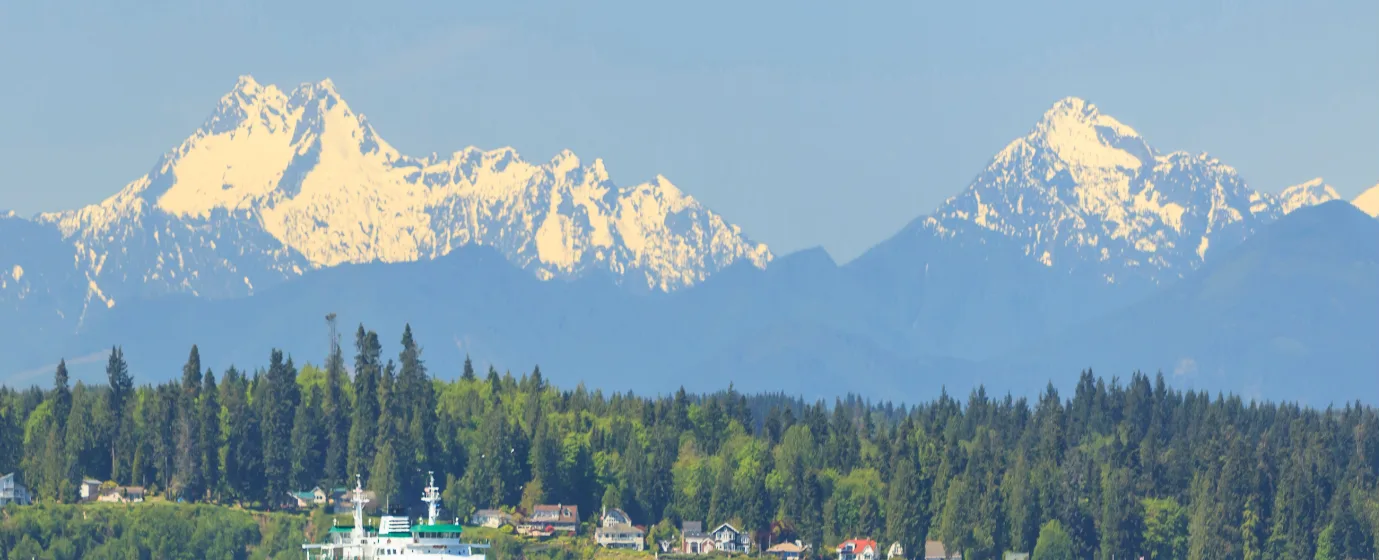
You've probably done the math on Seattle and it didn't work. So someone pointed you north toward Edmonds — ferry town, waterfront, genuinely walkable downtown on Main Street — and now you're wondering if the numbers here are any more forgiving. The short answer: not dramatically, but the market in 2026 has opened up slightly, and understanding exactly what you're working with is the difference between making a confident offer and spending a year in near-misses. Edmonds sits in Snohomish County, roughly 15 miles north of Seattle, at the junction of SR-104 and the Edmonds-Kingston Ferry Terminal. That location is the whole story: close enough to the city to commute, far enough to feel like somewhere else entirely.
A meaningful share of buyers arrive here from Seattle and Shoreline — parents with school-age children who want a strong district reputation without paying the full Eastside premium. The downtown business corridor — independent cafés, restaurants along Main Street — gives the Edmonds Bowl a livability that new construction suburbs can't manufacture. Regional transit connections make the commute genuinely multimodal for some buyers, and the Port of Edmonds anchors the waterfront character that defines the city's identity.
On the cost side, the Zillow Home Value Index puts the typical Edmonds home at $855,381 as of mid-2026 — a figure that's noticeably below what you'd pay in Kirkland or Bellevue but still demands serious financial preparation from a first-time buyer. Washington's lack of a state income tax helps your long-term purchasing power, though 2026 brought a property tax increase tied to the South County Fire annexation that every buyer budgeting here needs to know about. See the full cost-of-living breakdown for Edmonds for tax and utility context. Inventory has risen year-over-year through spring 2026, and homes are averaging around 28 days on market — still active, but with more breathing room than buyers faced in 2024 and 2025.
Whether you're a renter in Seattle trying to buy your first home or relocating from out of state with limited knowledge of the Pacific Northwest market, the sections below break down what the Edmonds market actually costs at first-time-buyer price points, how the buying process works here step by step, what your cash needs look like at the table, and the specific mistakes that trip up first-timers in this particular market.
The Edmonds First-Time Buyer Reality
The typical Edmonds home price — $855,381 per the Zillow Home Value Index, mid-2026 — lands well above what most people picture when they say "starter home." For a first-time buyer financing at current rates, that number represents a real stretch, and being honest about that upfront saves months of frustration.
Entry-level in Edmonds doesn't mean small-town affordable. The bottom of the market tends to be older condominiums and townhomes rather than detached single-family homes. A detached single-family home in the Edmonds Bowl or near the waterfront can push well past the typical figure. Move-in-ready homes at any price point carry a premium because buyers at mid-6% rates are already payment-sensitive and unwilling to take on a renovation project on top of a large mortgage.
The competitive pressure that surprises first-timers most: approximately 32% of recent Edmonds home sales were all-cash transactions, up from around 24% just two years prior. You are not just competing with other financed buyers — you are competing with equity-rich sellers from Seattle and Bellevue who are trading down into Edmonds with cash in hand. That dynamic rewards preparation: a clean pre-approval, a realistic price ceiling, and an agent who knows when to push and when to wait. Edmonds is also geographically locked in — Puget Sound to the west, established cities on every other side — which means new supply is structurally limited and prices have a structural floor that other suburban markets don't.
The Homebuying Process in Edmonds, Step by Step
Step 1: Get Pre-Approved Before You Tour Anything
In Edmonds, touring without a pre-approval letter is not just premature — it's actively counterproductive. Homes averaged 28 days on market in May 2026, which sounds comfortable until a well-priced property in Meadowdale or North Edmonds draws multiple offers in its first weekend. Sellers here, many of whom have equity-rich options, will not entertain an offer from an unverified buyer.
Get your pre-approval from a lender who can underwrite quickly and communicate with listing agents directly. A letter from a local or regional lender often carries more credibility with Edmonds-area sellers than a letter from a national online lender, even if the rate is similar.
Step 2: Define Your Price Ceiling — and Stick to It
Pre-approval tells you the maximum a lender will give you. Your actual ceiling should be lower. Factor in the approximately 0.70% effective property tax rate, the 2026 South County Fire annexation increase (roughly $780 per year added to the median Edmonds property tax bill), homeowners insurance, and HOA dues if you're buying a condo or townhome. The interactive calculator below this section will help you model those monthly numbers.
Step 3: Shop With Realistic Parameters
Work with your agent to identify which neighborhoods fall within your budget. Condos and townhomes represent genuine first-time-buyer entry points in Edmonds. The Edmonds Bowl commands a premium for the walkability to the ferry terminal, Main Street restaurants, and the Edmonds Fishing Pier — you'll pay for that proximity.
Step 4: Write a Competitive Offer
In a market where inventory has loosened slightly, you have modestly more negotiating room than buyers had in 2023–2024 — but this is not a buyer's market. Pricing your offer based on what you want to pay, rather than what comparable sales support, is still a fast path to rejection. Your agent should pull recent Northwest MLS sold data, not just active listings.
One concession worth asking for in 2026: sellers of move-in-ready homes are occasionally offering rate buydowns as an incentive for payment-sensitive buyers. If a seller is motivated, a buydown can meaningfully reduce your first years of payments — ask your lender to model it before you finalize offer terms.
Step 5: Inspection, Appraisal, and Closing
Washington is an attorney-state-adjacent escrow state — closings are handled by an escrow/title company, not an attorney. Your inspection period is typically 5–10 days and is one of the most important contingencies you have. Do not skip it to be competitive unless you have the construction expertise and cash reserves to absorb a major repair bill. The appraisal follows shortly after mutual acceptance; if the home appraises below your offer price, you'll need to negotiate with the seller, cover the gap in cash, or exercise your appraisal contingency. Budget 45–60 days from mutual acceptance to closing keys-in-hand for a financed purchase in Snohomish County.
How Much Home Can You Afford in Edmonds
The table below illustrates what different purchase prices require in cash at closing, using approximate figures for down payment and estimated closing costs. Closing costs in Washington typically run 2%–3% of the purchase price for a buyer (covering loan origination, title, escrow, prepaid taxes, and insurance escrow). These are estimates — your lender's Loan Estimate will show your actual figures.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs | Cash Needed at Table |
|---|---|---|---|---|
| FHA 3.5% Entry condo/townhome | $575,000 | ~$20,125 (3.5%) | ~$13,000–$17,000 | ~$33,000–$37,000 |
| Conventional 3% Entry condo/townhome | $575,000 | ~$17,250 (3%) | ~$13,000–$17,000 | ~$30,000–$34,000 |
| FHA 3.5% Smaller SFH, outer areas | $700,000 | ~$24,500 (3.5%) | ~$16,000–$21,000 | ~$40,500–$45,500 |
| Conventional 5% Smaller SFH | $700,000 | ~$35,000 (5%) | ~$16,000–$21,000 | ~$51,000–$56,000 |
| Conventional 10% Near city median | $855,000 | ~$85,500 (10%) | ~$19,000–$26,000 | ~$104,500–$111,500 |
| Conventional 20% Near city median | $855,000 | ~$171,000 (20%) | ~$19,000–$26,000 | ~$190,000–$197,000 |
A 20% down payment eliminates private mortgage insurance, which reduces your monthly cost meaningfully — but at Edmonds price points, most first-time buyers are financing with less than 20% down and budgeting for PMI until they reach sufficient equity.
One line item that catches buyers off guard: Washington state's Real Estate Excise Tax (REET) is a seller cost, but it factors into how sellers price and negotiate. Understanding it helps you read seller motivation correctly. Also note that the approximately 0.70% effective property tax rate — among the lower rates in Snohomish County — is worth confirming for any specific property you're considering, since individual assessments vary. For a deeper look at how Edmonds taxes and overall costs compare, see the Edmonds cost-of-living page.
Looking to buy in Edmonds? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Edmonds quote.
Common First-Time Buyer Mistakes in Edmonds
Touring Before You Have a Pre-Approval Letter
This is the single most common mistake, and in Edmonds it's especially costly. You fall in love with a craftsman near the Edmonds Bowl, learn it received three offers in 48 hours, and you weren't even in a position to make one. Pre-approval is not a formality — it's your entry ticket to the market. Start the lender process 60–90 days before you want to be under contract.
Waiving the Inspection Contingency Without Understanding What You're Giving Up
During the peak seller's market years of 2021–2022, waiving inspections became normalized locally. In 2026, with inventory up and homes sitting slightly longer, you have less reason to waive — and more to lose if you do. Edmonds has a significant stock of mid-century homes that look pristine and hide deferred maintenance: older electrical panels, wood rot beneath well-painted trim, drainage issues on sloped lots. A $600 inspection fee is the cheapest insurance you'll buy in this transaction.
Underbudgeting the Cash You'll Need at the Table
First-time buyers consistently plan for the down payment and forget that closing costs — title, escrow, loan origination, prepaid insurance, and the initial property tax escrow — add another 2%–3% of the purchase price. On an $855,000 home, that's $17,000–$25,000 on top of your down payment. The South County Fire annexation also means property tax escrow calculations for 2026 purchases are slightly higher than they were a year ago. Your Loan Estimate, which your lender must provide within three business days of application, is the document to study line by line.
Ignoring the Difference Between a Pre-Qualification and a Pre-Approval
A pre-qualification is a conversation. A pre-approval means a lender has reviewed your income documentation, tax returns, bank statements, and credit — and is committing to lend you a specific amount. Listing agents in Edmonds know the difference, and some will push sellers to decline offers accompanied only by a pre-qualification letter. When rates sit near 6.93% (the Washington state average as of July 2026), lenders are scrutinizing debt-to-income ratios carefully; surface-level pre-qualifications that haven't stress-tested your full financial picture can fall apart during underwriting. Get the real thing before you make an offer.
Local Expert Takeaway: Edmonds in 2026 is more accessible than it was in 2023 — inventory is up, days on market have stretched slightly, and sellers of move-in-ready homes are occasionally offering rate buydowns. But 'more accessible' is relative: you're still entering a market where nearly a third of buyers pay cash, entry-level options start with condos and townhomes well below the city median, and a typical detached home pushes past $855,000. The buyers who succeed here get their pre-approval locked before they ever walk through a door on 5th Avenue North, set a hard cash ceiling that includes closing costs and the 2026 property tax increase, and resist the temptation to waive the inspection on a mid-century home with great curb appeal. The Edmonds Bowl is earned — it rewards patience and preparation.
Quick Takeaways & FAQs
✅ Edmonds' effective property tax rate of approximately 0.70% is below both the Snohomish County and Washington state medians — a genuine financial advantage for buyers at this price point.
⚠️ Roughly 32% of recent Edmonds home sales were all-cash transactions, meaning first-time buyers with financing are consistently competing against equity-rich buyers — making a clean, fully documented pre-approval non-negotiable.
📍 The 2026 South County Fire annexation added approximately $780 per year to the median Edmonds property tax bill — a real number to plug into your budget before you set your offer ceiling.
What credit score do I need to buy a home in Edmonds?
How long does it take to close on a home in Edmonds?
Is FHA financing competitive in the Edmonds market?
What are closing costs for a buyer in Washington state?
Are there first-time buyer loan programs available in Edmonds or Washington state?
Moving to Washington?
Tell us what you need help with and we'll connect you with local resources.
