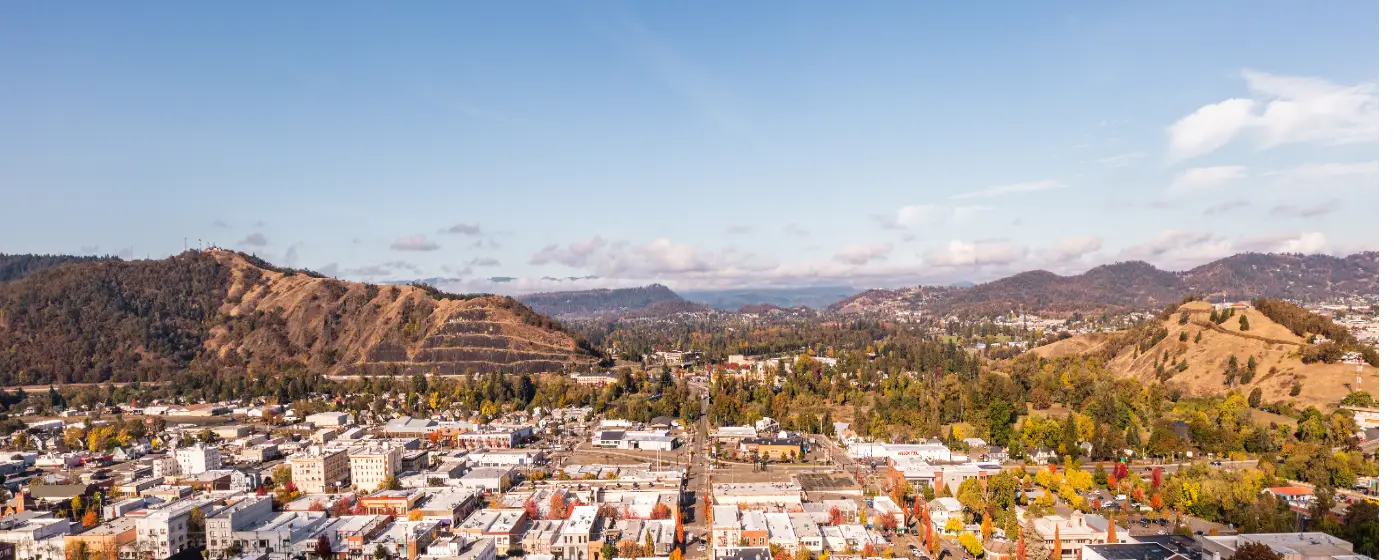
Roseburg doesn't get the headlines that Bend or Portland do, and for first-time buyers that is precisely the point. The Zillow Home Value Index puts the typical home price at $368,343 as of July 2026 — a figure that still makes genuine homeownership possible for households that would be completely priced out of most Oregon metros. That said, the median household income here sits noticeably below what it takes to comfortably carry that purchase, which means budgeting honestly from the first conversation with a lender matters more here than in markets where wages and prices align more closely. This guide is built around that tension.
Roseburg is the seat of Douglas County, a city of 23,795 people anchored by I-5 roughly midway between Eugene and Medford. Mercy Medical Center, Douglas County government, Roseburg Public Schools, Umpqua Community College, and the City of Roseburg itself form the core employment base — a mix of healthcare, education, and public-sector jobs that produces stable but not high salaries. Many residents also commute about 70 minutes to Eugene for work or drive to surrounding communities. The school district holds a B- rating, according to Niche, with 5,365 students enrolled in 2025-26. Understanding where you want to be relative to the district's school boundaries is a detail first-time buyers here often leave too late.
The housing stock that puts Roseburg within reach for first-timers is largely ranch-style homes built between 1960 and 1985 — solid bones, but not turnkey. Move-in-ready homes in neighborhoods like Garden Valley and Hucrest attract competitive attention and can go under contract quickly. For those who qualify, much of Roseburg and the broader Umpqua Valley falls within USDA-eligible territory, meaning a zero-down purchase may be possible — though eligibility is confirmed address by address on the USDA property eligibility map, so it must be verified for any specific property you consider.
Whether you are buying for the first time or returning to homeownership after three or more years of renting — HUD counts both as first-time buyers — the sections below walk through what your budget actually buys here, the step-by-step process in this specific market, a concrete budget snapshot table, and the mistakes that consistently cost Roseburg buyers time and money.
The Roseburg First-Time Buyer Reality
The typical home price in Roseburg sits at $368,343 as of July 2026 (Zillow Home Value Index). That number is noticeably more accessible than what buyers face in Eugene, Portland, or Bend — but it still demands a real plan, because the median household income in Roseburg falls short of what most lenders want to see for that purchase by a meaningful gap. If your income is at or near the city median, your comfortable price target and your maximum approval number are probably two different figures, and knowing which one to shop to matters enormously.
Entry-level inventory in Roseburg tends to cluster in the older ranch homes spread across Hucrest and parts of West Harvard, and in the Downtown Roseburg Mill-Pine Historic District, where condition and timing drive wide variation in what's available. Both carry trade-offs. The ranch homes offer more square footage and established lots but require scrutiny — electrical panels, aging roofs, and crawl-space conditions are the recurring items on inspection reports for homes built between 1960 and 1985. The historic district delivers walkability to Stewart Park and the South Umpqua River waterfront but less predictable renovation costs in older structures.
Garden Valley and Hucrest are where the competition concentrates. Move-in-ready homes there attract consistent buyer interest, and well-priced listings rarely sit. If you are shopping in those neighborhoods, arriving with a pre-approval letter and a clear sense of your ceiling is not optional — it is the baseline expectation sellers have. Nearby cities like Sutherlin, Winston, and Myrtle Creek offer lower typical prices if the Roseburg entry point stretches your budget, though each involves a longer drive to Roseburg's employers and services. See the full neighborhood breakdown for character and context on each area.
The Homebuying Process in Roseburg, Step by Step
Step 1: Get Fully Pre-Approved — Before You Tour Anything
Pre-qualification and pre-approval are not the same thing, and sellers in Roseburg know the difference. A pre-approval means a lender has reviewed your income documentation, employment history, and debt load and issued a letter committing to a specific dollar amount. It typically takes one to two business days. Sellers here will generally not take an offer seriously without one — showing up to a tour first and sorting out financing later is the single most common way first-time buyers here lose a home they wanted.
Shop at least three to four lenders and try to get all your credit pulls done within a 14-day window — credit bureaus treat multiple mortgage inquiries inside that window as a single inquiry, so your score takes one hit instead of several. Your pre-approval letter is typically valid for 60 to 90 days, so time the process to when you are genuinely ready to make offers, not six months out.
Step 2: Define Your Comfortable Payment, Not Your Maximum
Your lender's maximum approval number is a ceiling, not a target. Your actual monthly outlay includes principal, interest, property taxes at Roseburg's effective rate of approximately 0.65%, homeowner's insurance, and any HOA dues — a stack that can look meaningfully different from what a quick online search suggests. Use the mortgage calculator on this page to model a full payment at different price points before you commit to a shopping range. Staying well below your maximum gives you negotiating room and financial breathing room once you own.
Step 3: Tour, Offer, Negotiate
Work with a buyer's agent who knows Douglas County specifically. In Roseburg's entry-level range, a well-priced home can move quickly, and your agent's job is to flag the listings that match your criteria before they are gone. When you make an offer, include an inspection contingency and a financing contingency — both matter, and both protect you. Sellers may push back on either, especially on move-in-ready homes where multiple buyers are interested.
Step 4: Inspection and Appraisal
Never waive the inspection on an older Roseburg ranch home. Deferred maintenance on homes built between 1960 and 1985 — the most common stock in the entry-level range — can run $15,000 to $40,000, covering items like electrical panels, roofing, and crawl-space repairs. The inspection report is also your negotiating document: it gives you the basis to ask for a price reduction or seller-paid repairs if the findings are significant.
Your lender will order the appraisal. If it comes in below your purchase price, you have three options: renegotiate the price with the seller, cover the gap in cash, or walk away if your contract includes an appraisal contingency. Know which path you are prepared to take before you are in that situation.
Step 5: Closing
Oregon buyer closing costs typically run 2% to 5% of the purchase price, covering lender fees, title and escrow, recording charges, prepaid insurance, and prorated property taxes. On a $368,000 purchase, that is roughly $7,360 to $18,400 in addition to your down payment. Plan for the higher end of that range — arriving at closing short of cash is avoidable with a realistic budget built from the start. Oregon also offers a state tax tool worth knowing: a First Time Home Buyer Savings Account (Form OR-HOME) lets you deduct up to $6,125 per year in deposits or earnings from Oregon taxable income, with higher limits for married couples filing jointly. It is not a loan or a grant — it is a state income tax deduction on the money you are already setting aside for your purchase.
How Much Home Can You Afford in Roseburg
The table below shows five buying scenarios at realistic Roseburg price points. Closing costs are estimated at 3% of purchase price — the approximate midpoint of Oregon's 2%–5% range. Use these as planning benchmarks, not guarantees; your actual figures depend on lender, loan type, credit score, and the specific property. The interactive calculator below this section lets you model your own numbers precisely.
| Scenario | Purchase Price | Loan Type | Down Payment | Est. Closing Costs (3%) | Est. Cash Needed at Table |
|---|---|---|---|---|---|
| USDA eligible address (0% down) | $300,000 | USDA (0% down) | $0 | ~$9,000 | ~$9,000 |
| FHA — lower entry point | $300,000 | FHA (3.5%) | $10,500 | ~$9,000 | ~$19,500 |
| Conventional — lower entry point | $300,000 | Conventional (3%) | $9,000 | ~$9,000 | ~$18,000 |
| FHA — at city typical price | $368,000 | FHA (3.5%) | $12,880 | ~$11,040 | ~$23,920 |
| Conventional — at city typical price | $368,000 | Conventional (3%) | $11,040 | ~$11,040 | ~$22,080 |
| Conventional — Garden Valley / Hucrest range | $420,000 | Conventional (5%) | $21,000 | ~$12,600 | ~$33,600 |
A few notes on these loan types. USDA Section 502 Guaranteed Loans require no down payment for qualified buyers in eligible areas — Roseburg generally qualifies, but eligibility is confirmed address by address on the USDA property eligibility map, not by zip code or neighborhood. Income limits for a 1–4 person household are $119,850 in most Oregon counties (FY 2025 table). FHA loans require 3.5% down for borrowers with credit scores of 580 or above. Conventional loans can start at 3% down with strong credit, though private mortgage insurance applies below 20% equity. VA loans, available to eligible veterans, can also require zero down payment.
None of the scenarios above include monthly costs — property taxes, insurance, or any HOA dues. Those are what the calculator below is built to show you, at current rates, for any price point you choose.
Looking to buy in Roseburg? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Roseburg quote.
Common First-Time Buyer Mistakes in Roseburg
Touring Homes Before Getting Pre-Approved
It feels backwards, but the right order here is pre-approval first, then tours. Roseburg's entry-level market moves, and a home you fall in love with during a weekend tour can be under contract before your lender has seen your W-2s. A full pre-approval — not a pre-qualification estimate — takes one to two business days and costs nothing. Do it before you schedule a single showing.
Waiving the Inspection on an Older Ranch Home
The homes that fit a first-time buyer's budget in Roseburg are often ranch-style builds from the 1960s through the 1980s. They can be solid, well-located purchases — but waiving inspection to compete is a risk that can easily cost $15,000 to $40,000 in surprises. Electrical panels, roofing, and crawl-space conditions are the recurring issues in this vintage of home. The inspection is also how you negotiate: a report documenting deferred maintenance gives you grounds to ask for a price reduction or seller credit. Skipping it means accepting every unknown.
Treating the Lender's Maximum as a Budget
Lenders approve you for the most they are willing to lend, not the most you should spend. Your real monthly cost includes principal, interest, property taxes, insurance, and any HOA dues — and in a city where median household income sits below the income needed to carry the typical home, the gap between your maximum approval and a payment that actually fits your life can be significant. Build your shopping range around a comfortable payment, then use the calculator on this page to confirm it before you start touring.
Ignoring School Boundaries Until It's Too Late
Roseburg Public Schools serve the city, but attendance boundaries matter — especially for families with school-age children who have strong preferences about which elementary school their kids attend. A home a few streets away from the one you want can put your children in a different school entirely. Check the district boundary map before you fall in love with a specific street, not after you are already in contract. The Roseburg schools page covers the district in detail. Separately, if your job or daily routine takes you north toward Eugene, a home on the west side of I-5 versus a location that requires crossing through downtown can shape your commute experience more than the mileage suggests — worth a test drive at rush hour before you commit to a neighborhood.
Local Expert Takeaway: Roseburg is one of the few Oregon cities where a first-time buyer with a solid credit score and a few months of focused saving can realistically get to the closing table — but the math only works if you plan honestly. The city's typical home price of $368,343 (July 2026) is accessible compared to Eugene or Medford, yet it still exceeds what the city's median household income comfortably supports, which means your pre-approval number and your actual budget need to be two separate conversations. Get pre-approved before you tour anything, build your shopping range around a comfortable monthly payment rather than your lender's ceiling, and do not skip the inspection on an older ranch home — the crawl-space and electrical surprises in that housing stock are real. If your target neighborhood is Garden Valley or Hucrest, move quickly when the right listing appears; move-in-ready homes there attract serious competition. If your budget needs more flexibility, the Mill-Pine Historic District and the neighboring towns of Sutherlin and Winston offer lower entry points worth a look.
Quick Takeaways & FAQs
✅ Roseburg's typical home price of $368,343 (July 2026) is noticeably more accessible than Eugene or Medford, making it one of the more realistic paths to first-time homeownership in Oregon.
⚠️ The city's median household income falls short of what's needed to comfortably carry the typical home purchase, so honest budgeting before you start touring is essential — not optional.
📍 Much of Roseburg falls within USDA-eligible territory, potentially allowing a zero-down purchase, but eligibility is confirmed address by address on the USDA property map — never assume by neighborhood.
What credit score do I need to buy a home in Roseburg?
Is Roseburg USDA loan eligible?
How much are closing costs for a buyer in Oregon?
What does HUD mean by 'first-time homebuyer' — do I qualify if I owned a home years ago?
What is the Oregon First Time Home Buyer Savings Account and is it worth using?
Moving to Oregon?
Tell us what you need help with and we'll connect you with local resources.
