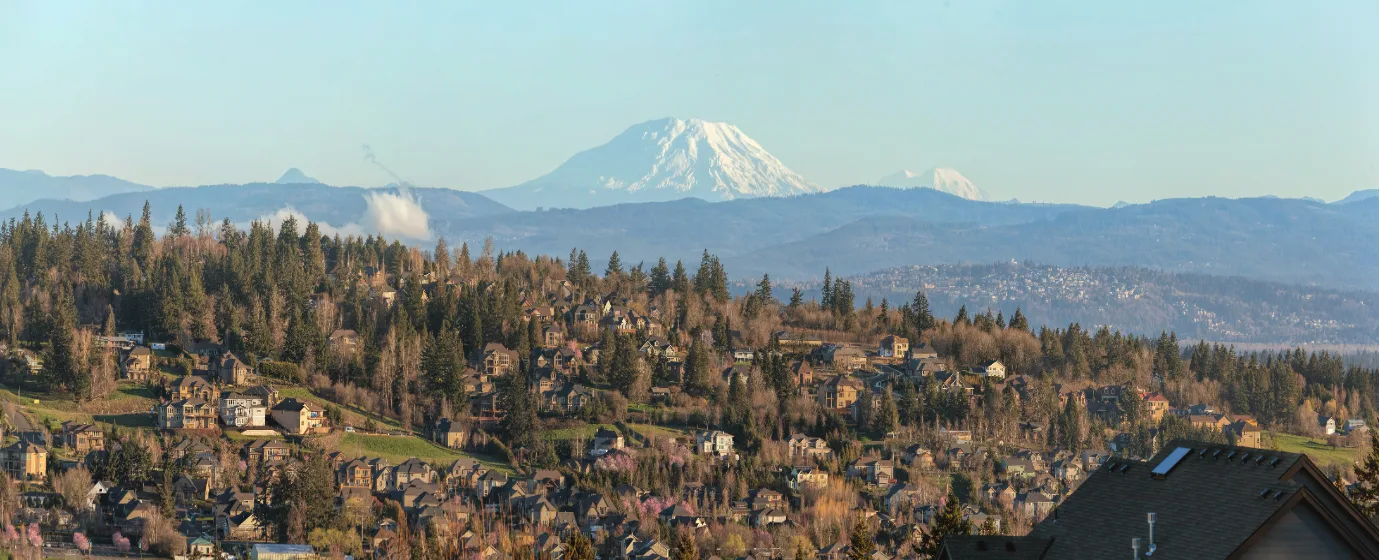
Maybe a colleague mentioned Happy Valley after you were priced out of Portland proper. Maybe you ran the numbers and decided Milwaukie or Clackamas wasn't quite the right fit. Either way, you've landed on a city that surprises a lot of first-timers: Happy Valley looks suburban from the outside — planned subdivisions, newer construction, wide streets — but it carries a price tag closer to an established urban neighborhood than the outlying bedroom community you might expect. Understanding that gap before you start touring is what separates buyers who close from buyers who spend six months getting outmaneuvered.
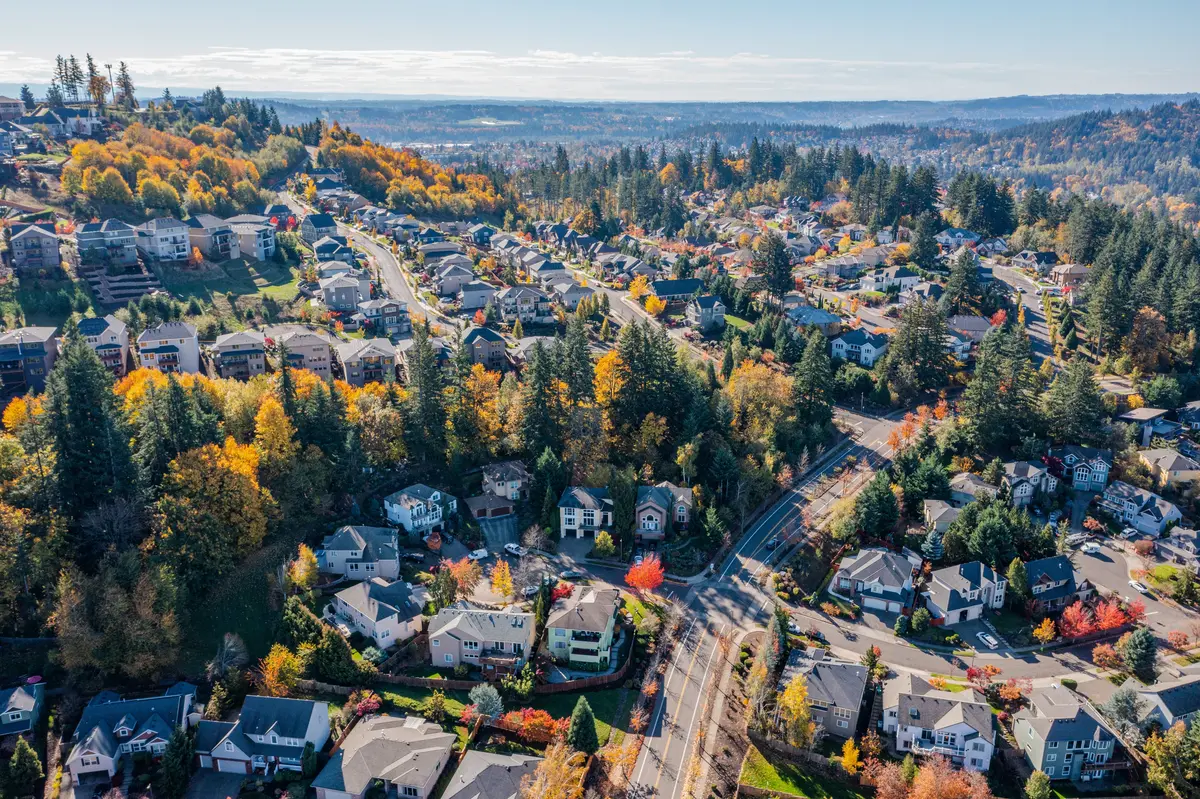
The city of 26,738 was designed from the ground up around residential growth. Commercial activity runs along the OR-212 and Sunnyside Road corridor, while the residential side is almost entirely planned subdivisions — master-planned neighborhoods with dedicated parks, trails, and architectural guidelines baked in. The North Clackamas School District draws many of the families relocating here, and that consistent demand is one reason entry-level inventory moves quickly when it appears. For a deeper look at schools, see the Happy Valley schools page.
The median household income in Happy Valley sits at $122,151 — well above the Oregon average — yet the typical home price still outpaces what that income alone can comfortably carry. That affordability gap is the central reality for first-time buyers here. Compared with buying in Portland itself, prices in Happy Valley run in a similar range; Milwaukie and Clackamas both come in somewhat lower if stretching your budget is the priority. For a full cost-of-living breakdown, the cost of living page has the detailed comparison. The daily lifestyle offset — Metro-managed nature parks, about 25 minutes to Downtown Portland, and newer housing stock — is what keeps buyers from simply defaulting to a cheaper neighboring city.
Whether you're just starting to research or already saving for a down payment, the sections below walk through what your budget actually buys here, the step-by-step process specific to this market, an honest budget snapshot, and the mistakes that cost first-time buyers the most in Happy Valley.
The Happy Valley First-Time Buyer Reality
The typical home price in Happy Valley is $686,520 (Zillow Home Value Index, July 2026). That figure is not a ceiling — it is the midpoint. Meaningful entry points exist below it, but they require trade-offs: older construction, smaller square footage, or lots without the trail access and park proximity that define the neighborhoods most buyers are targeting.
What makes this market particularly challenging for first-timers is the composition of the housing stock. Because Happy Valley developed largely through master-planned subdivisions, there is relatively little of the fixer-upper inventory that gives buyers in older suburbs a foothold. Homes that need cosmetic work and are priced to reflect it do come up — but they are the exception, not a reliable entry strategy.
The affordability math is honest but not impossible. A household earning the city's median income of $122,151 faces a gap between what that income qualifies for at current rates and what the typical home costs here. That gap is real and worth acknowledging before you fall in love with a specific neighborhood. First-timers who succeed in Happy Valley tend to do two things: they get fully underwritten pre-approval before they start touring, and they stay flexible on neighborhoods — recognizing that Rock Creek, Pleasant Valley, Sunnyside, and Eagle Landing each have a distinct character and housing mix worth understanding on its own terms. For neighborhood-level character and trade-offs, the best neighborhoods page breaks down each area in detail.
The Homebuying Process in Happy Valley, Step by Step
Step 1: Get Pre-Approved — Before You Tour Anything
In Happy Valley, most sellers will not accept a showing request without a pre-approval letter in hand. This is not a formality — it is a hard gate. Pre-approval requires a hard credit pull, pay stubs, W-2s, and bank statements; it is meaningfully different from a pre-qualification, which is little more than a self-reported estimate. The strongest position is a fully underwritten pre-approval, where the lender has already verified your documents. That step speeds up closing significantly once you are under contract.
First-timers most often underestimate how long this step takes. Give yourself two to three weeks to gather documents, shop at least two or three lenders, and get the letter in final form. Starting this process the week you want to tour a home is the most common mistake in this market.
Step 2: Define Your Search — Neighborhood and School Zone
School assignment in Happy Valley varies by address, not just by neighborhood name. Two homes on adjacent streets can fall into different elementary attendance zones within the North Clackamas School District. If schools are driving your decision — and for many families moving here, they are — confirm the exact school zone for every address before you get emotionally attached. Your agent can pull boundary maps; the district's website has the official lookup tool.
Step 3: Make Offers With Contingencies That Protect You
Oregon is a contingency-friendly state, and you should use that. A standard offer in Happy Valley includes a financing contingency, an inspection contingency, and an appraisal contingency. Well-priced homes in this market attract multiple offers, which creates pressure on first-timers to waive protections they should not waive — particularly the inspection. A home inspection on a Happy Valley subdivision home, even a newer one, matters: HOA-managed exteriors can mask deferred maintenance on systems that are entirely your responsibility inside the unit.
Step 4: Inspection, Appraisal, and the Final Stretch
Once you are under contract, you will typically have 10 business days for inspections. Order a general inspection and consider a sewer scope — Happy Valley's newer construction is generally sound, but lateral sewer lines on a hillside lot can develop issues that a general inspector will not catch. The appraisal follows and is ordered by your lender. If the home appraises below the purchase price, you will need to negotiate, cover the gap in cash, or walk away — your appraisal contingency protects your earnest money if you choose the last option.
Step 5: Closing
Oregon uses title companies and escrow agents rather than attorneys for closings. Plan on signing roughly three to five days before the funding date in some cases, though same-day sign-and-close is also common. Your closing disclosure will arrive at least three business days before closing — read it carefully against your loan estimate and flag any line-item changes with your lender immediately, not the morning of closing.
How Much Home Can You Afford in Happy Valley
The table below maps out what different purchase prices and down payment scenarios require in cash at closing. Closing costs in Oregon typically run between 2% and 3% of the purchase price and cover lender fees, title insurance, prepaid property taxes and homeowners insurance, and escrow charges. These are estimates — use them to frame your savings target, then run your specific numbers through the calculator below.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs | Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5% down) — entry-level | ~$525,000 | ~$18,375 (3.5%) | ~$10,500–$15,750 | ~$29,000–$34,000 |
| FHA (3.5% down) — near city median | ~$625,000 | ~$21,875 (3.5%) | ~$12,500–$18,750 | ~$34,000–$41,000 |
| Conventional (3% down) — entry-level | ~$525,000 | ~$15,750 (3%) | ~$10,500–$15,750 | ~$26,000–$32,000 |
| Conventional (5% down) — near city median | ~$650,000 | ~$32,500 (5%) | ~$13,000–$19,500 | ~$45,500–$52,000 |
| Conventional (10% down) — city median | ~$686,520 | ~$68,652 (10%) | ~$13,730–$20,596 | ~$82,000–$89,000 |
| Conventional (20% down) — city median | ~$686,520 | ~$137,304 (20%) | ~$13,730–$20,596 | ~$151,000–$158,000 |
The 20%-down scenario eliminates private mortgage insurance (PMI) entirely, which meaningfully reduces your monthly payment — use the calculator to see how much. FHA loans carry a mortgage insurance premium that persists for the life of the loan if your down payment is below 10%, so the lower upfront cash requirement comes with a long-term monthly cost worth modeling carefully.
Happy Valley's effective property tax rate is approximately 1.13%, which the calculator factors in automatically. One note on Oregon specifically: the state has no sales tax, which does not directly affect your closing costs but does affect how much disposable income you have month to month — a real factor when you are stretching to reach a $686,520 price point.
Looking to buy in Happy Valley? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Happy Valley quote.
Common First-Time Buyer Mistakes in Happy Valley
Touring Before You Have Pre-Approval
Happy Valley's planned subdivisions look beautiful on a weekend drive, and it is tempting to schedule tours before your financing is in order. Do not. Sellers here expect a pre-approval letter with any offer, and in a market where well-priced homes attract multiple buyers, a pre-qualified buyer without a full lender commitment will lose to a pre-approved one every time. Worse, you risk falling in love with a home at a price your actual approval letter won't support.
Waiving the Inspection to Win a Bidding War
The pressure to waive contingencies is real in this market, particularly on homes priced below the city median where competition concentrates. The inspection contingency is the one to protect. Even newer Happy Valley homes — many built in the 2000s and 2010s — can have drainage issues on hillside lots, HVAC systems approaching end of life, or HOA-governed exterior features that obscure what you are actually responsible for maintaining. An inspection is not optional; it is how you price the risk you are accepting.
Assuming School Zones Without Checking
The North Clackamas School District covers a large geographic area, and school assignment in Happy Valley is address-specific. A home in one part of Sunnyside may feed into a different elementary school than a home two streets over. If the specific school matters to your family — and for many buyers relocating to Happy Valley, it does — pull the district boundary map before you write an offer, not after. For the full picture on the district and individual schools, see the schools page.
Underbudgeting the Cash You Need at Closing
First-timers consistently underestimate total cash-to-close. The down payment is only part of it. Oregon closing costs, prepaid homeowners insurance, the first year's property tax escrow deposit, and any HOA initiation fees can add significantly on top of your down payment — sometimes more than you expect. Budget for the full figure from the start, and do not drain your emergency fund to reach it. Going into a home purchase with zero reserves because you stretched every dollar to close is a fragile position the moment a furnace fails or a roof needs attention.
Local Expert Takeaway: Happy Valley rewards first-time buyers who do the financial groundwork before they fall in love with a floor plan. The city's typical home price of $686,520 (July 2026) sits above what the median household income alone will comfortably carry, which means your pre-approval letter — ideally a fully underwritten one — is not a formality, it is your credibility in this market. Neighborhoods like Rock Creek, Pleasant Valley, Sunnyside, and Eagle Landing each have a distinct character and housing mix worth understanding before you narrow your search, and that flexibility is often what gets a first-timer across the finish line. Get the letter, know your school zone, and budget your full cash-to-close figure — not just the down payment.
Quick Takeaways & FAQs
✅ Happy Valley sits about 25 minutes to Downtown Portland with access to Metro-managed parks like Scouters Mountain and Mount Talbert, making the commute-to-nature trade-off one of the strongest in the Portland suburbs.
⚠️ The typical home price of $686,520 (July 2026) outpaces what the city's median household income can comfortably carry, so first-time buyers need a detailed pre-approval — not just a rough estimate — before they start shopping.
📍 School assignment in Happy Valley is address-specific within the North Clackamas School District, so confirming the exact boundary for any home you are considering is a non-negotiable step before writing an offer.
What is the minimum down payment to buy a home in Happy Valley?
How competitive is the Happy Valley real estate market for first-time buyers?
Do I need to verify which school my child would attend before making an offer?
What closing costs should I expect when buying in Happy Valley?
Is it worth buying in Happy Valley versus a less expensive nearby city like Milwaukie or Clackamas?
Moving to Oregon?
Tell us what you need help with and we'll connect you with local resources.
