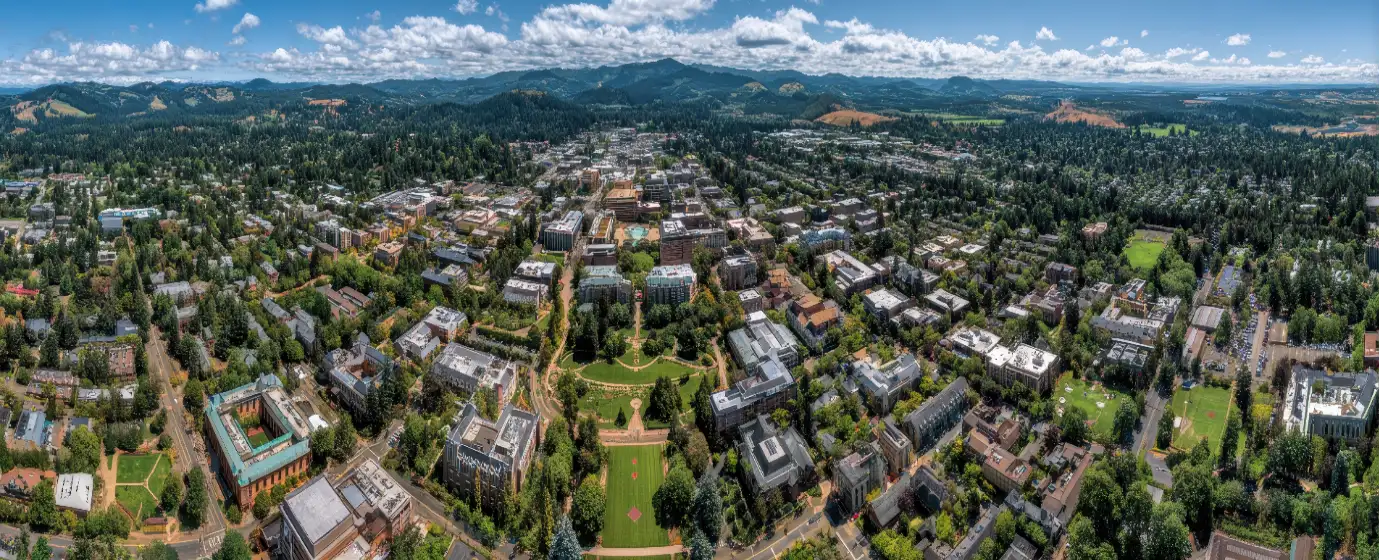
Maybe your company is relocating you here. Maybe you've been watching Albany prices and someone told you Corvallis wasn't that much more. Maybe you toured campus, fell for the bike infrastructure and the Willamette riverfront, and started running numbers on your phone before you left the parking lot. Whatever brought you here, the first thing to understand is that Corvallis operates on a different economic logic than most Oregon cities its size: Oregon State University sets the tone, Good Samaritan Regional Medical Center and HP anchor the professional job base, and a population of 61,247 living in under 15 square miles creates a housing market with very little room to expand outward.
That compression matters for first-time buyers. The typical home price in Corvallis stands at $565,289 as of July 2026 — well above what the city's median household income can comfortably carry at current rates. The gap between median income and the income needed to buy the typical home here is substantial, by roughly $79,000. That doesn't mean buying is impossible for a first-timer, but it does mean your down payment strategy, your loan type, and your neighborhood flexibility will all matter more here than they would in Albany or Lebanon, where prices run noticeably lower.
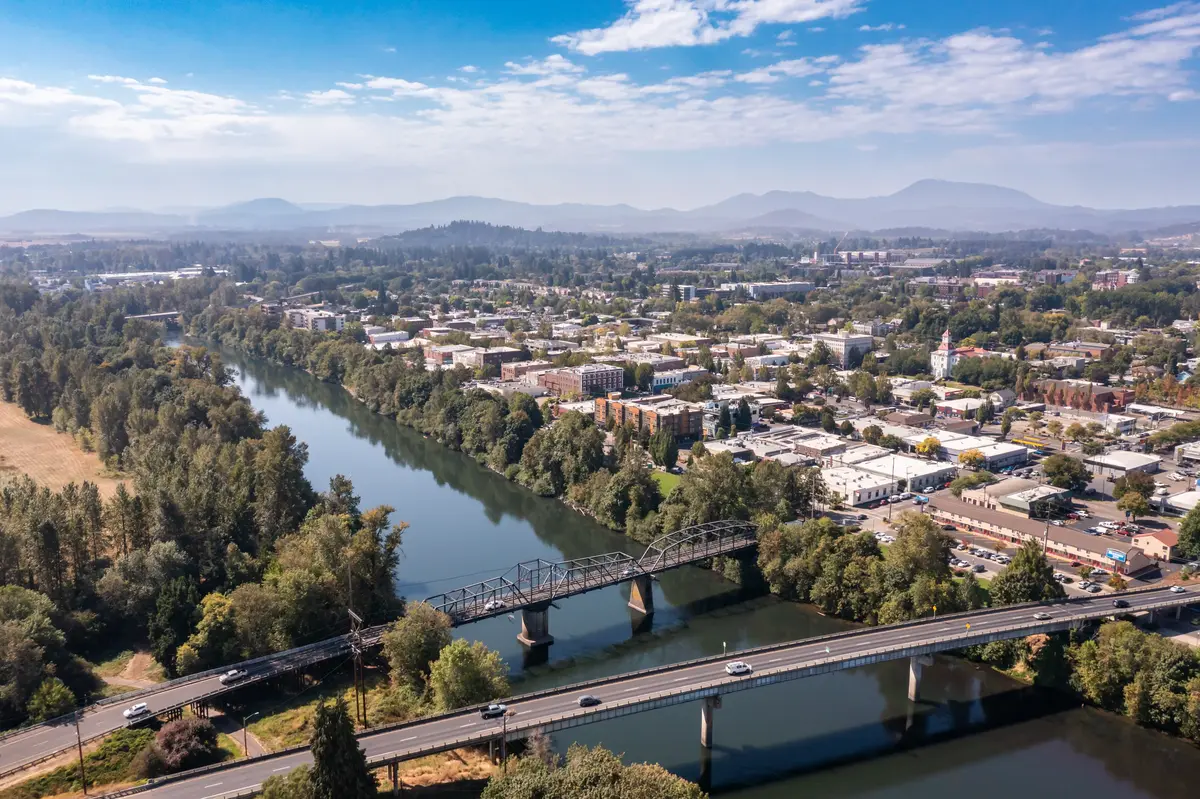
What Corvallis offers in return is a city that genuinely functions without a car for many residents. With bike lanes on 97% of collector and arterial streets and 18 miles of shared-use paths, the Corvallis Transit System running about 13 bus lines, and a compact grid that puts most errands within a 15-minute ride, transportation costs can meaningfully offset housing costs for buyers who factor that in. The Corvallis Farmers' Market, Bald Hill Natural Area, Avery Park, and the Oregon State University campus are all part of a daily life that doesn't require driving to find quality.
Whether you're seriously running numbers or just starting to think through the move, the sections below break down what your budget actually buys in Corvallis, how the local buying process works step by step, a plain-language budget snapshot table, and the mistakes that trip up first-timers in this specific market.
The Corvallis First-Time Buyer Reality
The typical home price in Corvallis is $565,289 (Zillow Home Value Index, July 2026). For a first-timer putting 3% to 5% down, that means you're financing more than half a million dollars — and in a market shaped by a major research university, a regional medical center, and limited land, sellers know that demand is consistent. Well-priced homes here move quickly; budget accordingly and get your paperwork in order before you fall in love with a listing.
Entry-level options do exist, but they tend to cluster in specific areas and housing types. Older condominiums and smaller single-family homes in South Corvallis and Willamette Landing represent the most realistic foothold for buyers at the lower end of the local price spectrum. Northwest Corvallis and Timberhill skew larger and newer. College Hill runs above the city median, driven partly by proximity to the OSU campus and the rental demand that surrounds it — something to weigh if you're buying there as an owner-occupant and not expecting a student-adjacent street.
The honest picture for a first-timer: plan on needing meaningful cash reserves beyond your down payment, a solid credit profile, and a pre-approval letter in hand before you set foot in a single showing. Sellers in Corvallis will not wait for you to get organized after finding the house you want. For neighborhood-by-neighborhood context on what different parts of the city feel like, see the best neighborhoods guide.
The Homebuying Process in Corvallis, Step by Step
Step 1: Get Pre-Approved — Before You Tour Anything
In Corvallis, a pre-qualification letter is largely meaningless to a serious seller. What you need is a full pre-approval: verified income, tax returns, bank statements, employment history, and a hard credit pull, reviewed by an underwriter. Most sellers here will not consider an offer without one attached. Pre-approval letters are typically valid for 30 to 90 days, so time the process about 60 days before you plan to make offers.
Step 2: Work With a Local Buyer's Agent
A buyer's agent in Corvallis costs you nothing out of pocket — seller compensation covers it — but a local agent earns their value in ways that matter here: knowing which streets near campus have high rental turnover, which South Corvallis lots carry drainage issues in a wet winter, and which sellers are genuinely motivated versus testing the market. Interview at least two before you commit.
Step 3: Search With Your Pre-Approval Range, Not Your Maximum
Leave yourself room. Closing costs, moving costs, and the first round of owner maintenance tasks routinely catch first-timers flat. Search at or slightly below your pre-approved ceiling so that a competitive offer or a repair credit request doesn't break the budget you've built.
Step 4: Make an Offer — and Understand What You're Signing
Oregon uses standard OREF (Oregon Real Estate Forms) purchase agreements. Your offer will include price, earnest money (typically 1% to 2% of purchase price in this market), financing contingency, inspection contingency, and a closing date. The earnest money is at risk if you back out without a valid contingency, so read every contingency deadline carefully before you waive or modify anything.
Step 5: Inspection Period — Go Beyond the General Inspection
Oregon practice calls for a standard structural, roof, and plumbing inspection — but in Corvallis and the broader Willamette Valley, also budget for a radon test and a sewer scope. Radon levels in this part of the valley are elevated enough that skipping the test is a gamble, and a sewer lateral failure on an older property is an expensive surprise that costs far less to discover before closing than after.
Step 6: Appraisal and Underwriting
Once your offer is accepted and inspection contingencies are resolved, your lender orders an appraisal. If the home appraises below purchase price, you'll need to negotiate a price reduction, cover the gap in cash, or walk away. Keep your financing contingency intact until you have a clear-to-close.
Step 7: Close Through a Title Company
Oregon closes real estate transactions through escrow at a title company — not through an attorney, as some other states require. The title company manages document preparation, coordinates fund transfers, and records the deed. Oregon property taxes are paid in arrears, which means they get prorated between buyer and seller at closing based on your closing date — and that proration affects how much cash you'll need at the table. One more Oregon-specific nuance: under Measure 50, a property's assessed value can sit well below its current market value for a long-term owner. When you buy, the assessed value typically resets closer to market value, which can mean a higher annual tax bill than the seller's tax history suggests. The city's effective rate is 0.95%, but apply that to your purchase price — not to what the prior owner was paying — for an honest estimate.
How Much Home Can You Afford in Corvallis
The table below lays out estimated cash requirements for several realistic purchase scenarios in Corvallis, using Oregon's typical closing cost range of 2% to 5% of purchase price. These are illustrative estimates — not quotes. Your actual figures will vary based on loan type, lender, closing date, and negotiated seller credits. The interactive calculator below the table lets you run your own numbers at current rates.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (2–5%) | Est. Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5% down) — entry range | ~$420,000 | ~$14,700 (3.5%) | ~$8,400–$21,000 | ~$23,100–$35,700 |
| Conventional (3% down) — entry range | ~$420,000 | ~$12,600 (3%) | ~$8,400–$21,000 | ~$21,000–$33,600 |
| FHA (3.5% down) — near city median | ~$565,000 | ~$19,775 (3.5%) | ~$11,300–$28,250 | ~$31,075–$48,025 |
| Conventional (5% down) — near city median | ~$565,000 | ~$28,250 (5%) | ~$11,300–$28,250 | ~$39,550–$56,500 |
| Conventional (10% down) — near city median | ~$565,000 | ~$56,500 (10%) | ~$11,300–$28,250 | ~$67,800–$84,750 |
| Conventional (20% down) — near city median | ~$565,000 | ~$113,000 (20%) | ~$11,300–$28,250 | ~$124,300–$141,250 |
A 20% down payment eliminates private mortgage insurance, which meaningfully reduces your monthly outlay — but reaching that threshold on a $565,000 home requires over $113,000 in savings before closing costs. Most first-timers in Corvallis are working with lower down payments and budgeting private mortgage insurance into the payment until equity grows.
Oregon also offers a tax-advantaged first-time homebuyer savings account through the Department of Revenue that can be applied toward a down payment, closing costs, agent commissions, or appraisal fees — worth exploring with a tax advisor alongside your loan options.
Looking to buy in Corvallis? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Corvallis quote.
Common First-Time Buyer Mistakes in Corvallis
Shopping Before You Have a Pre-Approval Letter
This one sounds obvious, but it's the most common way first-timers lose a home they wanted in Corvallis. The market moves quickly enough that the gap between "I should get pre-approved" and "I have a verified pre-approval letter in my hand" is exactly where a good listing disappears. Get the letter first. Then start touring.
Waiving the Inspection Contingency to Compete
In tighter markets, some buyers have waived inspection contingencies to make their offers more attractive. In Corvallis — with its older housing stock, wet winters, and elevated radon levels in parts of the Willamette Valley — this is a particularly high-stakes gamble. A failed sewer lateral or a radon remediation need on a house you can't renegotiate is a five-figure problem. The better move is a pre-offer inspection on a property you're serious about, which lets you keep the contingency while still presenting a clean offer.
Buying Near Campus Without Understanding the Neighbor Turnover
College Hill and the blocks immediately adjacent to the Oregon State University campus run above the city median in price and come with a street-level reality that surprises some first-time owner-occupants: high rental concentration, parking competition, and neighbor turnover that follows the academic calendar rather than the usual residential rhythm. None of that makes those blocks a bad buy — but buyers who didn't factor it in tend to be the ones who are surprised six months in. Tour on a weekday during the school year, not a summer weekend, before you make an offer in that corridor.
Underestimating Total Cash Needed at Closing
The down payment is the number everyone focuses on. The number that actually breaks deals is the full cash-at-table figure: down payment plus closing costs (2% to 5% in Oregon) plus the property tax proration that Oregon's arrears system creates at closing. On a $565,000 purchase, closing costs alone can run $11,300 to $28,250 depending on your loan type and the terms you negotiate. Budget the full amount — not just the down payment — before you write your first offer.
Ignoring School Boundary Lines When Buying for the Long Term
Corvallis School District 509J holds a B+ rating, according to Niche, with 5,858 students enrolled in 2025-26. But within the district, individual school assignments are determined by address boundary lines that don't always follow neighborhood names as buyers understand them. If you're buying with school assignment in mind, verify the specific boundary at your target address before making an offer — not after. The Corvallis schools guide has more detail on the district's structure and individual school profiles.
Local Expert Takeaway: Corvallis rewards first-time buyers who do the preparation work before they fall for a house. Get your pre-approval verified and in hand, budget the full closing-cost range on top of your down payment (Oregon's arrears tax system adds to that figure at the table), and spend time in the neighborhoods at different hours before you make an offer — especially near campus, where the street dynamic shifts with the academic calendar. Entry-level buyers willing to look at South Corvallis and Willamette Landing will find the most realistic footholds. Albany and Lebanon both offer noticeably lower prices if the Corvallis budget is a stretch, but buyers who can make the numbers work here tend to stay — the bike infrastructure, the riverfront, and the walkable compact city are genuine daily-life assets that show up in quality of life, not just in a listing description.
Quick Takeaways & FAQs
✅ Corvallis's compact, under-15-square-mile footprint means bike commutes replace car trips for many residents — a real offset to the higher-than-average housing costs.
⚠️ The gap between Corvallis's median household income and what it takes to buy the typical home here is roughly $79,000 — first-timers need strong savings discipline and realistic expectations about entry-level options.
📍 Oregon closes through title companies (not attorneys), property taxes are paid in arrears and prorated at closing, and Measure 50 means the seller's tax history understates what you'll actually owe — three Oregon-specific details that affect your cash-at-table number.
What is the typical home price in Corvallis for a first-time buyer?
Do I need a pre-approval letter before touring homes in Corvallis?
How much cash do I need at closing in Corvallis beyond the down payment?
What inspections should I get when buying a home in Corvallis?
How does Oregon's property tax system affect what I'll pay in Corvallis?
Moving to Oregon?
Tell us what you need help with and we'll connect you with local resources.
