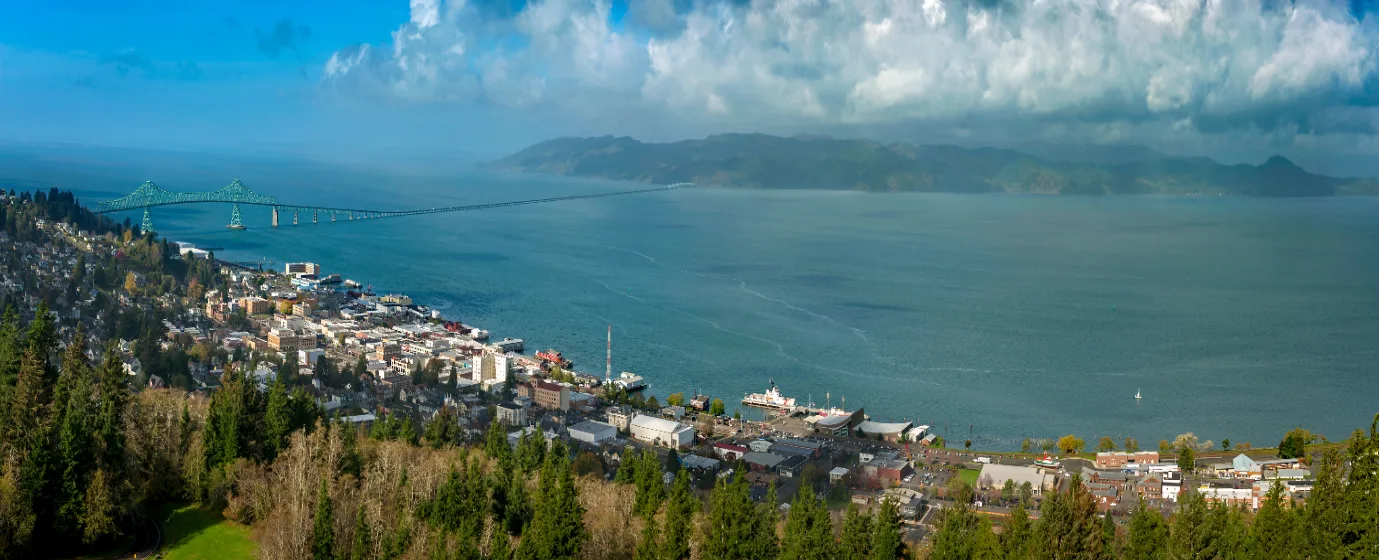
If you've priced homes in Portland and then looked at Astoria, the numbers feel like a relief — until you dig deeper. At $486,426 (Zillow Home Value Index, July 2026), the typical home here costs noticeably less than in most Portland suburbs, but that figure doesn't tell you about the Victorian-era plumbing, the flood-zone designations along the Columbia River waterfront, or the coastal inspection checklist that adds real cost to almost every purchase. Astoria is a city of 10,109 people where the housing stock is genuinely old, the scenery is genuinely stunning, and the financial surprises are genuinely avoidable — if you know where to look.
The buyers who land here successfully share one thing: they did their homework before they fell in love with a hillside Victorian above the Shively-McClure Historic District or a Uniontown craftsman two blocks from the Astoria Riverwalk. The major employers — the local school district, Clatsop Community College, and the City of Astoria — anchor a modest but stable local economy. Many residents also commute, or work remotely; Portland International Airport (PDX) is about 95 miles away, and the drive to Portland runs about 105 minutes. That context matters when you're deciding how much house your income can actually support here.
The cost picture is mixed in ways that matter for first-timers. Oregon has no sales tax, which helps at closing. The effective property tax rate sits at approximately 0.71%, which is low by national standards. But coastal living adds costs that inland buyers rarely encounter — flood insurance for waterfront and low-lying properties, moisture remediation on older homes, and maintenance on turn-of-the-century architecture that demands more than a standard home warranty. For a fuller picture of what everyday life costs here, see the cost-of-living breakdown.
Whether you're moving from the Portland metro, relocating from out of state, or simply ready to stop renting and put roots down along the Columbia, this guide walks through what buying your first home in Astoria actually looks like — budget math, the step-by-step process, a realistic affordability table, and the mistakes that consistently trip up first-time buyers in this specific market.
The Astoria First-Time Buyer Reality
The typical home in Astoria is priced at $486,426 (Zillow Home Value Index, July 2026). That number sits well below what a comparable home costs in Portland's inner eastside or in Beaverton, but it's not a bargain in the traditional first-time-buyer sense — it's a real ask for a household earning close to the city's median income of $68,007.
The market is mixed, not uniformly competitive. Roughly half of Astoria homes have been selling below asking price, while about 28% have sold above it — a negotiating environment that gives attentive buyers real leverage on the right property. Pre-approved buyers who move decisively have options that are worth pursuing, but the pool of move-in-ready homes is genuinely limited at any given moment.
Entry-level inventory tends to cluster around smaller or less-updated homes, many of them dating to the salmon-industry boom of the 1880s through early 1900s. The Shively-McClure Historic District and Uniontown carry the most concentrated Victorian and Queen Anne stock. These are genuinely beautiful homes, and they carry genuine maintenance obligations — deferred work on period plumbing, crawl-space drainage issues, and roofs that have lived through decades of coastal rain. First-timers who budget only for the purchase price often find themselves underprepared within the first year. Going in with eyes open — and a realistic contingency fund — is the difference between an Astoria success story and a cautionary one.
The Homebuying Process in Astoria, Step by Step
Step 1: Get Pre-Approved Before You Tour
This isn't advice to ignore in Astoria. The market may not be as frenzied as it was during 2021–2022, but well-priced homes on the Columbia-view hillsides still attract multiple offers. A seller's agent here will not take an unverified buyer seriously, and touring without a pre-approval letter creates expectations that your finances may not match once you see the lender's numbers.
Pre-approval means a lender has pulled your credit, verified your income and assets, and issued a conditional commitment for a loan amount. It is not the same as a pre-qualification, which is a rough estimate based on self-reported figures. In a market where roughly half of homes sell at or below list, an actual pre-approval is what separates a competitive offer from a forgettable one.
Step 2: Understand the Coastal Inspection Checklist — Before You Make an Offer
This is the step Astoria first-timers most consistently underestimate. A standard general inspection is not enough here. Oregon requires home inspectors to be licensed through the Oregon Construction Contractors Board (CCB); verify that license before hiring anyone. Beyond that baseline, coastal buyers routinely add a sewer scope, a moisture evaluation, and a crawl-space drainage assessment to their inspection package.
Salt-air corrosion on plumbing fixtures, roof integrity after years of coastal storms, and moisture intrusion into older wall assemblies are issues that show up regularly in Astoria home inspections and rarely in inspections of comparable inland homes. If the property sits near the Columbia River waterfront or in a low-lying area, ask your agent about the flood zone designation and whether an elevation certificate exists. Lenders may require National Flood Insurance Program (NFIP) coverage or private flood insurance for properties in designated Special Flood Hazard Areas, and that annual cost belongs in your budget from day one.
Oregon law also requires sellers to disclose whether a property lies within a tsunami inundation zone. Review that disclosure form carefully — it's part of the standard seller's disclosure package, and skipping it is the kind of thing buyers regret later.
Step 3: Make the Offer — With the Right Contingencies
In a market where many listings attract patient negotiation rather than bidding wars, buyers have some room to maneuver. That does not mean stripping contingencies to win. Retain your inspection contingency on any older home. The financing contingency protects you if the appraisal comes in short — a real risk when lending on Victorian-era or heavily updated homes where comparables can be thin. Experienced local agents know which seller situations warrant a more aggressive offer structure and which are better approached with patient negotiation.
Step 4: Appraisal and Underwriting
Your lender orders the appraisal after the offer is accepted. If the appraised value comes in below your purchase price, you'll need to renegotiate the price, cover the gap in cash, or walk away under the financing contingency. In a city with a relatively small inventory of comparable sales and a large share of one-of-a-kind older homes, appraisal gaps are not rare. Budget for this possibility before you make an offer.
Step 5: Closing
Oregon is an escrow state — a title company or escrow agent handles the closing, not a real estate attorney. Closing costs in Oregon typically run 2–3% of the purchase price on the buyer's side, covering lender fees, title insurance, escrow fees, prepaid homeowners insurance, and prepaid property taxes. On an Astoria-priced home, that's a real number. See the affordability table below for estimates by scenario.
How Much Home Can You Afford in Astoria
The table below lays out what different loan scenarios and purchase prices actually require at the closing table — down payment plus estimated closing costs, combined into the cash you need on hand. These are estimates, not quotes; your lender will issue a Loan Estimate after pre-approval with figures specific to your situation. Use this as a planning tool, not a final number.
Oregon has no sales tax, and the effective property tax rate is approximately 0.71% annually. For monthly payment estimates — including principal, interest, taxes, and insurance — use the mortgage calculator below, which lets you enter current rates and your specific numbers. The table here is intentionally limited to the cash-at-closing picture, which is where first-time buyers most commonly run short.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (2–3%) | Cash Needed at Table |
|---|---|---|---|---|
| FHA minimum (3.5%) | $350,000 | $12,250 (3.5%) | $7,000–$10,500 | ~$19,250–$22,750 |
| Conventional (3%) | $350,000 | $10,500 (3%) | $7,000–$10,500 | ~$17,500–$21,000 |
| FHA minimum (3.5%) | $430,000 | $15,050 (3.5%) | $8,600–$12,900 | ~$23,650–$27,950 |
| Conventional (5%) | $430,000 | $21,500 (5%) | $8,600–$12,900 | ~$30,100–$34,400 |
| FHA at city typical price | $486,426 | $17,025 (3.5%) | $9,729–$14,593 | ~$26,754–$31,618 |
| Conventional (10%) | $486,426 | $48,643 (10%) | $9,729–$14,593 | ~$58,372–$63,236 |
The Clatsop County FHA loan limit is set above the city's typical home price, which means most Astoria first-time buyers purchasing at or near that typical price can access FHA financing without exceeding the county cap. FHA loans require mortgage insurance — both an upfront premium rolled into the loan and an annual premium — which affects your monthly payment; the calculator below will model that accurately once you enter your scenario.
A note on the lower end of the price range: homes priced below $400,000 in Astoria do exist, but they tend to require the most attention — deferred maintenance, older mechanical systems, or significant cosmetic work. Budget a contingency reserve of at least several percent of the purchase price for the first year of ownership, separate from your closing cash. That buffer is not optional on a 120-year-old coastal home.
Looking to buy in Astoria? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Astoria quote.
Common First-Time Buyer Mistakes in Astoria
Touring Before You're Pre-Approved
Astoria is a small market. The pool of move-in-ready homes under $450,000 is genuinely limited at any given moment, and the agents representing those sellers know it. Walking through a home without a pre-approval letter isn't just premature — it sets you up to make emotional decisions before you've confirmed your financial position. Get the letter first. Then tour.
Waiving the Inspection Contingency on an Old Coastal Home
This mistake has a specific shape in Astoria. Buyers who arrive from hotter inland markets — Portland, Beaverton, or from out of state — sometimes waive inspection contingencies to compete, a tactic that can make sense on newer construction. On a Victorian in the Shively-McClure Historic District or a century-old Uniontown bungalow, it is a risk in a different category. Moisture intrusion, corroded plumbing fixtures, deteriorated crawl-space drainage, and roof systems at the end of their life are not rare findings — they are standard findings on many homes in this city's oldest stock. Retain the inspection contingency. Always.
Ignoring the Flood Zone and Tsunami Disclosure
Two disclosures that inland Oregon buyers rarely think about are standard practice here. Oregon law requires sellers to disclose whether a property is in a tsunami inundation zone, and that disclosure is on the standard paperwork — not buried in fine print. Separately, properties in Special Flood Hazard Areas require flood insurance, which is a recurring annual cost that belongs in your budget model before you make an offer, not after. Ask your agent to pull the flood zone designation on any property near the Columbia River waterfront or low-lying areas of Uniontown and Smith's Point before you get attached to a listing.
Underestimating Closing Cash — and the First-Year Maintenance Budget
First-time buyers routinely calculate the down payment and then treat closing costs as a rounding error. In Oregon, buyer-side closing costs genuinely run 2–3% of the purchase price. On a home at the city's typical price point, that's a real addition to the cash you need on hand. Even buyers who've budgeted correctly for closing day sometimes arrive unprepared for what comes next: on an older coastal home, the first year of ownership frequently surfaces deferred maintenance that the inspection flagged but the buyer mentally set aside. Build a contingency reserve into your financial plan — one that's funded and available, not theoretical. Many experienced buyers in Astoria treat this as non-negotiable.
Misreading the Market as Either Frenzied or Soft
The current Astoria market sits in a genuinely mixed position — not the frenzied seller's market of a few years ago, but not a buyer's market where patience alone wins everything. About half of recent homes sold below asking; about 28% sold above it. The practical implication: the right offer strategy depends entirely on the specific property and seller situation. A well-priced hillside Victorian with Columbia River views and fresh updates may still attract competing offers. A lower-priced fixer in Alderbrook that has been sitting for months probably will not. Come in with a pre-approved offer and an agent who knows which situation you're in — not a blanket assumption about the whole market.
Local Expert Takeaway: Buying your first home in Astoria rewards preparation more than it rewards speed. The Victorian and Queen Anne homes that define neighborhoods like Shively-McClure and Uniontown are genuinely compelling, but they demand a coastal inspection package that goes well beyond a standard walkthrough — sewer scope, moisture evaluation, crawl-space drainage, and a flood zone check before you make an offer. FHA financing is accessible at the city's typical price point within the Clatsop County loan limit. Get pre-approved before you tour, retain your inspection contingency, and budget a realistic contingency reserve for year-one maintenance. The buyers who skip those steps are the ones who learn the lesson the hard way on a 120-year-old house two blocks from the Riverwalk.
Quick Takeaways & FAQs
✅ FHA financing works at Astoria's typical price point — the Clatsop County FHA loan limit is set above the city's $486,426 typical home price, so most first-time buyers here can access it without exceeding the cap.
⚠️ Coastal inspections here routinely include sewer scopes, moisture evaluations, and crawl-space drainage checks that inland Oregon buyers rarely need — budget for all of them, not just the standard general inspection.
📍 Oregon law requires sellers to disclose tsunami inundation zone status on the standard disclosure form — review it carefully on any Astoria property, especially near the Columbia River waterfront.
What credit score do I need to buy a home in Astoria, Oregon?
Is the Astoria housing market competitive for first-time buyers?
Do I need flood insurance to buy a home in Astoria?
What makes buying an older home in Astoria different from buying in an inland Oregon city?
How much cash do I actually need to close on a home in Astoria?
Moving to Oregon?
Tell us what you need help with and we'll connect you with local resources.
