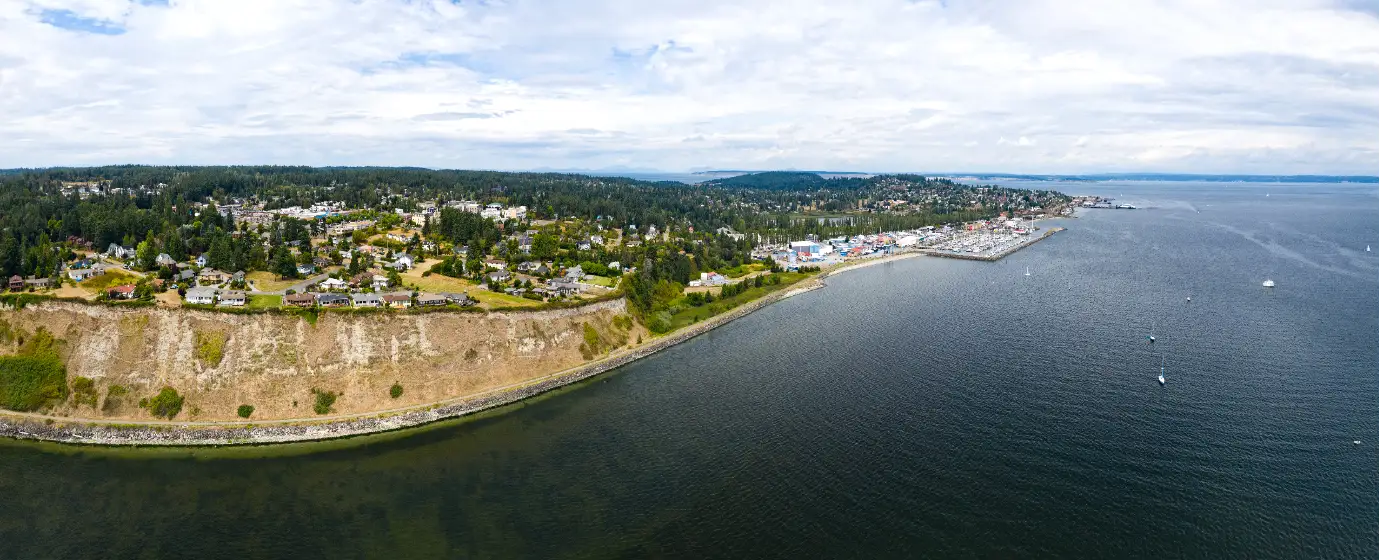
Maybe someone told you Port Townsend was more affordable than Seattle. That's technically true — but "more affordable" is doing a lot of work in that sentence. The Zillow Home Value Index for Port Townsend sat at $642,884 in May 2026, up 1.4% year-over-year. On a median household income of $62,271, that ratio is genuinely difficult, and first-time buyers who arrive expecting a sleepy, inexpensive Victorian seaport tend to recalibrate fast. The Olympic Peninsula keeps Port Townsend physically isolated — one ferry crossing and a two-lane highway separate it from most of greater Puget Sound — and that isolation has historically protected home values even when softer markets hit elsewhere.
The good news heading into mid-2026: inventory has risen sharply. Active listings climbed roughly 52% year-over-year to approximately 87 homes, and supply sits at 3.1 months — still a seller's market by technical definition, but meaningfully better than the near-zero-supply conditions of 2021–2022. Homes are averaging around 15–19 days on market and selling at roughly 99.2% of asking price, which means most sellers aren't leaving room for negotiation, but the frenzied multi-offer pile-ons have eased somewhat. For a first-time buyer who comes in prepared, this is a more navigable market than it was two years ago.
Port Townsend's housing stock adds a layer of complexity you won't find in newer suburbs. The predominance of single detached homes were built around 1984, and a meaningful share of the Victorian-era inventory Downtown and in Uptown dates back to the 1880s and 1890s. Older homes mean older systems — and that has real implications for your inspection budget and your financing options. You'll want to understand what you're walking into before you fall in love with a Water Street Queen Anne. For a broader look at what daily life and overall costs look like here, see the cost of living in Port Townsend page.
Whether you've been researching for months or just started wondering if Port Townsend is within reach, the sections below walk through what your budget actually buys, the step-by-step buying process as it works locally, a concrete budget snapshot table, and the specific mistakes that cost first-timers the most in this market.
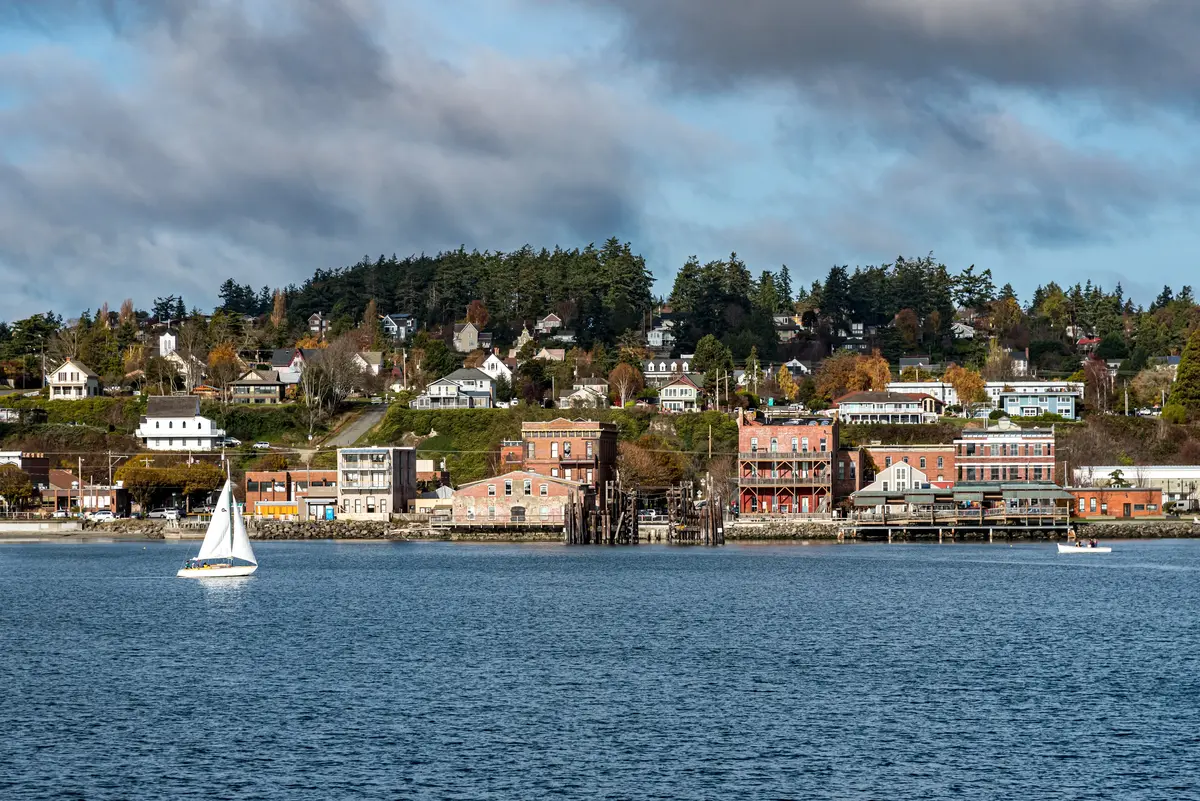
The Port Townsend First-Time Buyer Reality
At a Zillow Home Value Index of $642,884 (May 2026), Port Townsend isn't a market where first-timers walk in with a modest down payment and land a move-in-ready home without serious financial preparation. Entry-level inventory — generally older homes needing updates, smaller cottages on the outskirts near Chimacum Road, or condos — tends to cluster in the $450,000–$530,000 range when it appears. Those listings move quickly, often within two weeks.
The honest entry-point reality: under $500,000 gets you something, but rarely something turnkey. Expect deferred maintenance, oil heat systems that need replacement, or septic rather than sewer. Under $400,000 exists but is genuinely rare and usually involves significant work or a lot with buildability questions. If your budget is firm below $480,000, you need a patient strategy and a local agent who watches new listings daily — not someone who checks in weekly.
The market has softened slightly from its 2022 peak, and rising inventory gives buyers more options than they've had in years. But with homes still selling at 99.2% of list price and averaging only 15–19 days on market, this is not a place where you can leisurely tour homes for three months and then decide. First-time buyers who've been pre-approved and know their ceiling tend to be the ones who actually close. Those who haven't done the financial groundwork tend to lose homes to buyers who have — sometimes to retirees or remote workers relocating from Seattle or the Bay Area who arrive with larger reserves and no contingency anxiety.
The Homebuying Process in Port Townsend, Step by Step
Step 1: Get Pre-Approved Before You Tour Anything
This is not a formality in Port Townsend. With homes averaging fewer than 20 days on market, sellers and their agents expect to see a pre-approval letter — not a pre-qualification — attached to any serious offer. Local lenders like First Federal Savings & Loan know Jefferson County properties well, and national lenders like Guild Mortgage and Fairway Independent Mortgage are also active here. Interview at least two before choosing one.
Pre-approval requires W-2s or tax returns (usually two years), recent pay stubs, bank statements, and a hard credit pull. It typically takes three to seven business days. Don't start touring homes until you have the letter in hand.
Step 2: Choose an Agent Who Knows This Specific Market
Port Townsend has active offices for John L. Scott, Windermere, Bell Tower Brokers, and RE/MAX First Inc. Interview agents on their familiarity with older Victorian-era homes — specifically, how they handle inspection contingencies on pre-1950 properties. An agent who primarily works newer construction in Port Hadlock or Port Ludlow isn't necessarily prepared for the quirks of a Downtown Port Townsend listing.
Step 3: Make Offers With Contingencies Intact
Washington State earnest money deposits typically run 1%–3% of the purchase price. At Port Townsend's price levels, that's roughly $6,400–$19,300 that goes into escrow when your offer is accepted. The good news: financing and inspection contingencies protect that deposit — if either condition isn't met, you can generally cancel and recover it. Do not waive those contingencies to appear competitive unless you fully understand what you're giving up.
The market has softened enough that most listings are not generating the five-offer pileups common in 2021. A clean offer with standard contingencies is competitive in the current environment. Escalation clauses and contingency waivers should be reserved for truly exceptional properties with documented multiple-offer situations — not used as a default strategy.
Step 4: Inspection and Appraisal
Port Townsend's older housing stock makes the inspection phase more consequential than in newer markets. A standard general inspection is a floor, not a ceiling. For any home built before 1980, budget for add-on inspections: sewer scope (critical — many older properties still have clay or cast-iron lines), oil tank sweep if there's any evidence of fuel heat, and a structural review for homes showing foundation concerns or significant settlement. These add-ons typically run $150–$400 each.
The appraisal is ordered by your lender once you're under contract. If the appraisal comes in below the purchase price, you'll need to negotiate the difference with the seller, make up the gap in cash, or walk away using your financing contingency. In a market where homes are selling at 99.2% of list, significant appraisal gaps are not common — but they do happen on properties priced aggressively.
Step 5: Closing
Washington State uses escrow companies rather than real estate attorneys to handle closings, which keeps the process relatively streamlined. Closing typically takes 30–45 days from accepted offer to key handover. You'll do a final walk-through 24–48 hours before closing to confirm the property's condition. Closing costs in Washington generally run 2%–3% of the purchase price for buyers — plan for that cash on top of your down payment.
How Much Home Can You Afford in Port Townsend
The table below shows what different down-payment scenarios look like at several realistic price points in Port Townsend. Closing costs are estimated at 2.5% of the purchase price, which is a reasonable planning figure for Washington State buyers. All figures are approximations — your lender will provide a Loan Estimate with precise numbers for your specific scenario.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs | Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5%) — entry-level | $450,000 | $15,750 (3.5%) | ~$11,250 | ~$27,000 |
| Conventional (3%) — entry-level | $450,000 | $13,500 (3%) | ~$11,250 | ~$24,750 |
| FHA (3.5%) — mid-range | $525,000 | $18,375 (3.5%) | ~$13,125 | ~$31,500 |
| Conventional (3%) — mid-range | $525,000 | $15,750 (3%) | ~$13,125 | ~$28,875 |
| Conventional (5%) — near median | $642,884 | $32,144 (5%) | ~$16,072 | ~$48,216 |
| Conventional (10%) — near median | $642,884 | $64,288 (10%) | ~$16,072 | ~$80,360 |
These figures cover only what you bring to closing — they do not include your earnest money deposit (typically 1%–3% of the purchase price in Washington, applied toward these totals at closing), moving costs, or post-closing reserves. First-time buyers often underestimate the non-mortgage ownership costs that kick in immediately after closing: insurance, maintenance, and the effective property tax rate of approximately 0.90% in Jefferson County can combine with other carrying costs to total well over $16,000 annually, separate from your mortgage payment. Budget for those before you set your purchase-price ceiling, not after.
Looking to buy in Port Townsend? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Port Townsend quote.
Common First-Time Buyer Mistakes in Port Townsend
Waiving the Inspection Contingency on an Older Home
In a competitive situation, the temptation to waive inspection contingencies is real. In Port Townsend, it's particularly dangerous. The older Victorian and early-20th-century homes in Uptown and Downtown are genuinely beautiful — and genuinely complicated. Hidden knob-and-tube wiring, aging sewer laterals, wood foundations, and galvanized plumbing are not rare finds in this market. Walking away from a $500,000+ purchase without knowing what's behind the walls is a risk most first-timers cannot afford to absorb. Protect the contingency. If a seller won't accept an inspection contingency, that itself is information.
Shopping Before Pre-Approval
Touring homes before you have a pre-approval letter is one of the most common — and costly — mistakes in this market. You'll find a home you love on a Tuesday, spend two days getting pre-approved, and discover it went under contract Wednesday afternoon. Port Townsend's inventory is small enough (roughly 85–87 active listings in mid-2026) that desirable homes don't wait. Lining up financing before you walk into a single open house isn't just good advice — it's functionally required in this market.
Underbudgeting the Cash Needed to Close
Many first-timers calculate their down payment and assume that's the number they need. They arrive at closing surprised by closing costs (plan for approximately 2.5% of the purchase price), the earnest money deposit they've already sent (1%–3%, credited back at close), and prepaid items like homeowners insurance and initial escrow funding. On a $500,000 purchase with a 3.5% FHA down payment, your total cash outlay before moving costs can exceed $30,000. Running those numbers early — with your lender, using a Loan Estimate — prevents the unpleasant surprise of scrambling for cash two weeks before closing.
Ignoring the Commute Reality
Port Townsend's geographic position on the tip of the Olympic Peninsula means commuting anywhere is a real undertaking. Reaching Seattle requires the Kingston or Bainbridge ferry plus surface streets — a trip that runs approximately 90 minutes under good conditions and longer when ferries are delayed or full. If you're buying in Port Townsend while working remotely, this matters less day-to-day. But if you're planning to commute even two or three days a week, test that commute in person before you commit to a purchase. First-time buyers who discover the ferry line backs up on Friday afternoons tend to find this out six months after moving in — not before making an offer.
Local Expert Takeaway: Port Townsend's first-time buyer market rewards preparation and punishes hesitation. Homes near the Water Street Historic District and in Uptown sell within two to three weeks of listing, and they rarely drop in price before going under contract. The practical moves that actually work here: get fully pre-approved at a local lender like First Federal Savings & Loan or a national lender active in Jefferson County before touring anything, budget at least 2.5% of your purchase price for closing costs on top of your down payment, and never skip the sewer scope on a home built before 1985. Inventory is meaningfully higher than it was two years ago — use that breathing room to be thorough, not to be slow.
Quick Takeaways & FAQs
✅ Inventory in Port Townsend rose roughly 52% year-over-year in mid-2026, giving first-time buyers more choices than they've had since before the pandemic.
⚠️ The Zillow Home Value Index sits at $642,884 (May 2026) — well above the city's median household income of $62,271, making down-payment savings and lender selection critical steps before you even start touring.
📍 Port Townsend's older housing stock means a standard inspection isn't enough — budget for add-ons like a sewer scope and oil tank sweep, especially on homes built before 1980.
What credit score do I need to buy a home in Port Townsend?
How long does it take to buy a home in Port Townsend?
Can I buy a home in Port Townsend with an FHA loan?
What are typical closing costs for buyers in Port Townsend?
Is Port Townsend a buyer's or seller's market right now?
Moving to Washington?
Tell us what you need help with and we'll connect you with local resources.
