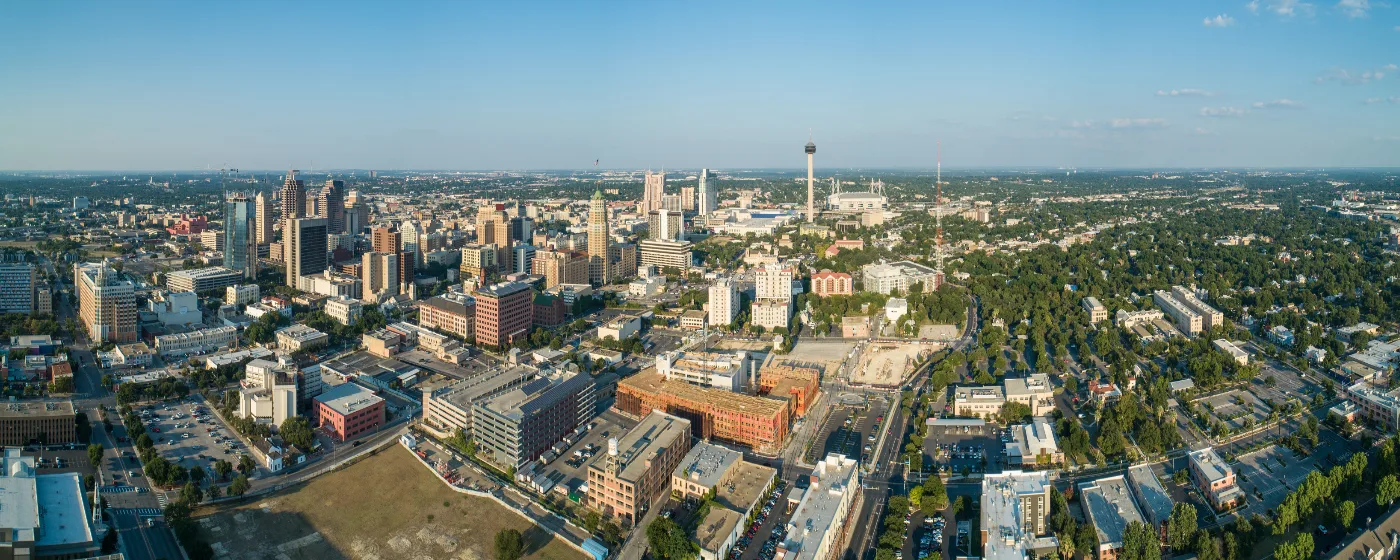
Maybe your company transferred you here, or you've been renting long enough to know you'd rather build equity than write another rent check. Either way, San Antonio has a concrete case for first-time buyers: the Zillow Home Value Index placed the typical home at $249,689 as of July 2026 — a figure that makes this one of the most attainable big-city markets in the country. That number matters, but it doesn't mean the path to closing is simple.
The economic foundation here is unusually stable for a city of 1,548,422 people. Joint Base San Antonio anchors a defense and cybersecurity economy that reached $12.4 billion in federal spending in FY2024. H-E-B and USAA are both headquartered here. University Health and Methodist Healthcare System employ thousands more. San Antonio's unemployment rate held at 3.8% in April 2025 — below the Texas rate of 4.1% and the national rate of 4.2% at that time. For a first-time buyer, that employment base matters: lenders look at job stability, and San Antonio's economy gives most buyers a credible story to tell. For a full look at the employers and economic landscape, that page goes deeper.
The honest catch is that the median household income of $65,056 runs below the income actually needed to carry the typical home here — by roughly $15,000. That gap isn't a dealbreaker, but it does mean budgeting carefully, shopping your loan options, and understanding what entry-level actually looks like on the ground. On the rental side, the cost-of-living page covers the typical rent figure and how San Antonio compares to nearby markets. The good news is that inventory has expanded significantly, sellers are making concessions, and buyers with solid pre-approval have real leverage.
Whether you're six months from being ready or six weeks out, the sections below break down what your budget actually buys in San Antonio, how the local process works step by step, a plain-language budget table, and the mistakes that cost first-timers the most in this specific market.
The San Antonio First-Time Buyer Reality
The typical home in San Antonio sits at $249,689 (Zillow Home Value Index, July 2026). That figure is real and attainable — but it represents the midpoint of the market, not the floor. Entry-level in Bexar County means older construction on the south and east sides of the city, townhomes in transitional neighborhoods, or new-build communities well outside Loop 1604. If your budget is tight, plan on trading location or square footage, not both.
Some neighborhoods run noticeably above the city-wide typical price — Stone Oak, Monte Vista, and The Dominion are priced that way for reasons first-timers can see immediately: walkable streets, proximity to employers along the US-281 corridor, or the River Walk's amenity orbit. Midtown — the cluster of neighborhoods including Tobin Hill, Five Points, Beacon Hill, and Alta Vista — draws buyers for its urban feel and proximity to downtown. You can find competitive pricing in those areas on smaller units, but a detached three-bedroom in any of these neighborhoods is a stretch at entry-level budgets. For a fuller picture of how the city's neighborhoods break down, that guide covers the geographic and character differences in detail.
The market itself has shifted in buyers' favor. Active listings across Bexar County have climbed to levels not seen in years, with a large share of sellers reducing their asking price at least once. That means pre-approved buyers who aren't in a frantic rush can negotiate, ask for closing cost credits, and take time to order inspections without fear of losing out. This is not the bidding-war environment of 2021. It rewards preparation over speed.
The Homebuying Process in San Antonio, Step by Step
Get Pre-Approved Before You Look at a Single Listing
This sounds obvious, but it is the step San Antonio first-timers most commonly skip or treat as optional. With a deep pool of active listings, it is tempting to start touring while your financial paperwork is still in a drawer. Don't. A pre-approval letter tells you what you can actually borrow, surfaces any credit issues early, and signals to sellers — and their agents — that you're a serious buyer. A credit score of at least 620 is the common lender threshold here, though a score above 700 opens up more favorable conventional loan pricing.
Shop Your Lender, Not Just Your Loan
Texas has a large and competitive mortgage market. Get quotes from at least three lenders — a local credit union, a regional bank, and an online or national lender — before you commit. The rate difference between lender A and lender B can matter meaningfully over a 30-year loan, and lender responsiveness matters just as much in a fast-moving transaction.
Make Offers Strategically
With sellers offering concessions and prices reduced on a large share of active listings, there is room to ask for help with closing costs, a rate buydown, or repairs. Pre-approved buyers with flexible closing dates hold the strongest negotiating position in this environment. Name your timeline clearly in the offer — sellers who have already reduced their price once often care more about certainty than the last dollar.
Do Not Waive the Inspection
This is where first-timers get hurt most in San Antonio specifically. The city has a large stock of 1970s and 1980s construction in the affordable price bands, and deferred maintenance — foundation issues, aging HVAC systems, older electrical panels — is common. Budget for a general inspection, and consider a separate foundation evaluation if the home shows any door-swing or flooring irregularities. Waiving the inspection to win a deal in a market this well-stocked with inventory is a trade that almost never makes sense.
Understand the Closing Timeline
From executed contract to closing, plan on 30 to 45 days for a standard purchase with a conventional or FHA loan. The appraisal is ordered by your lender, not chosen by you, and it can take one to two weeks to schedule in a busy market. Your title company — not a closing attorney, since Texas is a title-state — coordinates the settlement. Review your settlement statement carefully before closing day; the numbers should match what your Loan Estimate projected.
File Your Homestead Exemption Right After Closing
Texas's homestead exemption now removes $140,000 from your school district taxable value — a voter-approved increase that took effect in late 2025. It does not transfer from the prior owner. You must file with the Bexar County Appraisal District yourself after closing. It's one of the most valuable and most commonly missed steps first-time buyers take.
How Much Home Can You Afford in San Antonio
Closing costs in San Antonio typically run 2% to 5% of the purchase price, covering lender fees, title and escrow charges, county recording fees, and prepaid taxes and insurance. The table below uses the midpoint of that range (approximately 3%) as the closing cost estimate. Figures are approximations for planning purposes only — your lender will produce a formal Loan Estimate once you apply.
One local wrinkle worth knowing: San Antonio's property tax bill stacks levies from Bexar County, the city, the school district, Alamo Community College, and University Health on a single statement. In newer subdivisions — especially those outside Loop 1604 along I-35 or I-10 toward the growth corridors — Municipal Utility Districts (MUDs) or Public Improvement Districts (PIDs) can add 0.3% to 1.0% or more on top of the base effective rate of approximately 1.55%. Always ask whether a property sits inside a MUD or PID before making an offer. For a deeper look at the full property tax picture, that page covers it.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (≈3%) | Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5% down) — entry level | $175,000 | $6,125 | $5,250 | ≈ $11,375 |
| Conventional (3% down) — entry level | $175,000 | $5,250 | $5,250 | ≈ $10,500 |
| FHA (3.5% down) — city typical | $249,689 | $8,739 | $7,491 | ≈ $16,230 |
| Conventional (3% down) — city typical | $249,689 | $7,491 | $7,491 | ≈ $14,982 |
| Conventional (5% down) — mid-range | $300,000 | $15,000 | $9,000 | ≈ $24,000 |
| Conventional (10% down) — upper entry | $350,000 | $35,000 | $10,500 | ≈ $45,500 |
Use the mortgage calculator below to model your specific payment based on current rates and your down payment amount. The table above shows cash to close only — monthly payment, taxes, and insurance are best estimated through the calculator with your actual figures.
Looking to buy in San Antonio? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a San Antonio quote.
Common First-Time Buyer Mistakes in San Antonio
Shopping Without Pre-Approval
In a market where sellers have already been waiting longer than they'd like, a pre-approval letter isn't a formality — it's a filter. An agent who shows you homes without one is doing you a disservice, and a seller's agent who receives an offer without one will often advise their client to wait for something cleaner. Get the letter before you open a single listing tab.
Underestimating the Cash Needed at Closing
First-timers consistently budget for the down payment and forget the closing costs sitting beside it. At San Antonio's city-typical price, closing costs alone run $5,000 to $12,000 depending on the lender, title company, and how much prepaid escrow your lender requires. Add those to your down payment and you're looking at a meaningful cash requirement even on a low-down-payment loan. Sellers in today's market are offering concessions, so negotiating a credit toward closing costs is realistic — but you still need the full amount verified in your bank account to satisfy underwriting, since credits are only applied at the closing table.
Ignoring the MUD/PID Question in New Construction
New subdivisions along the I-35 corridor toward New Braunfels and the Loop 1604 growth ring often sit inside Municipal Utility Districts or Public Improvement Districts. The base price of a new build in these areas can look competitive until you add the MUD or PID assessment, which can push your effective tax rate meaningfully above the city's 1.55% baseline. Always ask the builder or listing agent directly: is this property inside a MUD or PID, and what is the full effective rate?
Skipping School Boundary Research Even Without Kids
San Antonio has dozens of school districts serving Bexar County — not just the San Antonio Independent School District. The district boundary a home sits in affects resale value, and a buyer who doesn't check the boundary before closing sometimes discovers after the fact that the neighborhood they chose feeds into a different district than they assumed. The schools page covers district performance context in detail. Check the specific boundary for any address you're seriously considering — the boundary lines don't always follow the street grid.
Skipping the Foundation Inspection on Older Stock
San Antonio's clay-heavy soil expands and contracts with rainfall cycles in ways that are unforgiving to foundations over decades. On homes built before 1990 — which make up a significant share of the affordable inventory — a general inspection alone may not surface early foundation movement. If the doors in a home don't swing cleanly, if you see diagonal cracks above doorframes, or if the floors feel uneven, spend the money on a dedicated foundation evaluation before you're under contract. That step doesn't cost much and can save you from a five-figure surprise in year two.
Local Expert Takeaway: San Antonio is genuinely one of the more accessible big-city markets for a first-time buyer — $249,689 as of July 2026 is real and reachable, not a floor that only applies to distressed properties. Expanded inventory and seller concessions make this one of the better entry windows in recent memory. What the market rewards right now is preparation: a clean pre-approval, a realistic cash-to-close number that includes closing costs, and the discipline to order a proper inspection rather than waiving it to speed up a close. The one local detail most first-timers miss is the MUD/PID question — ask it before you fall in love with a new-build in a Loop 1604 subdivision, because it changes the math.
Quick Takeaways & FAQs
✅ San Antonio's typical home price of $249,689 (July 2026) ranks it among the most affordable large-city markets in Texas, with a price-to-income ratio that independent analysts consistently place well below the national average for major metros.
⚠️ The median household income runs roughly $15,000 below what's needed to comfortably carry the typical home here — budgeting carefully and shopping loan options is not optional.
📍 New subdivisions outside Loop 1604 often sit inside Municipal Utility Districts or Public Improvement Districts that can push your effective property tax rate well above the city's 1.55% baseline — always ask before making an offer.
What credit score do I need to buy a home in San Antonio?
How much do closing costs typically run in San Antonio?
What is the homestead exemption and how does it affect my taxes in San Antonio?
Is San Antonio a buyer's market or seller's market right now?
What are the biggest differences between buying in San Antonio versus nearby cities like New Braunfels or Schertz?
Moving to Texas?
Tell us what you need help with and we'll connect you with local resources.
