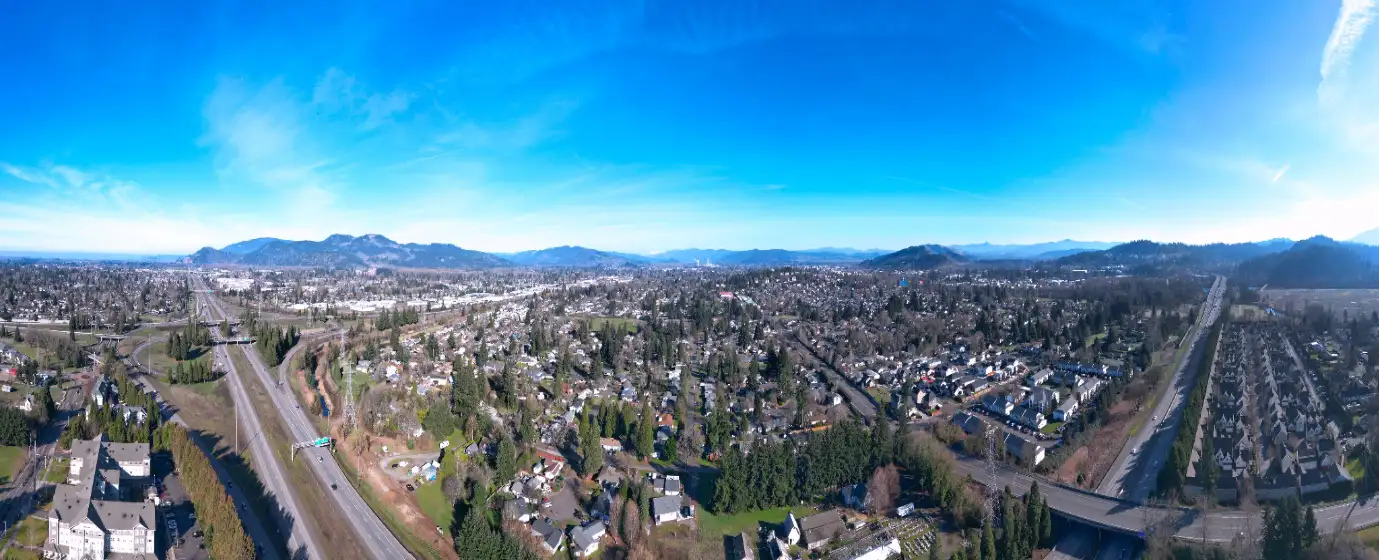
Maybe you've been renting in the Eugene-Springfield metro and watching a vacancy rate that, as of a spring 2025 city housing snapshot, sat at 0.4% — so far below a healthy market that finding another apartment feels harder than saving for a down payment. Or maybe you've looked at what Eugene asks for its entry-level homes and done the math. Springfield, Eugene's direct neighbor to the east, consistently offers prices that run somewhat lower while keeping you about 12 minutes to Eugene, connected by I-105 and a grid of bike lanes that makes the two cities feel like one place for most daily purposes. The decision to buy here rather than rent for another year is less abstract than it sounds: in a market this tight, renting is not a neutral holding pattern.
Springfield is a city of 61,182, the 10th-largest incorporated city in Oregon, and its economy is anchored by PeaceHealth Sacred Heart Medical Center, Springfield Public Schools, International Paper, and Lane County government — the kind of employer mix that keeps local purchasing power relatively stable. The median household income sits at $68,761, and the honest truth is that it falls short of what's needed to buy the typical home here without meaningful savings or a second income. That gap is real, and this guide won't paper over it. What it will show you is exactly where the entry points are, what the process looks like from pre-approval to keys in hand, and what first-timers most often get wrong in this specific market.
The typical home price in Springfield is $421,652 (Zillow Home Value Index, July 2026) — noticeably below Eugene and well below Portland, which makes Springfield one of the more accessible entry points in the Willamette Valley for buyers who have been priced out of larger Oregon cities. Day-to-day life here means Willamalane Park, the Middle Fork Path, the Washburne Historic District's walkable blocks, and a genuine small-city feel that Eugene's size doesn't quite replicate. See the full cost of living breakdown for utilities, groceries, and a deeper tax picture.
Whether you're comparing Springfield with Eugene, trying to figure out what your pre-approval should target, or just wondering whether buying here makes sense right now, the sections below cover the first-timer's reality in this market, the step-by-step process, what your cash actually buys, and the mistakes worth avoiding before you make an offer.
The Springfield First-Time Buyer Reality
The typical home in Springfield is priced at $421,652 (July 2026) — a figure that looks approachable on paper until you stack it against a median household income that falls short of qualifying by roughly the cost of a reliable used car. That gap is the central tension for most first-timers here: Springfield is genuinely more affordable than most of its Oregon neighbors, yet it still requires more household income or savings than the median Springfield family brings to the table.
Entry-level inventory is the other half of the equation. Only 4.2% of Springfield's housing stock was built since 2010, and the city has been permitted well below the pace needed to close that supply gap. What that means practically: the $300,000–$350,000 range that used to represent a true starter home has mostly dried up, and buyers in that bracket are now competing for older homes that may need real work. The Thurston area on Springfield's east side has absorbed most of the city's recent residential construction activity, and it remains the best place to look if newer-construction homes are a priority for you — though newer inventory there moves quickly and carries its own premium over older stock elsewhere in the city.
The practical entry point for move-in-ready homes in reasonable condition now starts closer to $360,000–$380,000, with anything under that figure tending to carry deferred maintenance that adds cost on the back end. Compared with Eugene — where prices run somewhat higher — Springfield does give first-timers more room to work with, but it is not the sub-$300,000 market some buyers expect from its reputation. Go in with accurate numbers and you'll find real opportunity here. Go in with wishful ones and you'll lose offers to buyers who did the math first.
The Homebuying Process in Springfield, Step by Step
Step 1: Get Pre-Approved Before You Tour Anything
In Springfield's supply-constrained market, showing up to a house without a pre-approval letter is not just inconvenient — it means you cannot make a credible offer when something good comes up, and good inventory here does not wait. Pre-approval (not pre-qualification) means a lender has pulled your credit, verified your income and assets, and issued a commitment letter with a specific purchase ceiling. Do this before you schedule a single showing.
Step 2: Know Your Loan Type Before You Choose a Price Range
FHA loans require 3.5% down and accept credit scores as low as 580, making them the most common path for Springfield first-timers with limited cash. Conventional loans at 3% down are available to buyers with stronger credit profiles and carry no upfront mortgage insurance premium, though private mortgage insurance applies until you reach 20% equity. Your lender should walk through both scenarios with your actual numbers — the difference in monthly cost between the two can be meaningful at Springfield price points.
Step 3: Shop Strategically
Gateway, Washburne Historic District, and North Springfield tend to offer the widest range of price points and housing ages. Thurston skews newer and has been absorbing most of the recent construction activity. Understanding what each area trades in — lot size, commute pattern, school boundary — matters more than buyers expect. See the neighborhood guide before you narrow your search geographically.
Step 4: Make an Offer — and Understand Your Contingencies
Oregon is an escrow state, not an attorney state, so your transaction will be managed by a title and escrow company rather than a closing attorney. Standard offers in Springfield include an inspection contingency and a financing contingency. The step most first-timers get wrong locally: waiving the inspection contingency on an older home to compete on price. Given that the vast majority of Springfield's housing stock predates 2010, skipping the inspection is where buyers absorb the real financial risk — deferred maintenance on a 40-year-old house is not abstract.
Step 5: Inspection, Appraisal, and Closing
Once your offer is accepted, the inspection comes first — budget time for it and attend in person. The lender's appraisal follows and is required for any financed purchase; if the appraised value comes in below the purchase price, you'll need to renegotiate, make up the difference in cash, or exit the contract under your appraisal contingency. Oregon closing costs typically run 2%–5% of the purchase price. Closings in Oregon happen through escrow, and the process from accepted offer to keys is typically 30–45 days for a financed purchase.
One Oregon-specific detail worth knowing: property taxes here are assessed on the Maximum Assessed Value under Measure 50 limits, not the current market value — and that assessed value does not reset at sale. An older Springfield home that has been owned for decades may carry a much lower assessed value than a comparable newly built home. Ask to see the MAV, not just the Real Market Value, when you're evaluating what a property will actually cost you annually. More on how this affects your budget is on the cost of living page.
How Much Home Can You Afford in Springfield
The table below is a working snapshot — all figures are estimates, labeled as such, and intended to give you a realistic starting point for your own conversations with a lender. Closing costs are estimated at 2%–5% of the purchase price, consistent with Oregon norms. The interactive mortgage calculator below this section will let you run your own numbers at current rates.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs | Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5%) — below-median entry | ~$340,000 | ~$11,900 (3.5%) | ~$6,800–$17,000 (2%–5%) | ~$18,700–$28,900 |
| Conventional (3%) — below-median entry | ~$340,000 | ~$10,200 (3%) | ~$6,800–$17,000 (2%–5%) | ~$17,000–$27,200 |
| FHA (3.5%) — near city median | ~$421,000 | ~$14,735 (3.5%) | ~$8,420–$21,050 (2%–5%) | ~$23,155–$35,785 |
| Conventional (3%) — near city median | ~$421,000 | ~$12,630 (3%) | ~$8,420–$21,050 (2%–5%) | ~$21,050–$33,680 |
| Conventional (5%) — near city median | ~$421,000 | ~$21,050 (5%) | ~$8,420–$21,050 (2%–5%) | ~$29,470–$42,100 |
| Conventional (10%) — newer construction | ~$450,000 | ~$45,000 (10%) | ~$9,000–$22,500 (2%–5%) | ~$54,000–$67,500 |
Oregon's statewide median down payment for single-family home purchases was $65,341 in 2024 — more than double the national median — which reflects how much of a hurdle upfront cash represents for buyers entering without existing equity. If your savings are below the figures in the table, it is worth asking your lender specifically about low-down-payment conventional options and Oregon's tax-advantaged First-Time Home Buyer Savings Accounts, which allow pre-tax savings toward a down payment, closing costs, agent commissions, and appraisal fees for accounts opened before the end of 2026.
Looking to buy in Springfield? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Springfield quote.
Common First-Time Buyer Mistakes in Springfield
Mistake 1: Starting Your Search Before Your Pre-Approval Is in Hand
This is the single most common misstep, and Springfield's thin inventory makes it costly. Buyers who fall in love with a home before talking to a lender often discover their actual ceiling is lower than they assumed — or that their credit profile needs work before any lender will touch the file. Start with the lender. The houses will still be there when you're ready, and you'll make a stronger offer when you are.
Mistake 2: Waiving the Inspection on Older Homes
In a competitive situation, waiving the inspection contingency feels like a reasonable concession to win an offer. On a Springfield home built before 1990 — which describes most of the stock — it is one of the most expensive gambles a first-timer can take. Older plumbing, aging electrical panels, and foundation issues that are invisible at a showing become your problem the moment escrow closes. Keep the inspection. Negotiate on price instead if you need to compete.
Mistake 3: Ignoring School Boundary and Commute Realities
Springfield Public Schools holds a C rating, according to Niche, and individual school quality varies meaningfully by neighborhood. A home in Gateway and a home in Thurston may feed different schools within the same district, and that matters to families with school-age children. Similarly, buyers who work in Eugene sometimes underestimate how much the specific part of Springfield they buy in affects their daily commute — the city spans enough east-to-west distance that it is worth mapping your actual drive before you commit to a neighborhood. See the schools page for boundary details and the living in Springfield page for commute context.
Mistake 4: Underbudgeting the Cash Required at Closing
Oregon's 2%–5% closing cost range sounds manageable until you apply it to a $420,000 purchase and realize the upper end is over $21,000 — on top of your down payment. Many first-timers budget for the down payment and treat closing costs as a secondary concern, then scramble in the final two weeks of escrow. Build both figures into your savings target from the start, and ask your lender early whether seller-paid closing costs are realistic in current market conditions. Arriving at the table short of cash is not a recoverable situation.
Local Expert Takeaway: Springfield gives first-time buyers a real foothold in the Willamette Valley — the city median of $421,652 (July 2026) is noticeably below Eugene, and Oregon's closing cost structure keeps total transaction costs manageable compared with many West Coast markets. But the entry-level supply is genuinely constrained, older homes dominate the inventory, and the upfront cash requirement surprises almost every buyer who hasn't run the full numbers. Get pre-approved first, keep your inspection contingency on any home built before 1990, and check the Maximum Assessed Value on older properties before you assume the tax bill matches what a comparable new-construction home would carry. Thurston is the area of Springfield where first-timers are most likely to find newer construction — worth tracking if the older-home maintenance risk feels like too much to take on.
Quick Takeaways & FAQs
✅ Springfield's typical home price of $421,652 (July 2026) sits noticeably below Eugene, making it one of the more accessible entry points in the Willamette Valley for first-time buyers.
⚠️ The median household income in Springfield falls short of what's needed to buy the typical home here by a meaningful margin — most first-timers will need strong savings, a dual income, or a below-median purchase target.
📍 Oregon's Measure 50 means a long-held Springfield home may carry a much lower assessed value than a newly built one of similar size — always ask to see the Maximum Assessed Value before making an offer.
What credit score do I need to buy a home in Springfield, Oregon?
How much do I need saved before buying a first home in Springfield?
Are there first-time homebuyer programs specific to Springfield?
How long does it take to close on a home in Springfield, Oregon?
Is Springfield a competitive market for first-time buyers right now?
Moving to Oregon?
Tell us what you need help with and we'll connect you with local resources.
