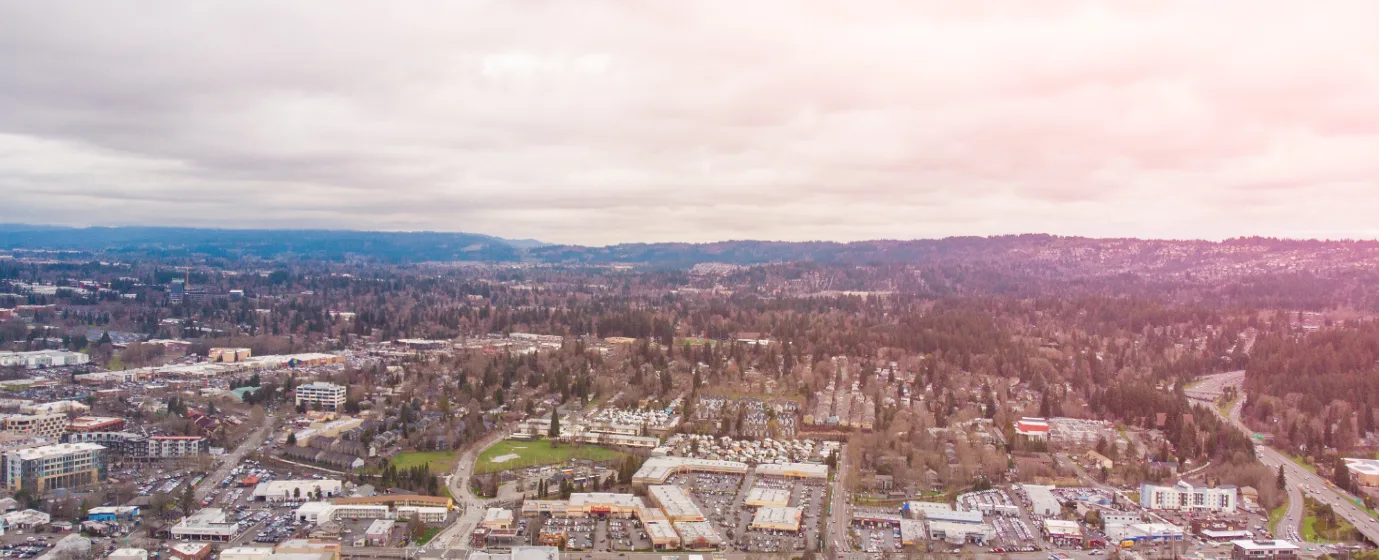
Maybe your company is relocating you to the Hillsboro tech corridor and you want a neighborhood that feels suburban without feeling isolated. Maybe you have been renting in Beaverton and watching Bethany from a distance, wondering if the jump to ownership is realistic. The honest answer: it is possible, but the entry point here is steep enough that going in without a clear financial picture is a mistake most first-timers in this market cannot afford to make twice.
Bethany sits in Washington County on Portland's western edge, a community of 33,106 built largely around medium-to-large single-family homes and owner-occupants who tend to stay. The Beaverton School District — which holds an A- rating, according to Niche — is a genuine draw for families with school-age children, and the proximity to Nike, Kaiser Permanente, and Intel's Hillsboro campus means the buyer pool here is well-employed and competitive. That competition is the first thing this guide will help you understand before you ever schedule a showing.
Bethany's median household income is $167,735, which is strong by any regional measure — and still falls short of what most lenders want to see behind an offer on a typical home here. For context on the full cost of living in Bethany, including taxes and utilities, that page breaks it down in detail. The community's vacancy rate sits at approximately 1.4%, lower than roughly 89% of all U.S. neighborhoods — which tells you something important about supply before you ever look at a listing.
Whether you are buying for the first time or re-entering the market after three or more years away from ownership — Oregon follows HUD's definition, so that second group qualifies as first-time buyers too — the sections below walk through what your budget actually buys here, how the buying process works locally, what the cash requirements look like across realistic scenarios, and where first-timers most often go wrong in this specific market.
The Bethany First-Time Buyer Reality
Bethany's typical home price puts the entry bar well above what most buyers without existing equity are prepared for, and it is the first number worth sitting with before you do anything else. The full price breakdown lives on the cost of living page, but the short version is this: Bethany is not a market where you can stretch a modest down payment and coast through.
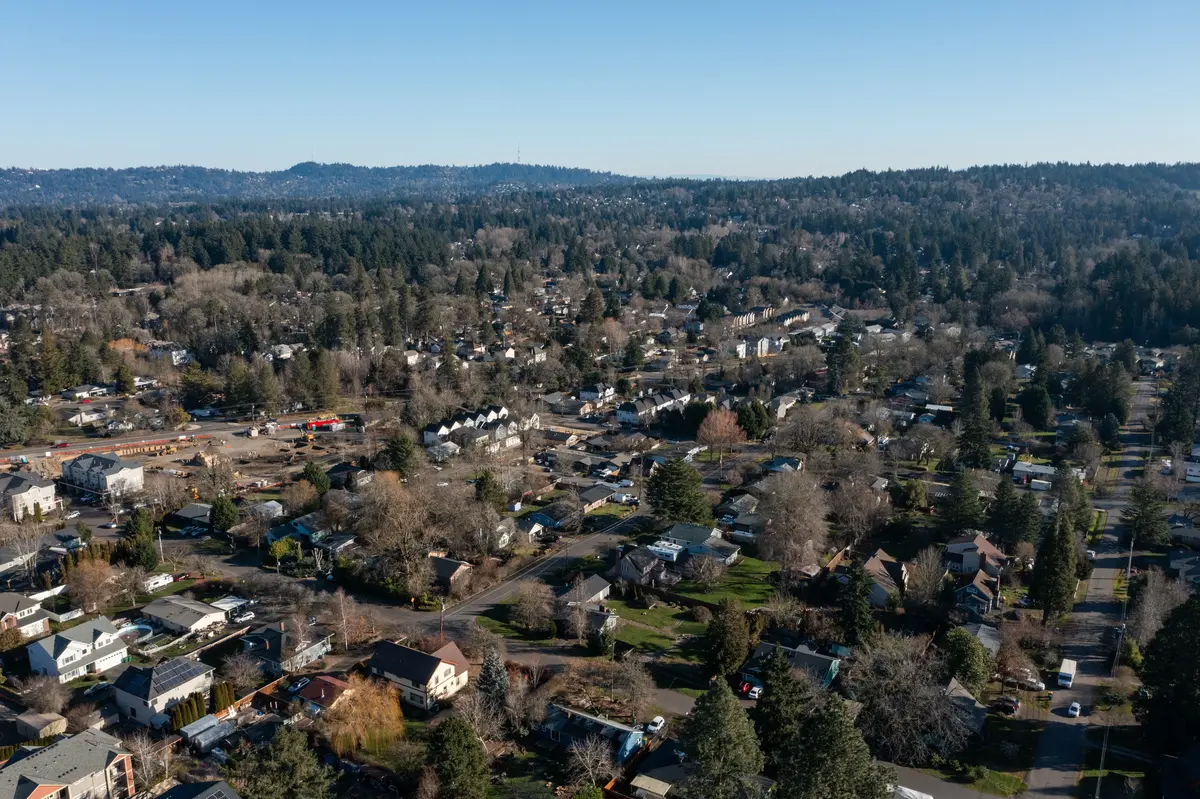
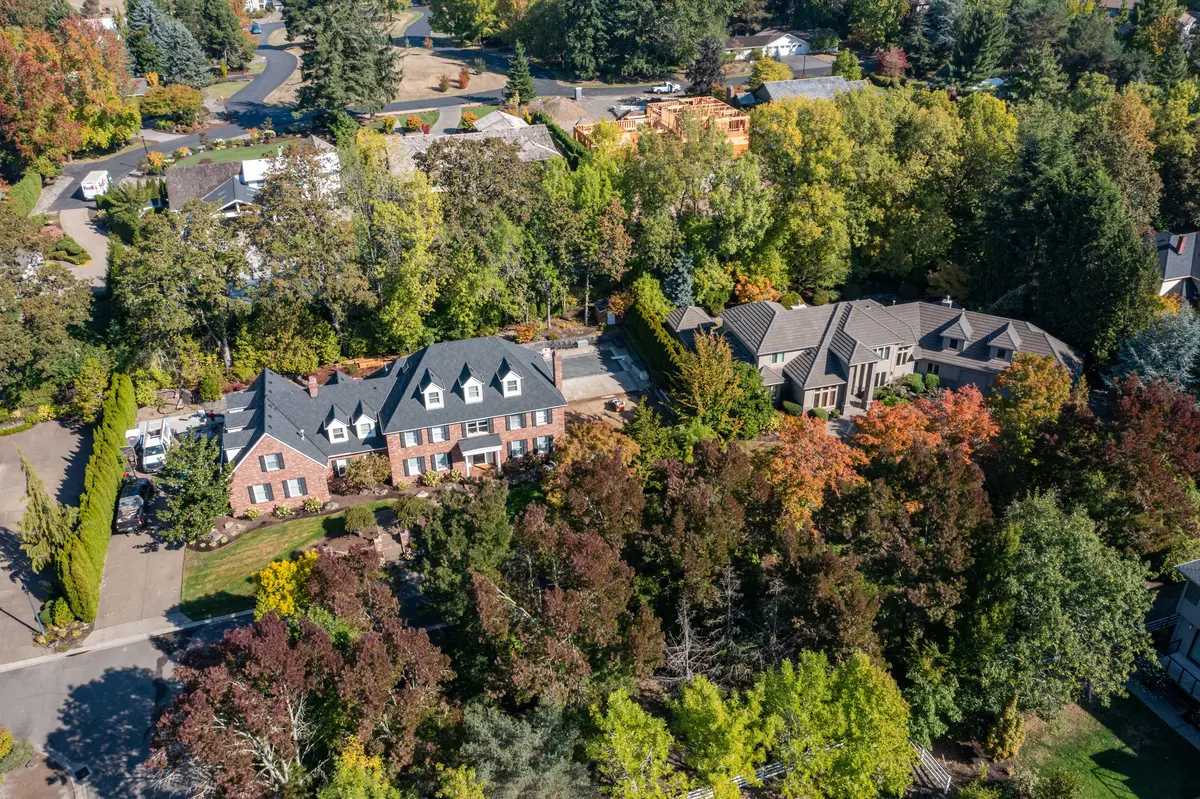
What does that price actually buy? In Bethany, the housing stock runs heavily toward medium-to-large single-family detached homes — think four-bedroom colonials in Bauer Highlands and Claremont, newer construction in North Bethany from builders like Toll Brothers, Pulte Homes, Taylor Morrison, and Noyes Development, and established resale homes in Arbor Heights and Bethany Ridge. Townhomes and smaller attached units exist but are not the dominant product here. If your budget sits meaningfully below the city-wide typical price, you are not necessarily priced out, but you are competing for a thinner slice of the inventory.
The most realistic entry point for a first-timer stretching their budget is North Bethany's new construction, where builder concessions — seller credits toward closing costs or rate buydowns — have been available on select homes. That flexibility can meaningfully reduce what you need at the table on closing day, which matters when cash is the constraint more than qualifying income. Beaverton and Hillsboro both carry noticeably lower typical prices if Bethany's entry point simply does not work — worth knowing before you spend months chasing a number that keeps moving away from you. See the full neighborhood breakdown if you want to understand which parts of Bethany tend to attract which buyer profiles.
The Homebuying Process in Bethany, Step by Step
Step 1: Get Your Financial House in Order
Before you tour a single home, pull your credit reports, total your debts, and run an honest number on how much cash you can put toward a down payment plus closing costs. Oregon is one of the most out-of-pocket-intensive states for buyers entering without existing equity — knowing your real cash position before you fall in love with a listing saves a painful conversation later.
Step 2: Pre-Approval — Do This First, Not Second
Sellers in the Portland Metro prioritize buyers with strong financing, and Bethany is not an exception to that. A pre-approval letter tells a seller you are real; an offer without one gets passed over. Gather recent pay stubs, W-2s, two years of tax returns, asset statements, your debt picture, and a government ID — that is the standard Oregon lender package. Pre-approval letters are generally valid for 30 to 90 days, so time this to when you are genuinely ready to make offers, not months in advance.
Step 3: Define Your Search with a Local Agent
Bethany's neighborhood geography matters more than it looks on a map. North Bethany is still partially built out — the planned North Bethany Main Street mixed-use corridor covers roughly 13 acres and remains in progress — which means some streets there feel more finished than others. An agent who knows the difference between a Bethany Ridge resale and a Claremont new build will save you time and help you write offers that fit the submarket you are actually in.
Step 4: Make an Offer — and Understand What You Are Signing
Oregon purchase agreements include standard contingencies for inspection and financing. In a competitive situation, buyers are sometimes pressured to waive or shorten these. Understand the difference between shortening an inspection window (reasonable) and waiving the right to inspect entirely (rarely worth it for a first-timer with no equity cushion). The Oregon process from pre-approval to closing typically spans 30 to 90 days once you are under contract.
Step 5: Inspections, Appraisal, and Closing
Once under contract, you will schedule a general home inspection — do not skip it, and consider add-ons like sewer scope depending on the home's age. The lender orders an appraisal independently. If the appraisal comes in below the purchase price, you and the seller will need to renegotiate or you will need to cover the gap in cash. Washington County property tax statements arrive each October, with payments due November 15 — good to know as you model your first year of ownership costs.
How Much Home Can You Afford in Bethany
The table below shows estimated cash requirements at closing across a range of realistic purchase prices. Closing costs in Oregon typically run 2% to 5% of the purchase price, covering lender fees, appraisal, title insurance, inspections, and recording fees. These are estimates — your actual figures will vary based on lender, loan program, and negotiated terms.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (2–5%) | Est. Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5% down) | $550,000 | $19,250 (3.5%) | $11,000–$27,500 | ~$30,250–$46,750 |
| Conventional (3% down) | $550,000 | $16,500 (3%) | $11,000–$27,500 | ~$27,500–$44,000 |
| Entry-level stretch — resale | $650,000 | $32,500 (5%) | $13,000–$32,500 | ~$45,500–$65,000 |
| Near-median — established neighborhood | $750,000 | $37,500 (5%) | $15,000–$37,500 | ~$52,500–$75,000 |
| At or above median — larger home | $850,000 | $85,000 (10%) | $17,000–$42,500 | ~$102,000–$127,500 |
| New construction — North Bethany | $800,000 | $40,000 (5%) | $16,000–$40,000 (builder credits may reduce this) | ~$56,000–$80,000 (potentially less with concessions) |
Builder concessions on North Bethany new construction can shift the closing-cost line meaningfully — ask specifically what credits are available before you finalize your cash-to-close estimate. The interactive mortgage calculator below will let you model monthly payment scenarios at current rates once you land on a purchase price that fits your pre-approval.
Looking to buy in Bethany? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Bethany quote.
Common First-Time Buyer Mistakes in Bethany
Touring Before You Have Pre-Approval
This is the most common — and most costly — mistake in any competitive Portland Metro submarket. Bethany sellers expect a pre-approval letter attached to every serious offer. Touring first and getting pre-approved second means you will either lose the home you want or rush the financing process in a way that produces a worse outcome for you. Do it in the right order.
Underestimating Total Cash at Table
First-timers often budget for the down payment and forget that closing costs in Oregon add another 2% to 5% on top. On a purchase at Bethany's typical price level, that gap between what you planned and what you actually owe at closing can easily reach $15,000 to $38,000 or more. Map out the full cash requirement — down payment plus closing costs — before you set your max purchase price, not after.
Waiving the Inspection to Win a Bidding Situation
The pressure to waive contingencies is real in competitive offers. But Bethany's housing stock includes older resale homes in Bethany Ridge, Dogwood Park, and Arbor Heights where deferred maintenance is common and a sewer scope can save you from a five-figure surprise after closing. Shortening your inspection window to five days is a reasonable concession; waiving the right to inspect entirely is not a risk worth taking without an equity cushion to absorb what you might find.
Ignoring School Boundary Specifics
The Beaverton School District serves Bethany, but individual school assignments depend on which street you are on — not just which neighborhood. Buyers who care deeply about a specific elementary or middle school sometimes discover after closing that their new address feeds to a different building than the one they assumed. Confirm boundary assignments by address before you make an offer, not after. The Bethany schools page has more on what the district offers.
Local Expert Takeaway: Bethany rewards buyers who come in prepared. The vacancy rate is tight, prices are real, and sellers here have options — which means a first-timer with a clean pre-approval, a realistic cash picture, and an agent who knows the difference between a Bauer Highlands resale and a North Bethany new build will do considerably better than one who learns the market by losing offers on it. If your budget needs more room to breathe, Beaverton and Hillsboro are both worth a serious look before you commit to a price point that stretches you past what makes sense.
Quick Takeaways & FAQs
✅ Bethany is one of the few Portland Metro communities where new construction from major builders is actively available, and builder concessions in North Bethany can genuinely reduce first-timer closing costs.
⚠️ Bethany's typical home price exceeds what the median Bethany household income can comfortably support on a standard mortgage — buyers should run real pre-approval numbers, not assumptions, before falling in love with a neighborhood.
📍 Oregon follows HUD's three-year rule for first-time buyer status — if you have not owned a principal residence in the last three years, you may qualify as a first-time buyer even if you have owned before.
What is the minimum down payment to buy a home in Bethany, Oregon?
Is it hard to buy a first home in Bethany compared to nearby cities like Beaverton or Hillsboro?
How long does buying a home in Bethany typically take?
What closing costs should a first-time buyer expect in Bethany?
Does Oregon have a broader definition of 'first-time homebuyer' than I might expect?
Moving to Oregon?
Tell us what you need help with and we'll connect you with local resources.
