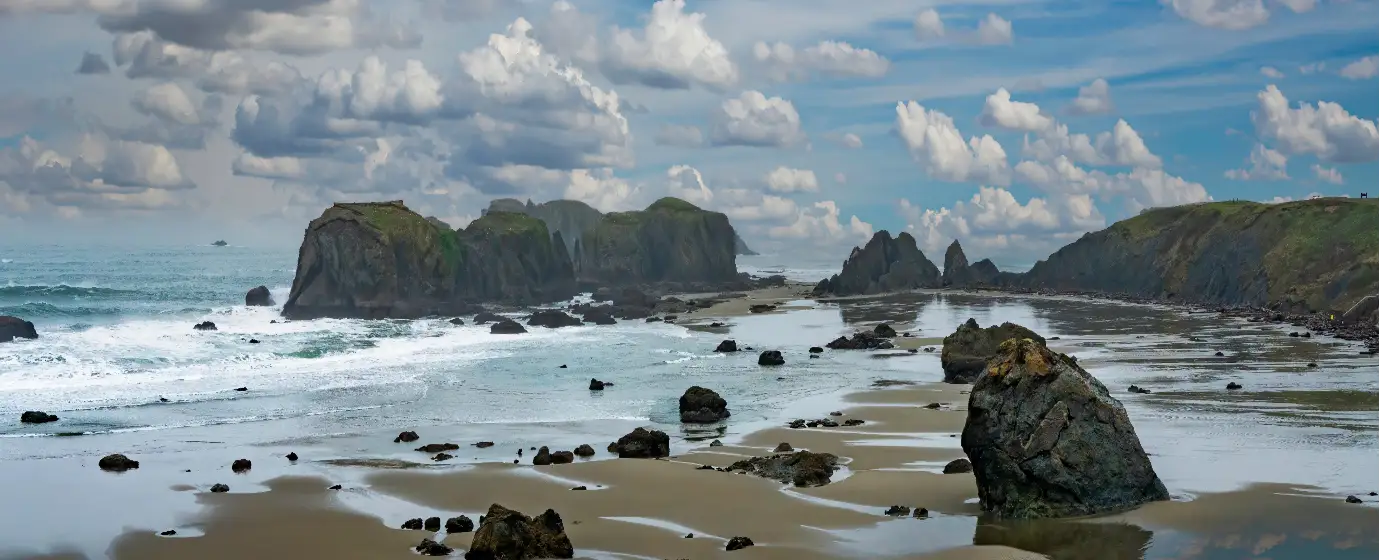
Maybe you've been priced out of the Willamette Valley and someone mentioned the Oregon Coast. Maybe you've vacationed in Bandon for years and finally decided to make it permanent. Either way, walking into this market without understanding what drives prices here is one of the most common and costly mistakes first-time buyers make. Bandon sits at the mouth of the Coquille River, accessible via US-101 (Oregon Coast Highway) and OR-42S, and its housing market does not behave like a typical small Oregon town of 3,311 people.
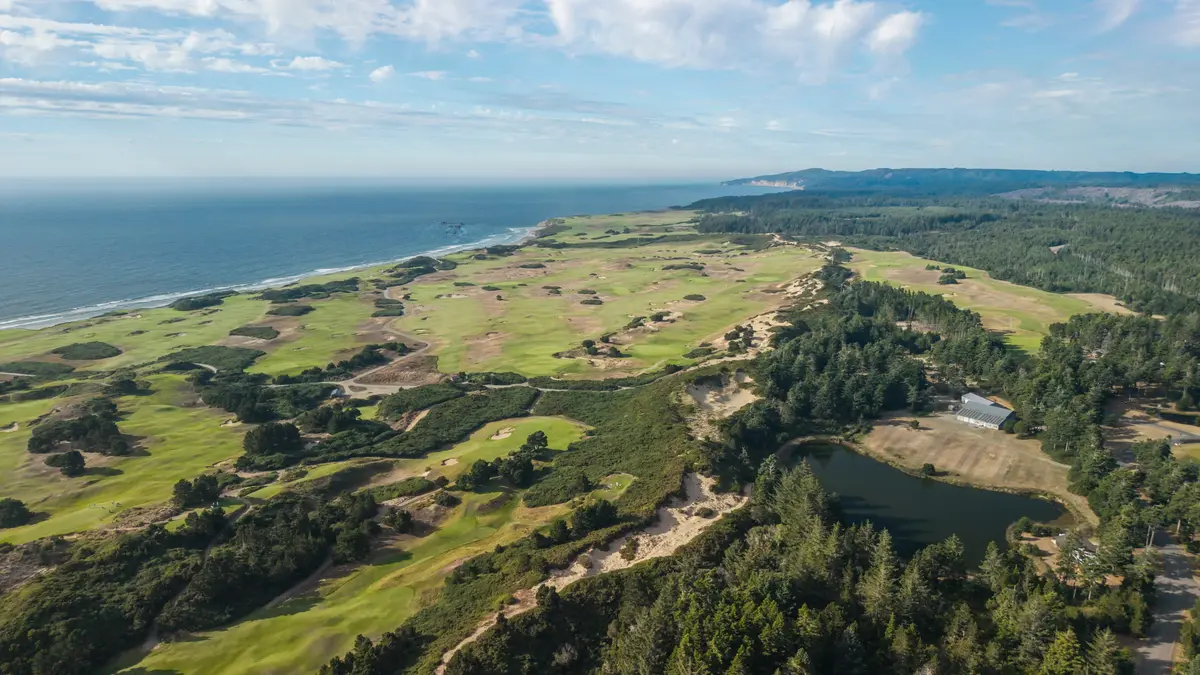
The reason is Bandon Dunes Golf Resort, which has drawn national and international attention to a city that might otherwise be priced like its neighbors. Resort-driven demand has pushed costs well above comparable small coastal Oregon communities and kept inventory tight. The Bandon School District 54 holds a B rating, according to Niche, and the district's employment base — anchored by the school district itself, Southern Coos Hospital & Health Center, and the City of Bandon — attracts working families who compete directly with second-home buyers and investors for the same limited pool of single-family homes.
The cost picture is honest but not easy. The typical home price stands at $488,995 (Zillow Home Value Index, July 2026), and the median household income in Bandon sits noticeably below what's needed to carry that price at current rates. For comparison, nearby Coquille, Coos Bay, and North Bend all come in noticeably lower — which is why many buyers weigh those markets first before deciding Bandon's lifestyle is worth the premium. The effective property tax rate of approximately 0.71% is a genuine advantage for stretched budgets, but closing costs, coastal-specific insurance, and flood-zone considerations add line items that inland buyers often don't anticipate. See the full cost-of-living breakdown for tax and utility context.
Whether you're making your first serious offer or still figuring out what you can afford, the sections below walk through what first-time buyers actually face in Bandon — the budget math, the step-by-step process, the local wrinkles that catch people off guard, and the mistakes worth avoiding before you fall in love with a listing.
The Bandon First-Time Buyer Reality
The typical home price in Bandon is $488,995 (July 2026). For a market of 3,311 people on the southern Oregon Coast, that number reflects something specific: sustained demand from a resort economy, not a suburban growth wave. Roughly 75.6% of Bandon's approximately 1,831 housing units are single-family detached homes, and the pool of entry-level inventory is genuinely small.
What does that price actually buy? At the lower end of the market — older construction, smaller lots, properties that need updating — you're looking at the mid-to-upper $300,000s. Move-in-ready homes in established neighborhoods like Bandon Heights or Sea Pines tend to cluster closer to or above the city-wide figure. Ocean-view properties or anything near the Old Town waterfront will push well past it. The gap between what you want and what your budget covers is real, and it narrows further when second-home and vacation-rental buyers compete for the same limited listings.
That vacation-rental pressure is worth understanding before you shop. The City of Bandon enacted a moratorium on new Vacation Rental Dwelling applications beginning March 2026, driven in part by a recognized shortage of middle-market housing for local workers — teachers, healthcare professionals, city staff. The moratorium was under review at the time of publication; its outcome matters because it signals which direction the city wants its residential stock to go. For a first-time buyer, a tighter vacation-rental market could eventually mean more homes available for owner-occupants. For now, though, expect competition and plan your financing before you step into a single open house.
The Homebuying Process in Bandon, Step by Step
Step 1: Get Pre-Approved — Before You Look at a Single Listing
In a small coastal market with limited inventory, sellers have no patience for unqualified buyers. A pre-approval letter is not a formality here — it is your entry ticket. Get it from a lender who understands Oregon coastal lending before you schedule your first tour. A lender unfamiliar with the market may underestimate coastal-specific underwriting friction.
Step 2: Understand the Coastal Appraisal Reality
Bandon has a thin comparable-sales pool. Coastal appraisals in this region routinely take longer than inland markets because appraisers must assess not just the structure but also coastal erosion exposure, seawall conditions, and access. If your offer is contingent on financing, build extra time into your closing timeline and discuss this with your lender upfront — an appraisal that comes in low or takes three weeks longer than expected can derail a deal.
Step 3: Check the Federal Flood Map Before You Fall in Love
Any Bandon property with a federally backed mortgage that sits inside a federally designated high-risk flood zone requires mandatory flood insurance. Properties near the Coquille River estuary, the South Jetty neighborhood, and Pacific-facing parcels are most likely to be flagged. Look up the federal flood map for any property before you make an offer, not after. The cost of flood insurance is a recurring budget line, not a one-time closing expense, and it can meaningfully change the monthly math.
Step 4: Make a Clean, Competitive Offer
First-time buyers often ask whether they can negotiate in Bandon. The answer depends on the specific property and how long it has been listed, but the general rule is: don't lead with a lowball and don't waive contingencies you actually need. The inspection contingency in particular is non-negotiable for most first-timers — coastal homes face moisture, wind, and deferred-maintenance patterns that an experienced inspector will catch and an inexperienced buyer will not.
Step 5: Inspection, Appraisal, and Closing
Schedule your home inspection as soon as the offer is accepted — don't wait. Inspectors in a small coastal market can book out, and a delayed inspection compresses your contingency window. After the appraisal clears, your lender will issue a final loan disclosure with the closing figures at least three business days before closing. Read it line by line; closing costs in Oregon typically run 2–3% of the purchase price, and first-time buyers are regularly surprised by the cash total even when they've seen an estimate.
The step first-time buyers most often underestimate locally is the flood-map check and its insurance implications — it feels like a closing detail, but it can change your effective monthly payment by hundreds of dollars and should happen before the offer, not after.
How Much Home Can You Afford in Bandon
The table below maps out the cash you'd need to bring to closing under several realistic scenarios for the Bandon market. All figures are estimates using general industry benchmarks; your lender will give you exact numbers based on your credit profile, loan program, and the specific property. The interactive mortgage calculator below the table lets you adjust the purchase price and down payment to model your own scenario at current rates.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (2–3%) | Est. Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5%) — entry level | $350,000 | $12,250 (3.5%) | $7,000–$10,500 | ~$19,250–$22,750 |
| Conventional (3%) — entry level | $350,000 | $10,500 (3%) | $7,000–$10,500 | ~$17,500–$21,000 |
| FHA (3.5%) — near city median | $489,000 | $17,115 (3.5%) | $9,780–$14,670 | ~$26,895–$31,785 |
| Conventional (5%) — near city median | $489,000 | $24,450 (5%) | $9,780–$14,670 | ~$34,230–$39,120 |
| Conventional (10%) — mid-range | $525,000 | $52,500 (10%) | $10,500–$15,750 | ~$63,000–$68,250 |
| Conventional (20%) — avoids PMI | $489,000 | $97,800 (20%) | $9,780–$14,670 | ~$107,580–$112,470 |
A few Bandon-specific budget lines to add on top of these figures: flood insurance (mandatory for federally designated high-risk flood zone properties, quoted separately from standard homeowner's coverage), and a coastal home inspection that may cost more than a standard inland inspection given the additional systems an experienced coastal inspector will evaluate. Coos County received a federal major disaster declaration in July 2025 following severe storms, flooding, and landslides — a strong reminder that hazard insurance beyond basic homeowner's coverage is worth budgeting for, not optional.
Oregon's effective property tax rate on a Bandon home runs approximately 0.71%, which is meaningfully below the national average and eases the long-term ownership cost. But the upfront cash requirement is the real barrier for most first-time buyers here, not the ongoing payment — plan your savings target around the "cash needed at table" column first.
Looking to buy in Bandon? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Bandon quote.
Common First-Time Buyer Mistakes in Bandon
Shopping Before You Have Pre-Approval
In a market this small, the right listing can appear and go under contract before you finish a second showing. Sellers in Bandon — where inventory is tight and second-home buyers often come with cash or pre-approved offers in hand — will not wait for you to start the lender conversation. Get pre-approved, then search. Not the other way around.
Ignoring the Flood Map Until Closing
This is the single most expensive mistake first-time buyers make in coastal markets. Properties near the Coquille River estuary, South Jetty, and Pacific-facing lots frequently fall within federally designated high-risk flood zones. Mandatory flood insurance on a federally backed loan is a recurring annual cost — it does not show up in most online mortgage calculators, and it can significantly change what a home actually costs to own each month. Check the flood map before you make an offer.
Waiving the Inspection Contingency to Win a Bid
The competitive pressure in a thin-inventory market tempts first-time buyers to write offers without inspection contingencies. Resist this in Bandon specifically. Coastal homes carry moisture, wind exposure, and deferred maintenance patterns that are hard to spot without a professional inspection — and the repair costs for uncaught issues can easily dwarf any savings from winning a slightly cleaner offer. Keep the inspection. Shorten the contingency window if you need to signal seriousness, but keep the inspection.
Underestimating the Cash Needed at Closing
First-time buyers regularly arrive at closing surprised by the total. Oregon closing costs typically run 2–3% of the purchase price, and in Bandon you may also be budgeting for a longer-than-average appraisal timeline, a coastal home inspection, flood insurance, and potentially a sewer scope or other property-specific assessments. The down payment is what buyers plan for; the closing costs and prepaids are what actually catch people short. Use the table in the previous section as a starting point and confirm line-by-line with your lender before your offer is accepted.
Not Accounting for the Commute and Services Reality
Bandon is about 25 minutes to Coos Bay for larger retail, specialty healthcare, and services that aren't available locally. That drive is fine on a Tuesday afternoon and genuinely inconvenient on a weekday with a sick child or an early meeting. If your job, your specialist, or your regular errands are in Coos Bay or North Bend, the commute is a daily variable — not a weekend trip — and it belongs in your neighborhood decision, not as an afterthought. See the full living in Bandon guide for commute and employer context.
Local Expert Takeaway: Bandon is a real place to live, not just a resort backdrop, but its housing market reflects the resort economy that surrounds it. First-time buyers who succeed here do two things well: they arrive with financing already in place, and they budget honestly for the coastal-specific line items — flood insurance, a thorough inspection, and the appraisal timeline that comes with thin comparable sales. The city's vacation-rental moratorium (under review since March 2026) signals that local officials recognize the squeeze on working residents, but policy takes time. For now, the buyers who move fastest and plan most carefully are the ones who close.
Quick Takeaways & FAQs
✅ Bandon's effective property tax rate of approximately 0.71% is well below the national average, which meaningfully lowers the long-term cost of ownership compared with most Oregon markets.
⚠️ Resort-driven demand from Bandon Dunes Golf Resort keeps prices above what a city of 3,311 people would typically support — nearby Coos Bay and North Bend come in noticeably lower if budget is the primary driver.
📍 Before making any offer near the Coquille River estuary, South Jetty, or Pacific-facing lots, check the federal flood map — mandatory flood insurance on a federally backed loan can add a significant recurring cost that most online calculators don't include.
What is the typical home price in Bandon, Oregon right now?
Is Bandon a good place for first-time homebuyers?
Do I need flood insurance to buy a home in Bandon?
How much cash do I need to buy a home in Bandon as a first-time buyer?
How does Bandon's home-buying process differ from other Oregon markets?
Moving to Oregon?
Tell us what you need help with and we'll connect you with local resources.
