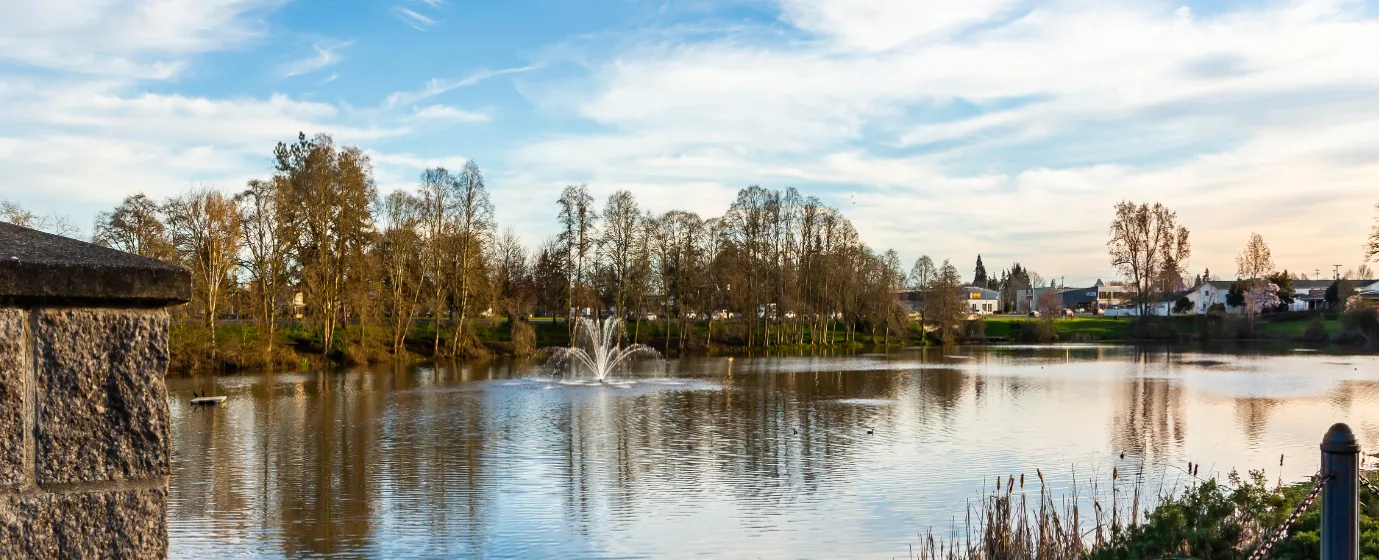
If you've been renting in Corvallis and watching prices there pull further out of reach, Albany has almost certainly come up in the conversation. The typical home price here — $439,047 as of July 2026 — sits noticeably below the Oregon statewide median, and the gap between Albany and Corvallis is wide enough to matter on a real budget. But Albany isn't a consolation prize. It's a city of 57,997 with its own historic districts, a genuine downtown, and a Willamette Valley location that makes the tradeoffs feel less like settling and more like a deliberate choice.
The city's economic backbone runs through Greater Albany Public Schools, Linn-Benton Community College, Linn County government, the Target Distribution Center, and ATI Specialty Alloys and Components — a manufacturing mix that keeps the local job market more stable than markets driven by a single industry. That stability shapes who buys here: working households, people moving from more expensive parts of Oregon, and buyers who want a real city feel without Portland prices. The Greater Albany Public School District 8J holds a B rating, according to Niche, which gives families with school-age children a reasonable starting point, though boundary details deserve a closer look before you lock in a neighborhood — see the schools page for the full picture.
Cost of living here is genuinely lower than most of the Willamette Valley, though that framing can obscure an honest tension: the median household income of $78,114 runs below what's needed to comfortably carry the typical home at current prices. That gap isn't unique to Albany, but first-time buyers need to go in with clear eyes about what their budget actually buys and what they may need to stretch for. On the lifestyle side, the city sits about 20 minutes to Corvallis along US-20, with I-5 providing the main north-south spine — Eugene Airport (EUG) is roughly 40 miles out, which covers most travel needs without a trip to Portland.
Whether you're a renter deciding it's finally time to buy or someone relocating from out of state, the sections below walk through what the Albany market actually looks like for first-timers, how the homebuying process works here step by step, what different down payment scenarios cost at the table, and the specific mistakes that trip up buyers in this market.
The Albany First-Time Buyer Reality
Albany's typical home price of $439,047 (July 2026, Zillow Home Value Index) is one of the more accessible entry points in the Willamette Valley — meaningfully below the Oregon statewide median. That matters, but it doesn't mean Albany is easy. The market is described as somewhat competitive: well-priced homes attract multiple offers, especially anything move-in ready under $400,000. Frantic bidding wars are uncommon here, but assuming you have a week to think is how buyers lose houses they actually wanted.
What does $439,000 actually get you? In neighborhoods like East Albany and South Albany, that price range reaches solid single-family homes with yards — not starter-condo territory. The Hackleman and Monteith historic districts can push above that figure for restored character homes with original millwork and covered porches, and Jackson Hill — which sits below the city median — is where buyers who want a detached home at an entry-level price point should start looking. North Albany, closer to Millersburg, skews newer construction and tends to price higher. The honest summary: there are real options here for first-timers, but the bottom of the market moves quickly, and anything priced well rarely sits.
One thing worth knowing before you start: under Oregon's HUD definition, a "first-time homebuyer" includes anyone who hasn't owned a principal residence in the last three years — not just someone who has never owned. If you sold a home more than three years ago, you may qualify for loan programs and terms structured for first-time buyers. That's a detail worth raising with a lender before you assume anything about your eligibility. For how Albany's prices compare to nearby cities, see the cost of living page.
The Homebuying Process in Albany, Step by Step
Step 1: Get Pre-Approved — Before You Tour Anything
This is not a suggestion. In Albany's somewhat competitive market, sellers and their agents filter out buyers without pre-approval letters before scheduling showings on desirable properties. Pre-approval means a lender has reviewed your income, assets, debt, and credit — not just run a soft estimate. Give yourself two to three weeks for this before you want to start touring.
Step 2: Know Your Loan Type
Most first-time buyers in Albany choose between FHA loans (3.5% down, more flexible credit requirements) and conventional loans (as low as 3% down with strong credit). For Linn County, the FHA loan limit sits comfortably above Albany's typical home price, so FHA eligibility is not a constraint for most buyers here. VA and USDA loans are also available for qualifying buyers and can require no down payment at all. Your lender will tell you which programs you qualify for; your job is to understand what each one costs in mortgage insurance and fees over time, not just the down payment figure.
Step 3: Work With an Agent Who Knows the Neighborhoods
Albany's neighborhoods feel genuinely different from each other. The historic districts have quirks — older systems, potential lead paint disclosures, stricter renovation rules — that don't apply in newer South Albany subdivisions. An agent who only knows one part of the city is a real limitation. Ask specifically about the neighborhoods you're targeting and what the inspection realities look like there.
Step 4: Make an Offer — and Understand Your Contingencies
Standard Oregon purchase agreements include an inspection contingency and a financing contingency. Do not waive either on your first purchase, and be cautious about dramatically shortening the inspection window under pressure. In Albany, where older housing stock is common in the most affordable price bands, what an inspection finds can change the calculus of a deal significantly.
Step 5: Inspection, Appraisal, and the Path to Closing
After an accepted offer, you'll typically have ten to fourteen days for inspections — general home inspection, plus any specialty inspections (sewer scope, radon, roof) the inspector recommends. An appraisal is ordered by your lender and is separate from the inspection: it confirms the home is worth what you're paying. If it comes in low, you'll negotiate with the seller or make up the gap in cash. Closing in Oregon typically takes 30 to 45 days from accepted offer. Budget time as carefully as you budget money — gaps in your employment history, large unexplained deposits, or changes in your credit during the process can all slow or derail a closing.
HUD-approved housing counselors are available statewide and can walk you through the process before you ever talk to a lender. Ask your lender which first-time buyer loan options you qualify for, and ask them to point you toward a local HUD-approved counselor if you want a structured review of your full financial picture before you start.
How Much Home Can You Afford in Albany
The table below gives a snapshot of what different purchase prices and loan scenarios require in cash at closing. Closing costs in Oregon typically run 2%–3% of the purchase price and cover lender fees, title insurance, escrow, prepaid property taxes, and homeowners insurance reserves. These are estimates — your lender will provide a Loan Estimate with exact figures after pre-approval.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (2–3%) | Approx. Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5% down) — entry-level | $325,000 | ~$11,375 (3.5%) | ~$6,500–$9,750 | ~$17,875–$21,125 |
| Conventional (3% down) — entry-level | $325,000 | ~$9,750 (3%) | ~$6,500–$9,750 | ~$16,250–$19,500 |
| FHA (3.5% down) — near city median | $439,000 | ~$15,365 (3.5%) | ~$8,780–$13,170 | ~$24,145–$28,535 |
| Conventional (3% down) — near city median | $439,000 | ~$13,170 (3%) | ~$8,780–$13,170 | ~$2$1,950–$26,340 |
| Conventional (5% down) — mid-range | $475,000 | ~$23,750 (5%) | ~$9,500–$14,250 | ~$33,250–$38,000 |
| Conventional (10% down) — stronger equity position | $475,000 | ~$47,500 (10%) | ~$9,500–$14,250 | ~$57,000–$61,750 |
The interactive mortgage calculator below this section lets you adjust purchase price, down payment, and current rates to see estimated monthly payment ranges for your specific scenario. Note that the effective property tax rate in Albany is approximately 0.97% annually — factor that into your total monthly housing cost when comparing scenarios.
One planning note that surprises many first-timers: the cash needed at closing is not just the down payment. Closing costs, prepaid insurance, and escrow reserves add up to real money on top of the down payment figure. Buyers who save exactly their down payment and nothing more often find themselves scrambling in the final week before closing.
Looking to buy in Albany? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Albany quote.
Common First-Time Buyer Mistakes in Albany
Touring Homes Without a Pre-Approval Letter
This one is the most common and the most damaging. Buyers who tour first and get pre-approved second frequently fall in love with a home that's priced above what they actually qualify for — or lose a home they could have had to a buyer who was already pre-approved when the listing went live. In a market where well-priced homes attract multiple offers, the pre-approval letter is what gets you in the game.
Waiving the Inspection Contingency on Older Albany Homes
Albany's most affordable price bands — particularly in East Albany and the historic districts — are concentrated in housing stock built decades ago. These homes can be full of character and also full of deferred maintenance: aging electrical panels, older sewer laterals that need scoping, roofs approaching end of life. Waiving the inspection contingency to compete on price is a strategy that works until it doesn't, and in Albany's older neighborhoods, a thorough inspection is often the most valuable few hundred dollars in the entire transaction. Never skip the sewer scope on a pre-1980 home here.
Ignoring School Boundary Lines When Choosing a Neighborhood
The Greater Albany Public School District serves the whole city, but specific school assignments vary by address — and boundaries don't always follow the neighborhood lines you'd expect. Two homes a few streets apart can feed into different elementary schools. If school assignment matters to your household, verify the exact attendance zone for any property before making an offer, not after. The Albany schools page has more detail on the district.
Underestimating the True Cash Requirement
The most consistent budget shock among Albany first-timers isn't the purchase price — it's arriving at the closing table underprepared for the full cash requirement. Down payment plus closing costs plus prepaid items (the first year of homeowners insurance, property tax reserves, prepaid interest) routinely add up to more than buyers projected. At a $439,000 purchase price with 3.5% down, you need roughly $24,000–$29,000 in total cash — not $15,000. Build a realistic cash target from a lender's Loan Estimate, not from a down payment calculator that ignores closing costs.
Skipping Pre-Purchase Housing Counseling
HUD-approved housing counselors are available across Oregon at no or low cost and offer something lenders typically don't have time for: a structured review of your full financial picture — credit, debt ratios, savings timeline — weeks or months before you're ready to make an offer. If you're within a year of wanting to buy, connecting with a counselor through a lender referral or a local nonprofit costs nothing and often surfaces something useful. Six months of lead time makes that conversation far more valuable than six weeks.
Local Expert Takeaway: Albany's $439,047 typical home price (July 2026) is a real entry point into Willamette Valley homeownership — but the gap between what sounds affordable and what your budget actually supports is narrower than most first-timers expect. Get pre-approved before you fall in love with a house. If you need to come in below the city median, Jackson Hill is where to start looking. Hire an inspector who knows older Oregon construction, and never skip the sewer scope on anything built before 1980. The buyers who move smoothly through this market are the ones who show up prepared — with their financing squared away, their cash reserves fully counted, and a clear picture of which school boundaries matter to their family.
Quick Takeaways & FAQs
✅ Albany's typical home price sits noticeably below the Oregon statewide median, making it one of the more accessible entry points in the Willamette Valley for first-time buyers.
⚠️ The median household income in Albany runs below what's needed to comfortably carry the typical home price — budgeting honestly from the start is the most important step a first-timer can take here.
📍 Oregon's HUD definition of 'first-time homebuyer' includes anyone who hasn't owned a primary residence in the last three years — if you sold a home more than three years ago, you may still qualify for first-time buyer loan terms.
What is the typical home price for first-time buyers in Albany, Oregon?
Can I use an FHA loan to buy a home in Albany, Oregon?
How much cash do I actually need to buy a home in Albany?
How competitive is the Albany housing market for first-time buyers?
Are there housing counselors available to help first-time buyers in Albany?
Moving to Oregon?
Tell us what you need help with and we'll connect you with local resources.
