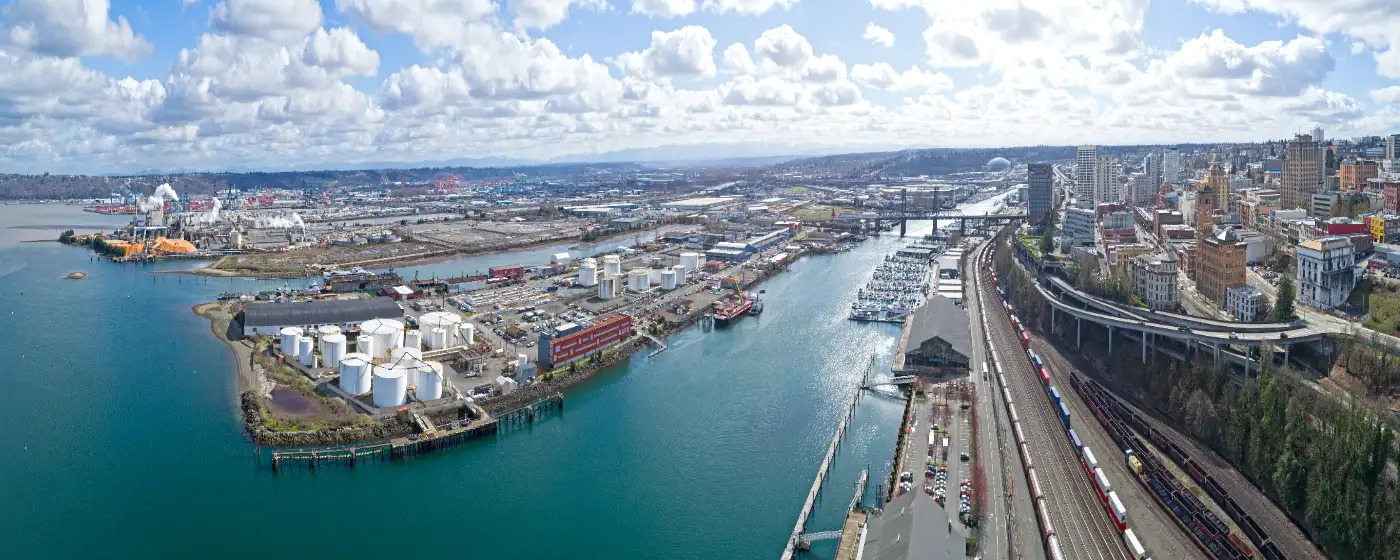
Maybe you've been renting in Fife or a nearby city and your landlord just raised the rent again. Maybe you've watched Tacoma prices climb and someone told you to look south along I-5. Either way, Fife sits in an interesting position for first-time buyers: it's genuinely more accessible than much of King County, yet it comes with a specific set of realities — thin inventory, a predominantly renter-occupied housing stock, and a flood-zone situation that catches a lot of newcomers off guard. Understanding those realities before you start scheduling tours is the difference between a smooth closing and a stressful scramble.
Fife's economy draws a workforce of working households and dual-income families who weigh what they'd pay for a comparable home in Puyallup or Federal Way against what Fife offers at a lower price point. Washington State's lack of a state income tax also meaningfully expands monthly take-home pay, which matters when you're stress-testing a mortgage payment.
At a median sold price of $529,612 (Redfin, June 2026), Fife is not a bargain market by national standards, but it runs noticeably below Seattle and much of the Eastside. The catch is that roughly 54% of Fife households are renter-occupied, which means the pool of available resale homes is genuinely small — only five single-family homes closed in June 2026. That supply constraint matters more to a first-timer than a move-up buyer, because you have less flexibility to wait out the market. For a full breakdown of what that price means for your monthly budget, the cost-of-living page goes deeper.
This guide walks you through the Fife buying process step by step, breaks down what different down-payment scenarios actually cost at the closing table, and names the specific mistakes that trip up first-time buyers in this market — from flood insurance surprises to the pre-approval timing error that kills more Fife deals than any other single factor.
The Fife First-Time Buyer Reality
The median sold price in Fife was $529,612 as of June 2026 — down about 11% year-over-year, which sounds like relief, but context matters. That 11% drop reflects a market that overheated during the pandemic era, not a collapse in fundamentals. Entry-level inventory here remains genuinely thin, and what does come to market moves at a measured but steady pace: homes sat a median of 32 days before going under contract in June 2026, giving buyers more breathing room than the frenzied 2021–2022 window, but not enough room to be casual about it.
What does $529,612 actually buy? In Fife, that range typically gets you a 3-bedroom, 2-bath resale home — often a 1970s or 1980s build — in areas like West Fife or East Fife. New construction from builders active in Fife Heights, such as Garrette Custom Homes, can push toward or past that number but often comes with builder incentives and modern energy-efficient features that older stock can't match. If your budget is meaningfully below the median, expect to compete hard for anything well-priced, because with only a handful of homes closing each month, a single desirable listing can draw multiple offers even in a softer market.
One reality that rarely shows up in online listings: Redfin's climate data flags approximately 97% of Fife properties as carrying a major flood risk over the next 30 years, a direct consequence of the city's low-lying position in the Puyallup River delta. The City of Fife also requires an Elevation Certificate before a homeowner can apply for flood insurance through the National Flood Insurance Program (NFIP). That certificate costs money, takes time to obtain, and is a required step before closing on flood-zone parcels — not something you discover after you've already fallen in love with a house. Budget for flood insurance as a line item from the start, not an afterthought.
The Homebuying Process in Fife, Step by Step
Step 1: Get Pre-Approved — Before You Tour Anything
In a market where only five homes closed in a single month, a seller has no incentive to wait for a buyer who is still shopping for a lender. Pre-approval is not a formality here — it's your entry ticket. Get a full pre-approval letter (not just a pre-qualification estimate) from a lender who can document your income, assets, and credit before you contact an agent.
Step 2: Define Your Search with Local Precision
Fife's neighborhoods sit in distinct pockets shaped by I-5, Pacific Highway East, and the industrial corridor near the port. Fife Heights is where much of the new construction activity is concentrated. West Fife and the Sunrise and Alderwood areas tend toward older resale stock. Knowing which neighborhoods fit your priorities and your flood-zone tolerance will help your agent narrow the search before inventory evaporates.
Step 3: Make Offers with Realistic Terms
Even at 32 days on market, well-priced homes in Fife attract multiple offers. Your agent should pull recent comparable sales — not list prices — to anchor your offer. In this market, an escalation clause or a clean offer with a tight timeline can matter more than a slightly higher number. First-timers often write offers with too many contingencies they don't actually need, which weakens the package without adding real protection.
Step 4: Inspection, Appraisal, and the Flood Certificate
The general home inspection is non-negotiable — older Fife homes frequently carry deferred maintenance on roofing and drainage systems. If the parcel sits in a federally designated flood zone, your lender will require a flood insurance binder before closing, and that requires an Elevation Certificate. Coordinate with your agent and lender early so the certificate is ordered at inspection rather than two days before closing.
The appraisal step matters especially if you're putting less than 20% down — if the home appraises below your purchase price, you'll need to negotiate, make up the gap in cash, or walk away. In a thin inventory market, appraisal gaps are a real risk on competitively bid homes.
Step 5: Closing
Washington State closings are handled by escrow companies rather than attorneys. Your escrow officer manages the title search, coordinates payoff of the seller's mortgage, and disburses funds. Plan for roughly 30–45 days from accepted offer to closing for a standard resale. Budget your closing costs carefully — the next section breaks down what to expect at the table for several realistic Fife price points.
How Much Home Can You Afford in Fife
Washington's lack of a state income tax gives Fife buyers more monthly take-home pay than equivalent earners in Oregon, California, or most other states — a real, concrete advantage when you're modeling a monthly payment. The interactive mortgage calculator below this section will run your specific numbers. The table here is for pre-planning: what cash do you actually need to show up at closing?
Closing costs in Washington typically run 2%–3% of the purchase price, covering title insurance, escrow fees, lender origination charges, prepaid homeowners insurance, and property tax reserves. These estimates use 2.5% as the midpoint. Flood insurance premiums, if required, are separate and vary by Elevation Certificate results — budget for them but don't include them in this table since the amount depends on individual parcel data.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (≈2.5%) | Est. Cash Needed at Table |
|---|---|---|---|---|
| FHA minimum (3.5%) — entry-level | $430,000 | $15,050 (3.5%) | ~$10,750 | ~$25,800 |
| Conventional (3%) — entry-level | $430,000 | $12,900 (3%) | ~$10,750 | ~$23,650 |
| FHA minimum (3.5%) — near median | $529,612 | ~$18,536 (3.5%) | ~$13,240 | ~$31,776 |
| Conventional (3%) — near median | $529,612 | ~$15,888 (3%) | ~$13,240 | ~$29,128 |
| Conventional (10%) — near median | $529,612 | ~$52,961 (10%) | ~$13,240 | ~$66,201 |
| Conventional (20%) — near median, no PMI | $529,612 | ~$105,922 (20%) | ~$13,240 | ~$119,162 |
The 20%-down scenario eliminates private mortgage insurance (PMI) entirely, but the cash required is substantial — roughly $119,000 before flood insurance and moving costs. Most first-time buyers in Fife realistically land in the 3%–10% down range, which means PMI is part of the equation until equity builds. At Fife's effective property tax rate of approximately 0.94%, the annual tax bill on a $529,612 purchase runs to an estimated $4,978 — factor that into your total monthly housing cost alongside principal, interest, and insurance. Use the calculator below to see how all of these variables interact at your specific price point.
Looking to buy in Fife? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Fife quote.
Common First-Time Buyer Mistakes in Fife
Shopping Before You Have a Pre-Approval Letter
With only a handful of homes closing each month, the window between a listing going active and an offer being accepted can be under a week on a well-priced property. Buyers who tour first and get pre-approved second almost always miss the home that made them want to buy in the first place. Get the letter, then schedule tours — not the other way around.
Ignoring the Flood Insurance Line Item
This is the most Fife-specific mistake on the list. Buyers who budget carefully for their down payment and closing costs, then discover mid-transaction that the parcel requires an Elevation Certificate and ongoing NFIP flood insurance premiums, often find themselves stretched in ways they didn't model. Ask your agent to flag the flood zone status of any home before you make an offer, not after inspection. The cost of flood coverage varies significantly by certificate results, so getting that information early lets you decide whether the property still pencils out.
Waiving the Inspection to Compete
The temptation to waive a home inspection to make an offer look cleaner is real in a thin-inventory market. In Fife, where a meaningful portion of resale stock dates to the 1970s and 1980s, that gamble is particularly costly. Drainage issues, aging roofing, and deferred maintenance on older systems are genuinely common findings here. An inspection contingency can be written in ways that don't make your offer toothless — your agent can help structure it — but waiving it entirely on an older Fife home is a risk that many first-time buyers later wish they hadn't taken.
Underestimating the Income Needed at the Median Price
At Fife's $529,612 median, a buyer putting 25% down would need to cover roughly $2,980 per month in estimated housing costs — which, at a standard 35% of gross monthly income, implies an annual income of approximately $102,000. That sits above the city's median household income of $90,532. Buyers near the median income who are targeting median-priced homes should model a lower purchase price or a smaller down payment rather than stretching — and should stress-test the payment against the calculator with the property tax rate and insurance included, not just the principal and interest. The cost-of-living breakdown at the Fife cost-of-living page can help you put that income figure in context.
Local Expert Takeaway: Fife's first-time buyer market rewards preparation over speed. With only a handful of single-family homes closing each month, the buyers who win are the ones who arrive with a pre-approval letter already in hand, a clear flood-zone checklist, and a realistic cash-to-close figure that includes the Elevation Certificate and flood insurance — not just the down payment. The 11% year-over-year price dip has created a more honest market than the city has seen in years, but thin inventory means that a single well-priced home on a street like 20th St E or in Fife Heights can still draw multiple offers. Come prepared, move quickly when the right house appears, and don't let a flood insurance surprise undo a deal you've spent months working toward.
Quick Takeaways & FAQs
✅ Washington's no-income-tax policy meaningfully expands monthly take-home pay, giving Fife buyers a real affordability advantage over equivalent earners in income-tax states.
⚠️ Only about five single-family homes close in Fife per month — thin inventory means first-timers who aren't pre-approved before touring routinely lose the homes they want.
📍 Roughly 97% of Fife properties carry a major flood risk rating due to the city's location in the Puyallup River delta; an Elevation Certificate is required before obtaining NFIP flood insurance, and buyers should budget for this before making an offer.
What is the median home price in Fife, WA right now?
Do I need flood insurance to buy a home in Fife?
Is FHA or conventional financing better for buying in Fife?
How competitive is the Fife housing market for first-time buyers?
What are typical closing costs for a home purchase in Fife, WA?
Moving to Washington?
Tell us what you need help with and we'll connect you with local resources.
