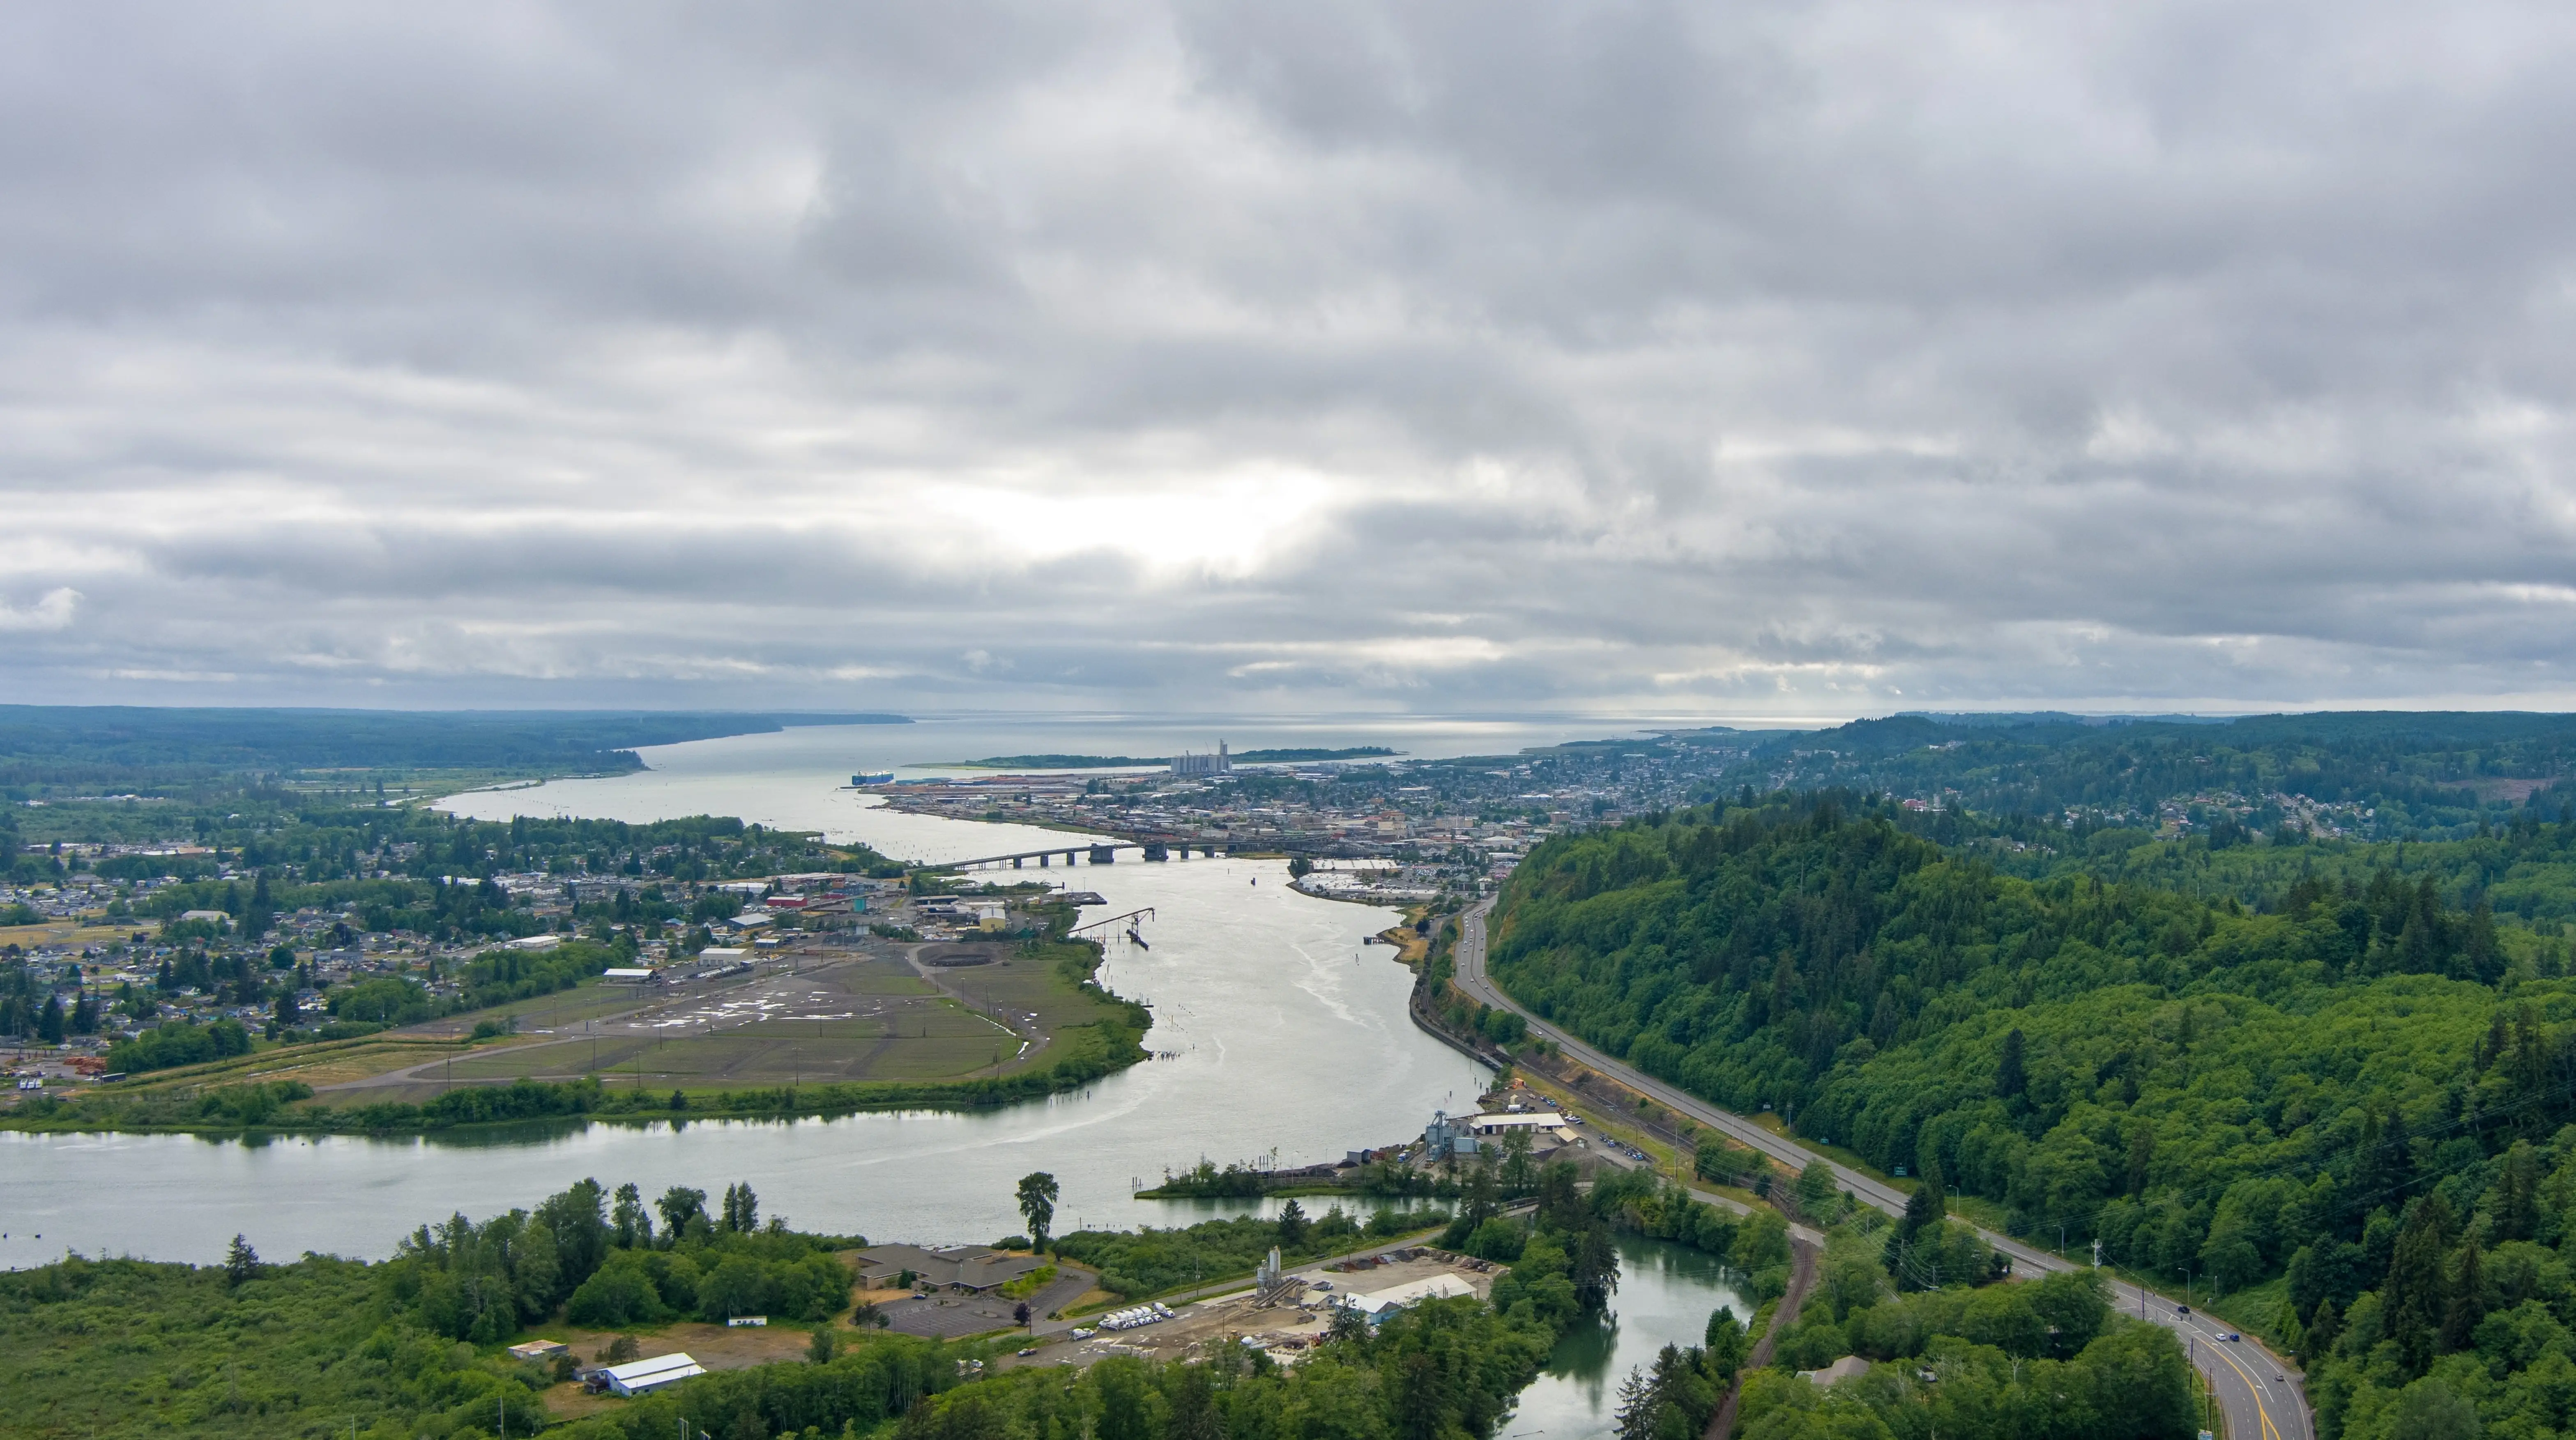
Most first-time buyers who look at Aberdeen do a double-take at the prices. The Zillow Home Value Index puts the typical Aberdeen home at $253,790 as of July 2026 — a figure that reads like a typo to anyone who spent time shopping in Seattle, Tacoma, or even Olympia. Aberdeen sits at the mouth of the Chehalis River on Washington's Olympic Peninsula, about 55 minutes west of Olympia on US-12, and the distance from those higher-cost markets is exactly what makes the math work here. What that math doesn't automatically tell you is how the local process works, where the real entry points are, and which moves will cost you the deal.
The economic foundation here matters when you're buying. A diversified base of employers — a regional health system, the Port of Grays Harbor, Sierra Pacific Industries in lumber, Ocean Spray in food processing, and a major retail anchor — means the community isn't dependent on a single industry cycle. That kind of stability is something lenders and appraisers quietly weigh when underwriting in smaller markets, and it works in your favor. Washington's lack of a state income tax also improves your debt-to-income ratio in ways that buyers coming from Oregon or California often underestimate when they first run the numbers.
The market itself is softening in ways that genuinely favor first-timers right now. Homes are averaging 49 days on market as of mid-2026 — up sharply from 30 days the year before — and transaction-based data puts the median sale price around $243,000 for the three months ending May 2026. That gives you time to conduct due diligence, negotiate repairs, and avoid the panicked decision-making that defined hotter markets in recent years. The catch is that well-priced, move-in-ready homes still move; the days-on-market figure reflects the broader inventory, not every listing equally. See the full cost-of-living breakdown for how Aberdeen compares on taxes and everyday expenses.
Whether you're a state-government employee priced out of Thurston County, a local renter finally running the buy-vs-rent math, or someone who followed the Kurt Cobain mythology here and decided to stay — the sections below walk through what your budget actually buys, the step-by-step process in this specific market, a realistic affordability snapshot, and the mistakes that most often derail first-timers in Aberdeen.
The Aberdeen First-Time Buyer Reality
The headline number is real: the Zillow Home Value Index for Aberdeen stands at $253,790 as of July 2026, making it one of the most accessible entry points in Washington state for first-time buyers. That figure is not a distressed-market outlier — it reflects a functioning, stable housing market in a working-class city with a diversified employer base. What it does not mean is that every listing near that price is a clean, move-in-ready home.
Much of Aberdeen's available inventory skews older — craftsman-era bungalows and mid-century ranchers with varying levels of maintenance. Homes priced below the citywide median often carry deferred upkeep that listing photos don't fully capture. As you approach or exceed the median, you're more likely to find updated kitchens, newer roofs, and sellers with room to negotiate on repairs.
The competitive reality is measured but real. Redfin scores Aberdeen's market at 67 out of 100 — "somewhat competitive" — as of mid-2026. That means well-priced homes in good condition still attract multiple interested buyers, even as the broader market softens. First-timers who show up to a showing without a pre-approval letter in hand are not just at a disadvantage; in a market this size, where listing agents often know the local lender pool personally, arriving unprepared signals inexperience that sellers notice. Aberdeen is affordable, but it is not a market where hesitation costs you nothing.
The Homebuying Process in Aberdeen, Step by Step
Step 1: Get Pre-Approved Before You Tour Anything
This is the step most first-timers skip, and in Aberdeen it matters more than you'd expect for a market at this price point. Because inventory is relatively thin — typically 100–150 active listings across the city at any given time — desirable homes move even when the broader market is slow. A pre-approval letter from a Washington-licensed lender tells the seller you're serious and that your financing has been vetted. A pre-qualification is not the same thing; sellers and listing agents here know the difference.
Use the current Washington state average of approximately 6.93% on a 30-year fixed rate as a planning baseline (Experian/Curinos data, July 2026). Your actual rate will vary based on your credit score, down payment percentage, and the lender you choose. Shop at least two or three lenders — local credit unions, community banks, and mortgage brokers who work the Grays Harbor County market regularly will often price more aggressively than national online lenders for loans in this price range.
Step 2: Identify Your Loan Type Early
FHA loans are the most common entry point for first-timers here. They require a minimum 3.5% down payment for borrowers with a credit score of 580 or higher, and at Aberdeen's typical price point that down payment works out to roughly $8,883 — a reachable target for most buyers who've been intentional about saving. Conventional loans are available with as little as 3% down for qualifying borrowers, typically requiring a credit score of 620 or above.
Washington state-backed loan programs — administered through the Washington State Housing Finance Commission's network of approved local lenders — offer below-market first mortgage rates for qualifying buyers. To access these programs, you must complete a free, five-hour homebuyer education seminar before closing; it's available in-person or virtually, and it's a genuine requirement, not a formality. Start this early, not the week before closing.
Step 3: Shop, Make an Offer, and Negotiate Smart
With homes averaging 49 days on market, you're less likely to face a same-day bidding war than buyers in tighter markets. Use that time deliberately: tour multiple properties before making an offer, and resist the pull of the lowest-priced listing without understanding why it's priced below its neighbors.
When you make an offer, include an inspection contingency — this is the step Aberdeen first-timers most often get wrong by waiving it to appear more competitive. Given the age of the local housing stock (many Aberdeen homes were built between the 1920s and 1960s), skipping an inspection to win a deal on a sub-$200,000 house can expose you to foundation issues, outdated wiring, or oil-tank decommissioning costs that run well into five figures. The market does not move fast enough here to justify waiving this protection.
Step 4: Inspection, Appraisal, and Closing
Budget 10–15 business days for a professional home inspection. Aberdeen's older housing stock means inspectors here are accustomed to flagging deferred maintenance, moisture intrusion from the region's heavy rainfall, and aging systems — treat the inspection report as a negotiating tool, not a reason to walk away from every imperfect house.
Your lender will order an appraisal independently. In smaller markets like Aberdeen, the appraiser's comp set can be limited, which occasionally produces appraisals that come in below the agreed purchase price. If that happens, you have three options: renegotiate the price, make up the gap in cash, or walk away using your appraisal contingency. Keep that contingency in your offer. Closing typically takes 30–45 days from accepted offer; budget closing costs at roughly 2–4% of the purchase price (see the affordability table in the next section for scenario-specific estimates).
How Much Home Can You Afford in Aberdeen
The table below models five realistic purchase scenarios for Aberdeen first-time buyers using a 30-year fixed rate of approximately 6.93% as the planning baseline. Down payment percentages shown are the program minimums; putting more down reduces your monthly obligation and eliminates private mortgage insurance at 20%. Closing cost estimates reflect the 2–4% range typical for Grays Harbor County transactions — your actual figure depends on title fees, lender charges, and whether you negotiate seller concessions.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (2–4%) | Est. Cash Needed at Table |
|---|---|---|---|---|
| FHA Minimum (3.5%) — Entry-Level Home | $180,000 | $6,300 (3.5%) | $3,600–$7,200 | ~$9,900–$13,500 |
| Conventional Minimum (3%) — Entry-Level Home | $180,000 | $5,400 (3%) | $3,600–$7,200 | ~$9,000–$12,600 |
| FHA Minimum (3.5%) — Near-Median Home | $253,790 | $8,883 (3.5%) | $5,076–$10,152 | ~$13,959–$19,035 |
| Conventional Minimum (3%) — Near-Median Home | $253,790 | $7,614 (3%) | $5,076–$10,152 | ~$12,690–$17,766 |
| Conventional (5%) — Updated/Larger Home | $290,000 | $14,500 (5%) | $5,800–$11,600 | ~$20,300–$26,100 |
| Conventional (10%) — Move-In Ready, Larger Lot | $320,000 | $32,000 (10%) | $6,400–$12,800 | ~$38,400–$44,800 |
All figures are estimates for planning purposes only; your actual closing costs, rate, and required reserves will vary by lender and loan program.
Washington has no state income tax, which helps your debt-to-income ratio look cleaner to lenders than it would for a comparable buyer in a state with 5–9% income tax withholding. The effective property tax rate in Grays Harbor County runs approximately 0.90% annually — fold that into your total housing cost alongside insurance when stress-testing your budget. The interactive mortgage calculator below lets you model your specific scenario with current rate inputs.
Looking to buy in Aberdeen? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Aberdeen quote.
Common First-Time Buyer Mistakes in Aberdeen
Waiving the Inspection on Older Stock
Aberdeen's housing inventory skews old. A surprising number of listings in the lower price ranges were built before 1960, and some go back to the lumber-boom era of the early 1900s. Moisture intrusion is the dominant issue on the Olympic Peninsula — not theoretical moisture, but active crawlspace problems, rotted sills, and deferred roof maintenance that the listing photos rarely show. First-timers who waive inspection to look more competitive on a lower-priced home are taking a risk that is genuinely not worth it in a market moving at 49 days on average.
Shopping Before Pre-Approval
Aberdeen is a small market. Listing agents here often work with a limited pool of local buyers and recognize names and faces. Showing up to tour a home — especially at a seller-hosted open house — without a pre-approval creates an impression that follows you. More practically, you may fall in love with a home and then discover your financing doesn't support that price band. Pre-approval first tells you exactly what you're shopping for.
Underbudgeting for Cash at Closing
The down payment is the number buyers fixate on. The closing costs are the number that blindsides them. On a $253,790 purchase, even the low end of the 2–4% closing cost range adds over $5,000 on top of your down payment. Add in the first year of homeowner's insurance (paid upfront at closing in most cases) and your prepaid escrow reserves, and first-timers frequently arrive at the closing table $3,000–$5,000 short of what they expected. Budget the full range from day one.
Underestimating What Aberdeen's Location Costs Over Time
Aberdeen's affordability draws buyers who work in larger nearby cities. The drive to Olympia or other employment centers is real, and so are the costs — fuel, vehicle wear, and hours per week add up over the life of a mortgage in ways that a simple rent-vs-buy comparison doesn't capture. Run those numbers honestly before deciding that a lower purchase price justifies a long daily round trip. The living in Aberdeen page covers the city's daily-life tradeoffs in more depth.
Skipping the Homebuyer Education Requirement
If you plan to use a state-backed mortgage program through the Washington State Housing Finance Commission's network of participating lenders, the five-hour homebuyer education seminar is not optional. It must be completed before closing — not scheduled for after. First-timers who discover this requirement late in the process have had closings delayed by weeks. The course is free and available virtually; schedule it during the pre-approval phase, not after you're under contract.
Local Expert Takeaway: Aberdeen's $253,790 typical home price (Zillow Home Value Index, July 2026) is one of the most credible entry points left in Washington state for a first-time buyer on a working-class income. The market is softening — 49 days on market, prices trending down year-over-year — but it still rewards preparation. Get pre-approved with a Washington-licensed lender before you tour anything, budget the full 2–4% closing cost range on top of your down payment, keep your inspection contingency in every offer on older Aberdeen stock, and complete the WSHFC homebuyer education seminar during the pre-approval phase if you're using a state-backed loan program. Do those four things and you're genuinely better positioned than most buyers who have shopped this market.
Quick Takeaways & FAQs
✅ Aberdeen's typical home price of $253,790 (Zillow Home Value Index, July 2026) makes it one of the most affordable real entry points for first-time buyers in all of Washington state.
⚠️ Aberdeen's older housing stock and the region's heavy rainfall mean moisture intrusion and aging systems are common inspection findings — never waive the inspection to win a deal here.
📍 Aberdeen's housing stock skews heavily pre-1960, meaning a professional home inspection is non-negotiable — deferred maintenance and aging systems rarely show up in listing photos but frequently show up in inspection reports.
What credit score do I need to buy a home in Aberdeen, WA?
How much cash do I actually need to buy a home in Aberdeen?
Is Aberdeen, WA a good place to buy a home right now?
What type of mortgage is best for a first-time buyer in Aberdeen?
Do I need a real estate agent to buy a home in Aberdeen?
Moving to Washington?
Tell us what you need help with and we'll connect you with local resources.
