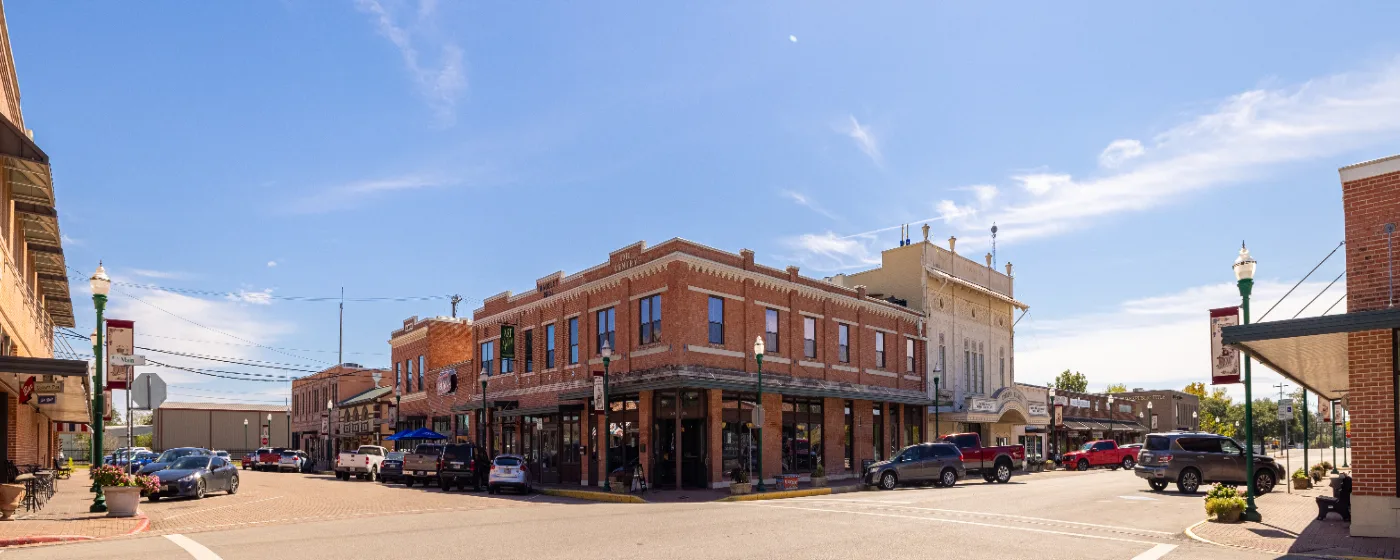
You've been renting in the Houston area, watching prices climb, and someone told you to look at Conroe. Maybe your coworker just closed on a house there. Maybe you got priced out of The Woodlands and needed the next logical step north on I-45. Either way, you're asking the right question at a complicated moment: Conroe has absorbed a sustained wave of relocating households from across the Houston metro, and that demand shows up in the offers you'll be competing against. This is not a sleepy exurb — it is an actively growing city where buyer competition is real at every price point.
Conroe is the county seat of Montgomery County, a city of 119,564 residents that has grown roughly 33% since 2020. The Conroe Independent School District — with 72,757 students enrolled in 2025-26 — is the institutional backbone of the community, and it holds a B rating, according to the Texas Education Agency. The employer base includes a regional healthcare system, a community college, and petrochemical firms whose employees commute from established subdivisions all over the northern suburbs. That workforce creates steady buyer competition at every price point.
The typical home price in Conroe sits at $315,986 (Zillow Home Value Index, July 2026) — noticeably below The Woodlands and noticeably below Montgomery, which makes this city one of the more accessible entry points into Montgomery County without leaving the county entirely. The city's effective property tax rate of approximately 1.52% is worth factoring early, because Texas leans on property tax rather than income tax, and that rate adds meaningfully to monthly carrying costs. Still, for a buyer coming from inside Loop 610, the price delta here is significant.
Whether you are buying your first home or re-entering the market after a period of renting, this guide covers what your budget actually buys in Conroe, how the buying process works locally (including a few Texas-specific steps that catch newcomers off guard), a plain-language budget table, and the most common mistakes first-time buyers make here.
The Conroe First-Time Buyer Reality
The typical home price in Conroe is $315,986 (Zillow Home Value Index, July 2026). That number is real, but it carries a catch: the median household income here sits roughly $18,000 below what it takes to comfortably carry a home at that price at current rates. That gap is not unusual for fast-growing Texas suburbs, but it means your budget math needs to be honest before you start touring.
Entry-level inventory — think older construction in established subdivisions, or smaller townhomes near Loop 336 — starts somewhere in the low-to-mid $200,000s. At that price point you're trading proximity to master-planned amenities for affordability, and you're likely competing with investors who buy at that tier for rental conversions. The master-planned communities like Grand Central Park, Artavia, and Fosters Ridge attract national builders offering new construction, which can mean builder incentives and rate buydowns that partially offset higher sticker prices — a real option worth comparing against resale.
Move-up and investor buyers have dominated the Conroe market in recent years, which means first-time buyers are rarely the majority in any competitive situation. The practical implication: come pre-approved, not pre-qualified, and treat your budget ceiling as firm rather than flexible. Sellers here have seen enough competitive offers to recognize a half-prepared buyer quickly.
One piece of context that helps: Texas defines "first-time homebuyer" broadly for state program purposes — if you haven't owned a primary residence in the past three years, you likely qualify even if you've owned before. Ask your lender which first-time buyer loan options and tax credit programs you qualify for, including any federal tax credit programs that reduce your annual tax bill for the years you stay in the home. These are not down payment programs, but they can meaningfully lower your effective carrying cost over time.
The Homebuying Process in Conroe, Step by Step
Step 1: Get a Full Pre-Approval First
Not a pre-qualification estimate — an actual pre-approval with a credit pull, income documentation, and a written letter from a lender. Since the National Association of Realtors settlement took effect in August 2024, buyers must also sign a written representation agreement with their agent before touring homes. That means your first two moves happen before you ever walk through a door: choose a lender, get pre-approved, then choose an agent and sign their agreement.
Step 2: Shop with Your Pre-Approval Letter in Hand
In Conroe's active market, a verbal offer backed by nothing is not a competitive offer. When you tour homes in Grand Central Park or Fosters Ridge and find one you want, you need to move within days, not weeks. Know your price ceiling before you fall in love with a floor plan.
Step 3: Write an Offer — and Understand the Texas Option Period
Texas contracts include something buyers from other states often miss: the option period. You pay a small non-refundable fee — typically $100 to $500 — to buy yourself a window of roughly 5 to 10 days to back out of the deal for any reason while keeping your earnest money deposit intact. This is your due-diligence window. Use it for the inspection. Do not waive it to look competitive unless your agent has a specific strategic reason in a specific situation.
Step 4: Inspection and Appraisal
Order a general inspection immediately when your option period starts — you have a short window and inspectors book out. In Conroe's climate, pay particular attention to HVAC systems, roof condition, and any drainage concerns, especially in lower-lying subdivisions. The appraisal is lender-ordered and happens in parallel; if the home appraises below the purchase price, you'll need to negotiate or cover the gap in cash.
Step 5: Title Company Closing — Not an Attorney
Texas closings are handled by a title company, not a real estate attorney — a difference that surprises buyers from states like Georgia or South Carolina. The title company manages escrow, coordinates the settlement statement, and issues both the lender's and owner's title insurance policies. The owner's policy is typically paid by the seller; you'll pay for the lender's policy. Title insurance premiums in Texas are set by the state and are not negotiable. Ask your agent to walk you through the closing disclosure at least a few days before you sign.
How Much Home Can You Afford in Conroe
Closing costs in Texas typically run 2–5% of the purchase price, covering lender fees, title insurance, escrow setup, and prepaids. Sellers may offer concessions to cover a portion of buyer costs, particularly on homes that have been on the market longer. The table below shows estimated cash needed at closing across realistic Conroe entry points; these are approximations and your actual figures will vary by lender, loan type, and negotiated terms.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (2–5%) | Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5%) — entry-level resale | $220,000 | $7,700 (3.5%) | $4,400–$11,000 | ~$12,100–$18,700 |
| Conventional (3%) — entry-level resale | $220,000 | $6,600 (3%) | $4,400–$11,000 | ~$11,000–$17,600 |
| FHA (3.5%) — near city median | $315,000 | $11,025 (3.5%) | $6,300–$15,750 | ~$17,325–$26,775 |
| Conventional (3%) — near city median | $315,000 | $9,450 (3%) | $6,300–$15,750 | ~$15,750–$25,200 |
| Conventional (5%) — master-planned new construction | $370,000 | $18,500 (5%) | $7,400–$18,500 | ~$25,900–$37,000 |
| Conventional (10%) — above-median established subdivision | $420,000 | $42,000 (10%) | $8,400–$21,000 | ~$50,400–$63,000 |
These figures exclude your monthly payment, property taxes, insurance, and HOA fees — the interactive calculator below handles those based on your actual inputs. Budget for HOA fees especially in master-planned communities, where amenity-heavy neighborhoods like Harper's Preserve and Graystone Hills carry monthly assessments that add meaningfully to carrying costs.
Looking to buy in Conroe? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Conroe quote.
Common First-Time Buyer Mistakes in Conroe
Skipping Pre-Approval and Touring Anyway
This is the single most common error, and in Conroe it's particularly costly. The market here has absorbed a sustained wave of relocating households, and sellers have seen enough offers to spot an unprepared buyer immediately. Touring without a pre-approval letter doesn't help you learn the market — it creates emotional attachment to homes you may not be able to buy, and it burns the trust of listing agents whose cooperation you'll need when a competitive situation arises.
Waiving the Option Period to Win an Offer
The Texas option period is the most Texas-specific contract feature first-timers misunderstand. Some buyers waive it entirely to look competitive. That is almost always the wrong call. The option fee is small; what you're buying with it is the right to walk away and keep your earnest money if the inspection reveals something serious — a failing HVAC system, foundation movement, or drainage problems that are genuinely common in parts of Montgomery County. Losing a few hundred dollars in option fees is far better than being locked into a home with a $15,000 foundation issue.
Underbudgeting the Cash Needed at Closing
Buyers often plan for the down payment and forget to budget closing costs separately. At a $315,000 purchase price, 2–5% in closing costs means an additional $6,300 to $15,750 on top of your down payment — not included in it. Add earnest money (typically 1% of purchase price, applied at closing but tied up beforehand), the option fee, and any inspection costs, and the total cash picture is significantly larger than the down payment alone. Run the full number before you make an offer.
Ignoring the Commute Math and School Boundary Reality
Conroe is about 50 minutes to Houston — in normal conditions, on a good day. Buyers sometimes purchase in outlying subdivisions near SH-242 or the northern edges of the city without stress-testing that commute on a Tuesday morning in rain. Separately, Conroe ISD covers a large geographic area, and school boundary assignments don't always follow neighborhood names. The school your neighbor's child attends may not be the school your child is assigned to — check the actual boundary map for any specific address before you make an offer, not after. See the full schools breakdown for district context.
Local Expert Takeaway: Conroe gives first-time buyers a real shot at Montgomery County homeownership at a price point that has been driven out of The Woodlands. But the market moves with confidence, not hesitation — get your pre-approval letter before your first tour, understand that the Texas option period is your due-diligence lifeline rather than a negotiating chip to give away, and budget your total cash need (down payment plus 2–5% closing costs) before you start shopping. The new-construction pipeline in communities like Grand Central Park and Artavia adds options resale markets rarely offer, including builder incentives worth negotiating hard. Go in with full preparation and a firm budget ceiling, and Conroe's entry-level inventory is genuinely accessible.
Quick Takeaways & FAQs
✅ Conroe's typical home price of $315,986 (July 2026) sits noticeably below neighboring The Woodlands, making it one of the more realistic entry points into Montgomery County for buyers working with a modest down payment.
⚠️ First-time buyers face real competition here — relocating households have flooded the market in recent years, and move-up and investor buyers dominate, so arriving without a pre-approval letter puts you at an immediate disadvantage.
📍 The Texas option period is a contract feature most first-timers don't know exists: a small non-refundable fee buys you a 5–10 day window to back out for any reason while keeping your earnest money — never waive it without a specific strategic reason from your agent.
What credit score do I need to buy a home in Conroe, TX?
How long does it take to close on a house in Conroe?
What are typical closing costs for a buyer in Conroe?
Is it better to buy new construction or resale in Conroe?
Do I need a real estate agent to buy a home in Conroe?
Moving to Texas?
Tell us what you need help with and we'll connect you with local resources.
