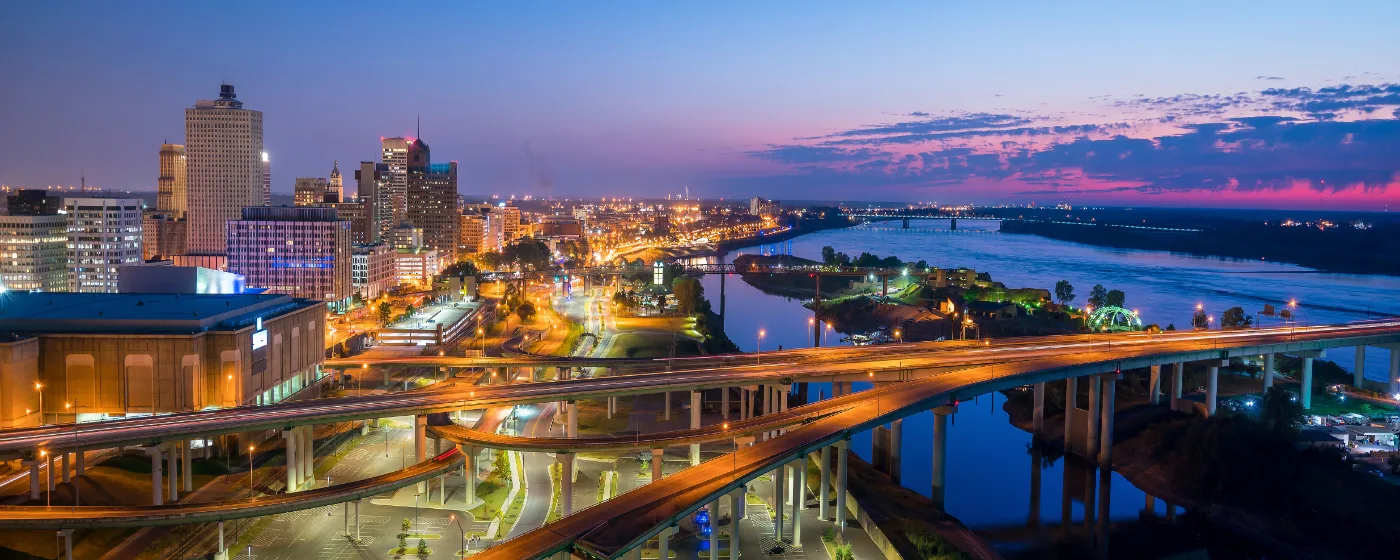
Memphis is one of the most genuinely affordable large cities left in the South, and that fact alone draws relocating buyers who've been priced out of Nashville or other higher-cost metros across the region. The typical home here — $145,335 as of August 2026 (Zillow Home Value Index) — sits well below what a comparable house would cost in any of the state's other major metros. That price point means a first-time buyer earning close to the city's median household income of $51,211 can realistically qualify for a mortgage without heroic sacrifices, which is increasingly rare anywhere in Tennessee. The city's employment base, anchored by FedEx's global headquarters, St. Jude Children's Research Hospital, AutoZone, and Methodist Le Bonheur Healthcare, keeps demand steady enough to support a functioning market without the frenzied multiple-offer environment that defines hotter cities.
What surprises most out-of-state buyers is how far that price goes in terms of square footage and lot size — and how much neighborhood selection matters here. Memphis is a city of distinct and sometimes sharply different areas. Getting that geography wrong costs first-time buyers real money, either by overpaying for a neighborhood that doesn't fit their life or by under-budgeting for the area they actually want. The Memphis neighborhoods guide covers those distinctions in full. The school picture also deserves honest attention: Memphis-Shelby County Schools holds a C+ rating, according to Niche, and many families research attendance zones before they pick a ZIP code.
The market itself is genuinely buyer-friendly by recent standards. Homes have been selling at roughly 2% below list price, and a significant share of active listings have already seen price reductions — meaning a prepared first-timer with a real pre-approval letter has negotiating leverage that simply doesn't exist in Nashville right now. Tennessee levies no state income tax on wages, which puts more of every paycheck toward a mortgage than buyers coming from states like Illinois or California typically expect. The effective property tax rate in Shelby County runs approximately 0.59% — above the Tennessee state average but noticeably below the national median. For a full picture of what things cost day-to-day, see the Memphis cost of living page.
Whether you've been renting in Midtown and are ready to stop, or you're relocating from out of state and doing your homework from afar, the sections below walk through what your budget actually buys in this market, the step-by-step process for buying locally, a budget snapshot table with realistic cash figures, and the specific mistakes that trip up first-timers in Memphis more than anywhere else.
The Memphis First-Time Buyer Reality
The headline number — a typical home price of $145,335 as of August 2026 — understates the range a first-time buyer actually encounters. The most attractively priced homes in areas like Whitehaven, Frayser, and Raleigh can sound genuinely accessible until you factor in the inspection results that older housing stock tends to produce. Deferred maintenance, aging HVAC systems, and roof conditions are common enough in that tier that budgeting only the purchase price is a fast road to buyer's remorse.
Step up toward the city's typical price range and the picture improves meaningfully. Midtown offers bungalows and older brick homes with genuine character — though competition from investors is real, because those homes also pencil as rentals. The practical entry point for a buyer who wants a house that doesn't need immediate work and sits in a neighborhood with stable values is closer to the city-wide typical price than to the absolute floor. For how specific neighborhoods compare on price, see the Memphis neighborhoods page.
The market's competitive character is worth understanding before you tour a single home. Memphis is described by current market data as somewhat competitive — not a war zone, but not a sleepy buyer's market either. Homes that are priced correctly move, and sellers of well-maintained properties in desirable ZIP codes are not desperate. Coming in without a pre-approval letter, or assuming you can lowball anything with a Memphis address, are both mistakes that cost first-timers offers they wanted. The leverage you do have — and it is real — comes from being prepared, moving decisively, and knowing which neighborhoods carry the most negotiating room.
The Homebuying Process in Memphis, Step by Step
Step 1: Get Pre-Approved Before You Do Anything Else
This is where most Memphis first-timers slip up first. Browsing Zillow for three months and then trying to get pre-approved the week you want to make an offer is a sequence that costs people houses here. A pre-approval letter from a lender — not a pre-qualification, which is softer and carries less weight — needs to be in hand before you contact an agent or walk through a door. Sellers and listing agents in Memphis treat unattached buyers as low-priority, and in a somewhat competitive market, low-priority means you lose.
Pull your credit reports before you apply. If anything looks wrong, dispute it before the lender runs your file — a hard inquiry on a thin or incorrect credit profile can hurt your rate. Most FHA lenders in Memphis want a minimum 580 score for the 3.5% down option; conventional lenders typically want 620 or higher, with better pricing above 740. Your debt-to-income ratio matters just as much as your score: total monthly debt payments (including the new mortgage) should generally stay under 43–45% of your gross monthly income.
Step 2: Find an Agent Who Knows the Neighborhoods
Memphis is a city where neighborhood knowledge is not optional. The difference between Frayser and Raleigh, or between the parts of Midtown that are appreciating and the parts that are stagnant, is not something a national search algorithm tells you. An experienced local buyer's agent earns their commission in this market by keeping you out of the wrong ZIP codes and into the right ones for your priorities.
Step 3: Shop, Make an Offer, Negotiate
With your pre-approval in hand and an agent beside you, the shopping process itself is relatively low-stress compared to hotter markets. Because homes here often sell below list price, your agent can model a realistic opening offer based on comparable sales rather than simply matching the ask. Build your offer around an inspection contingency and a financing contingency — both are standard in Memphis and neither should be waived on a first purchase.
Step 4: Inspection and Appraisal — Don't Rush Either
This is the second place first-timers go wrong. Memphis's housing stock skews older, and a general home inspection is not enough on its own. Sewer scopes are common sense on any house built before 1980 — older cast iron lines in Midtown and Whitehaven fail more often than buyers expect, and a sewer repair is not a small number. Your lender will order an independent appraisal; if the appraised value comes in below the purchase price, you have a decision to make, and you want your financing contingency intact when that happens.
Step 5: Closing
Tennessee closing costs for buyers typically run 2–3% of the purchase price, covering lender fees, title insurance, prepaid property taxes, homeowners insurance escrow setup, and attorney fees. In Shelby County, an attorney must be present at closing — this is not a title-company-only state. Budget conservatively and plan to bring a certified check or wire transfer; personal checks are not accepted. Closing day itself is usually 30–45 days after a signed contract.
How Much Home Can You Afford in Memphis
The table below gives a realistic look at what different price points and down payment scenarios actually require in cash at closing. Closing cost estimates use a conservative 3% of the purchase price, which reflects the typical range in Shelby County — your lender's Loan Estimate will give you the exact figure for your transaction. These are estimates; actual costs vary by lender, loan type, and negotiated seller concessions.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (3%) | Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5%) — entry-level | $120,000 | $4,200 (3.5%) | $3,600 | ~$7,800 |
| FHA (3.5%) — city typical | $145,000 | $5,075 (3.5%) | $4,350 | ~$9,425 |
| Conventional (3%) — city typical | $145,000 | $4,350 (3%) | $4,350 | ~$8,700 |
| FHA (3.5%) — move-in ready | $165,000 | $5,775 (3.5%) | $4,950 | ~$10,725 |
| Conventional (5%) — above city median | $190,000 | $9,500 (5%) | $5,700 | ~$15,200 |
| Conventional (10%) — stronger equity start | $165,000 | $16,500 (10%) | $4,950 | ~$21,450 |
A few things this table can't show: FHA loans require an upfront mortgage insurance premium (typically 1.75% of the loan amount, often rolled into the loan) and monthly mortgage insurance that stays until you refinance or reach sufficient equity. Conventional loans with less than 20% down also carry private mortgage insurance, but it falls off automatically once you hit 20% equity — a meaningful long-term difference at Memphis price points. The interactive calculator below lets you run your own numbers with current rates and an exact purchase price.
One budget advantage specific to Tennessee: no state income tax on wages means your take-home pay goes further than it does in most states, and lenders see that full gross income when calculating how much you qualify for. Tennessee also offers a Mortgage Credit Certificate that allows qualifying buyers to claim a federal tax credit of up to $2,000 per year on paid mortgage interest — worth asking your lender about before you close.
Looking to buy in Memphis? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Memphis quote.
Beyond the Monthly Mortgage Payment — What to Factor In
- The property tax rate above — The 0.59% used in the estimate is the median effective rate — tax actually paid as a share of market value — published by Ownwell, 2026. Half of local homes pay more and half pay less: your own bill depends on that property's assessed value and any exemptions it qualifies for, which can differ a lot from its market price. Confirm with the Shelby County assessor before you budget.
- Total cost of ownership — Your monthly mortgage payment is just the baseline. Depending on the specific city, county, and service district, homeownership costs also include local utility fees, municipal surcharges, and special assessments (such as water, sewer, storm drainage, or local energy taxes) that vary by location.
- Independent due diligence — Because these recurring local costs and municipal fees change depending on the exact property address, buyers must research them independently during their transaction process.
Tax laws, local municipal fees, and utility costs change frequently and individual situations vary. This page is general information, not tax or legal advice — always consult a qualified tax professional, CPA, or local municipal offices for personalized guidance.
Common First-Time Buyer Mistakes in Memphis
Shopping Without a Pre-Approval Letter
It happens constantly. A buyer spends two months falling in love with houses on the internet, contacts a seller's agent, and discovers their credit profile or debt-to-income ratio needs work before any lender will commit. Memphis's investor-heavy market means well-priced houses in Midtown and Whitehaven can move before a scrambling buyer gets their paperwork together. Pre-approval is not a formality — it is the starting line.
Waiving the Inspection Contingency to Compete
In hotter markets, buyers sometimes waive inspections to win bidding wars. Memphis is not that market. Homes here often sell below list price and negotiate down — there is almost no scenario where a first-time buyer should close on a Memphis house without a full general inspection and, on older properties, a sewer scope. The houses most likely to tempt a waiver — priced attractively in Frayser or older Whitehaven stock — are precisely the ones with the highest likelihood of expensive surprises underneath.
Ignoring School Attendance Boundaries Until After the Offer
Memphis-Shelby County Schools attendance zones do not follow neighborhood names neatly, and they matter to resale value even for buyers who don't have children yet. Two houses on adjacent streets can feed into different schools. Look up the specific address in the district's zone finder before you fall in love with a house — not after your offer is accepted. Buyers planning families should see the full picture on the Memphis schools page before narrowing their search area.
Underbudgeting the Cash Needed to Close
The down payment is the number buyers focus on; closing costs are the number that blindsides them. In Shelby County, attorney fees are mandatory — Tennessee requires an attorney at closing, not just a title company — and that's before lender origination fees, prepaid homeowners insurance, property tax escrow, and title insurance. Budget 3% of the purchase price for closing costs as a floor, not a ceiling. If you're counting on seller concessions to cover part of that, build it into your offer strategy upfront rather than hoping for it after the fact. Many first-time buyers also forget to reserve cash for immediate post-closing needs: a new HVAC filter, a locksmith to re-key the locks, or minor repairs the inspection flagged but the seller declined to fix.
Treating Neighboring Suburbs as Interchangeable with Memphis
Germantown, Collierville, and Bartlett all carry typical home prices noticeably higher than Memphis's $145,335 (August 2026) city-wide figure. Buyers who stretch to afford a Memphis house and then realize they actually wanted the Germantown school district are starting over with a budget that doesn't fit the market they've chosen. Make the suburb-versus-city decision before pre-approval, not after — your loan amount, your down payment target, and your neighborhood shortlist all follow from it.
Local Expert Takeaway: Memphis is one of the few large Southern cities where a buyer with a solid pre-approval and a realistic budget can still find a move-in-ready house at or near the city-wide typical price — but the market rewards preparation, not improvisation. Get pre-approved before you tour, insist on a full inspection regardless of competition, and do your school-zone homework by address before you fall for a house. The neighborhoods where first-time buyers tend to do well — parts of Midtown, Raleigh, and areas closer to the city-wide price level — reward buyers who understand what they're getting and go in with their eyes open.
Quick Takeaways & FAQs
✅ Memphis's typical home price of $145,335 (August 2026) makes it one of the most accessible large-city markets in Tennessee, with realistic entry points well below the city median.
⚠️ Older housing stock throughout Midtown, Whitehaven, and Frayser means a sewer scope and thorough inspection are non-negotiable — the houses priced most attractively carry the most hidden-cost risk.
📍 Tennessee has no state income tax on wages, which stretches a first-time buyer's qualifying income further here than in most states — a real budget advantage that often surprises out-of-state relocators.
What credit score do I need to buy a home in Memphis?
How much money do I actually need to buy a house in Memphis?
Is Memphis a buyer's market or a seller's market right now?
Do I need an attorney to buy a house in Memphis?
Are there Memphis neighborhoods where first-time buyers get the most for their money?
Moving to Tennessee?
Tell us what you need help with and we'll connect you with local resources.
