Wilsonville is the kind of Portland-area suburb that draws first-time buyers for sensible reasons — about 25 minutes to Portland, a highly rated school district, a walkable village core at Villebois, and a genuine small-city feel at a population of 27,341. The catch is equally sensible: this is not a starter-home market in the traditional sense. The typical home here costs $630,814 (Zillow Home Value Index, July 2026), and the gap between that figure and what a median-income household can actually carry is real and worth understanding before you start touring open houses.
The city sits along I-5 in Clackamas County at the southern edge of the Portland metro, where the suburbs give way to Willamette Valley farmland. That position makes it appealing to buyers who want metro access without metro density, and to households with jobs at Sysco, Siemens EDA, or Rockwell Collins — three of the city's major private employers. The West Linn-Wilsonville School District holds an A rating, according to Niche, which adds meaningful pull for parents with school-age children weighing this market against Tualatin or Sherwood.
On cost, Wilsonville sits roughly in the same range as Tualatin and Sherwood, and noticeably above Canby — so buyers who cannot make the numbers work here sometimes find more room to the south. The city's 2019 decision to build Villebois as a New Urbanist village, combined with townhome and condo inventory in Frog Pond, has created a real (if limited) entry tier below the single-family median. Rental alternatives run $1,610–$1,960 for a two-bedroom, which helps buyers who want to keep renting while they save — but the math on accumulating a down payment in this market demands a plan.
Whether you are setting a budget for the first time or have a pre-approval letter in hand and are ready to tour, the sections below walk through what the Wilsonville market actually costs, how the buying process works here step by step, what the numbers look like at the table, and the specific mistakes that catch first-timers off guard in this city.
The Wilsonville First-Time Buyer Reality
The headline number is $630,814 — the typical Wilsonville home price as of July 2026 (Zillow Home Value Index). That figure sits above what the city's median household income of $96,236 can comfortably carry, which means most first-time buyers here are either bringing meaningful savings, receiving family support, or adjusting their product type. This is not a market where you drift in with 3% down and expect to compete on a detached single-family home without a financial plan behind you.
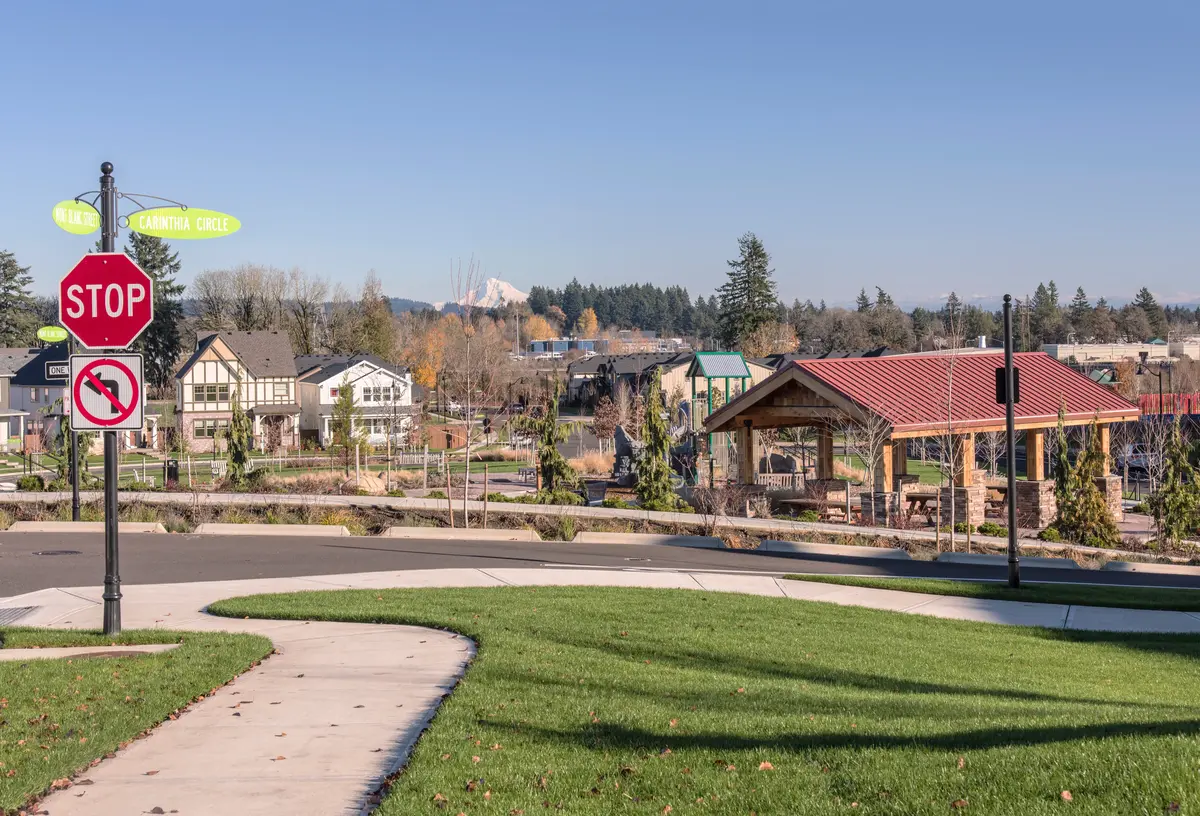
Entry-level single-family homes rarely surface below $500,000 in Wilsonville. When they do, they tend to need work, or they are attached products marketed as detached. The more realistic entry point for first-timers is townhomes and condos — particularly in Villebois and Frog Pond, where the New Urbanist design philosophy produced a denser, somewhat more accessible housing stock than the rest of the city. These are not budget properties, but they are where the floor of the market actually lives for buyers without a substantial equity transfer from a prior sale. For a deeper look at what different neighborhoods offer in terms of character and housing type, see the best neighborhoods guide.
The competitive reality is measured, not frenzied. Well-priced homes move — expect a prepared offer to matter more than speed alone, though both count. The days of waiving everything to compete are largely behind this market, but sellers in Wilsonville are still accustomed to receiving clean offers with strong pre-approvals attached. Buyers who arrive without that documentation in hand are not starting the process — they are delaying it.
The Homebuying Process in Wilsonville, Step by Step
Step 1: Get Pre-Approved — Before You Tour Anything
In Oregon's suburban markets, a pre-approval letter is not a courtesy — it is a requirement. Sellers here will not seriously consider an offer without one attached, and listing agents sometimes decline to schedule tours without proof of financing in hand. A pre-approval is meaningfully stronger than a pre-qualification: it involves a credit pull, verified income documentation, and a lender's actual underwriting review, not just a basic estimate of what you might borrow.
Choose your lender before you choose your agent, and get the letter before you step into a single open house. A pre-approval also sets a hard ceiling on your search, which saves everyone time — including yours.
Step 2: Assemble Your Team and Define Your Search
Once pre-approved, find a buyer's agent with active experience in Wilsonville and the southern Portland metro. This market has specific neighborhood dynamics — the difference between Villebois, Charbonneau, and Frog Pond is not just aesthetic — and an agent who works it regularly will know when a price is fair, when a listing has been sitting, and when a multiple-offer situation is brewing. Define your non-negotiables early: product type, minimum square footage, proximity to the WES commuter rail station if that matters for your commute.
Step 3: Make an Offer
When you find a property, move deliberately but without unnecessary delay. Well-priced homes in Wilsonville do not sit indefinitely. Your offer should include your pre-approval letter, a reasonable earnest money deposit, and clear contingency language — particularly for inspection and financing. Resist pressure to waive contingencies entirely on your first purchase; the inspection contingency in particular exists to protect buyers who have never owned a home before and have no baseline for what a home's systems should look like.
Step 4: Inspection, Appraisal, and Underwriting
The inspection period is where first-timers most often make one of two mistakes: they either panic over normal findings and walk away from a solid home, or they dismiss concerns that deserve negotiation. A general home inspection is the floor, not the ceiling — in the Portland area, it is worth considering a sewer scope on older homes, which can surface lateral-line issues that a standard inspector will flag but not investigate. Your lender will order an appraisal independently; if the appraisal comes in below your purchase price, you will need to negotiate with the seller, cover the gap in cash, or walk away.
During underwriting, do not change anything about your financial picture. No new credit cards, no large deposits without a paper trail, no job changes. Lenders re-verify employment and credit shortly before closing, and a change that looks minor to you can pause or end the transaction.
Step 5: Closing
Oregon closings are handled by an escrow/title company, not in a lawyer's office. You will sign a substantial package of documents — typically in person, though remote online notarization is increasingly available — and bring your closing funds via wire transfer or certified check. Budget three to five business days for the wire to be confirmed and the deed to record. Once it records, you own the home.
How Much Home Can You Afford in Wilsonville
Oregon closing costs for buyers typically run 2% to 5% of the purchase price, covering loan origination, the appraisal, title insurance, prepaid homeowners insurance, and escrow fees. That range is wide because it depends on your lender, your loan type, and whether you negotiate seller concessions toward costs. Budget toward the middle of that range unless your lender gives you a specific Loan Estimate early in the process.
The table below shows cash-needed estimates at several realistic price points in Wilsonville. These are approximations — your actual figures will come from your Loan Estimate — but they give you an honest starting point for how much cash you need before you can close.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (3%) | Est. Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5% down) — entry condo/townhome | $490,000 | $17,150 (3.5%) | ~$14,700 | ~$31,850 |
| Conventional (3% down) — entry condo/townhome | $490,000 | $14,700 (3%) | ~$14,700 | ~$29,400 |
| FHA (3.5% down) — lower mid-range | $550,000 | $19,250 (3.5%) | ~$16,500 | ~$35,750 |
| Conventional (5% down) — lower mid-range | $550,000 | $27,500 (5%) | ~$16,500 | ~$44,000 |
| Conventional (10% down) — near city median | $630,000 | $63,000 (10%) | ~$18,900 | ~$81,900 |
| Conventional (20% down) — near city median | $630,000 | $126,000 (20%) | ~$18,900 | ~$144,900 |
The 20% scenario avoids private mortgage insurance (PMI), which meaningfully reduces your ongoing monthly cost. The interactive mortgage calculator below lets you run current-rate estimates for any of these scenarios — the table above covers only the cash you need at closing, not the monthly payment picture.
One planning note: the city's effective property tax rate is approximately 0.96%, which is a factor in your monthly payment calculation — see the full cost-of-living breakdown for how taxes compare across the area.
Looking to buy in Wilsonville? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Wilsonville quote.
Common First-Time Buyer Mistakes in Wilsonville
Shopping Before You Have a Pre-Approval
This is the single most common mistake, and it costs buyers in two ways. First, you may tour — and fall for — a home you cannot actually buy under the terms the seller will accept. Second, Wilsonville listing agents talk to each other, and arriving at a showing without documentation signals that you are not ready to transact. Get the letter first. Touring is not a low-stakes activity here.
Waiving the Inspection Contingency to Win an Offer
In the peak competition years of 2021–2023, waiving inspections became almost routine in this metro. That pressure has eased, and most well-advised sellers in Wilsonville today are not requiring a full waiver to accept an offer. Waiving the contingency entirely on your first purchase — on a home you have never owned and a market you do not yet know — is an asymmetric risk. If the home has a compromised roof, a failing sewer lateral, or an unpermitted addition, you inherit those costs without recourse. An inspection is not negotiable for first-timers.
Ignoring the School Boundary Reality
Wilsonville sits in the West Linn-Wilsonville School District, which holds an A rating, according to Niche, and draws families who want that academic environment. What buyers sometimes do not check until after they are under contract is which specific school a given address feeds into — and whether that school is the one they assumed. The district's attendance boundaries do not perfectly follow neighborhood lines. Check the specific address before you make an offer, not after. More detail on the district is on the schools page.
Underbudgeting the Cash Needed at Closing
First-timers often focus on saving the down payment and treat closing costs as a secondary concern. At Wilsonville price points, a 3% closing cost estimate on a $550,000 home is $16,500 — real money that needs to be liquid at the same time as your down payment. If you are also paying first and last month's rent while your current lease winds down, the cash demand in the weeks around closing can be genuinely stressful. Build a closing-cost line into your savings plan from the beginning, not as an afterthought in the final month.
Changing Your Financial Picture Between Pre-Approval and Closing
Oregon lenders re-verify credit and employment shortly before the closing date. A new car loan, a large unexplained deposit, or a job change — even a lateral move to a better salary — can trigger additional underwriting scrutiny or delay closing entirely. The period between pre-approval and the recording of your deed is not the time to make financial moves, however sensible they might seem in isolation. Stay still financially until the keys are in your hand.
Local Expert Takeaway: Wilsonville rewards first-time buyers who do the preparation work before they start touring. The entry tier is real — townhomes and condos in Villebois and Frog Pond give buyers a foothold that the single-family market does not — but it requires a pre-approval in hand, a clear-eyed cash budget that includes closing costs alongside the down payment, and a willingness to move when the right home surfaces. Buyers who arrive pre-approved, keep their finances stable through underwriting, and do not skip the inspection tend to close without drama. The ones who don't are usually caught by one of those three things.
Quick Takeaways & FAQs
✅ The West Linn-Wilsonville School District holds an A rating, according to Niche — one of the stronger draws for families choosing this market over nearby Tualatin or Canby.
⚠️ The typical home price of $630,814 (Zillow Home Value Index, July 2026) sits above what the city's median household income can comfortably support, so first-time buyers need a realistic cash plan before they start shopping.
📍 Townhomes and condos in Villebois and Frog Pond are where the practical entry tier exists — single-family homes below $500,000 in Wilsonville are rare and move fast when they appear.
What is the minimum down payment to buy a home in Wilsonville?
How competitive is the Wilsonville housing market for first-time buyers?
Are there townhomes or condos in Wilsonville that are more affordable for first-time buyers?
What are closing costs for a home purchase in Wilsonville, Oregon?
Do I need a pre-approval letter before touring homes in Wilsonville?
Moving to Oregon?
Tell us what you need help with and we'll connect you with local resources.
