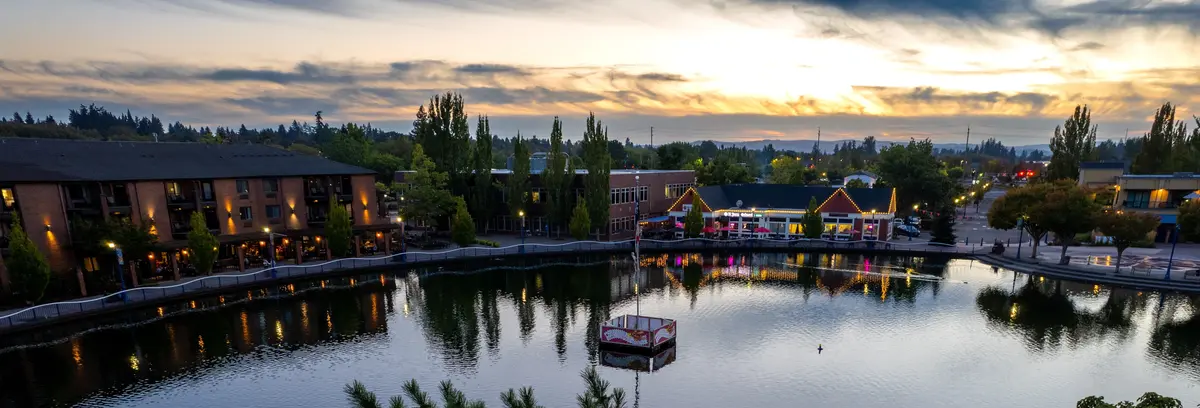
Maybe someone told you Tualatin was the affordable alternative to Lake Oswego or West Linn. That framing is partly right and worth unpacking before you start touring open houses. The typical home in Tualatin sits at $635,314 as of July 2026 — well above what most households expect when they hear the word "suburb," and above what the median household income here can comfortably carry without a significant down payment. The city of 27,763 is compact, connected to Portland by I-5, and priced at a level that rewards buyers who show up prepared.
What draws first-time buyers to Tualatin is real: the Tigard-Tualatin School District holds a B+ rating on Niche, employers like Lam Research anchor a stable local job base, and the commute runs about 25 minutes to Portland on most days. Bridgeport Village and the Tualatin Commons give the city a walkable center that many neighboring suburbs lack. The buyer pool here skews toward working households and dual-income couples who have spent a year or two saving and are serious when they make an offer.
For first-timers, the core challenge is cash at the table. Oregon closing costs typically run 2% to 5% of the purchase price, and at Tualatin prices that adds up fast on top of a down payment. The good news is that this is not a market where every well-priced home disappears in 48 hours — buyers who come in with full documentation, a clear budget ceiling, and a pre-approval letter in hand are competitive without needing to waive every protection.
Whether you are weighing your first offer or still figuring out how much to save, the sections below walk through what the Tualatin market actually costs, how the buying process works locally, how to build a realistic budget snapshot, and the specific mistakes that set first-timers back most often here.
The Tualatin First-Time Buyer Reality
The typical home price in Tualatin is $635,314 as of July 2026 (Zillow Home Value Index). That figure puts entry-level homeownership above what most first-time buyers picture when they imagine a Portland-area suburb — and it sits at a level that requires meaningful savings for both a down payment and closing costs before you can compete. That gap between aspiration and cash-on-hand is the central planning challenge for any first-timer in this market.
What does that price actually buy? Condos, townhomes, and smaller single-family homes — including options in areas like Tualatin Village and near Hedges Creek — represent the more accessible end of the local inventory. Detached single-family homes in established neighborhoods like Fox Hill or Victoria Woods tend to draw serious interest from move-up buyers as well as first-timers, which keeps pricing firm. Move-in-ready properties consistently attract stronger interest here, while homes with deferred maintenance have more room for negotiation. For buyers on a tight budget, condition is a real filter: a fixer at a lower sticker price can cost more in the end if you are also financing the repairs.
Well-priced, well-maintained homes in Tualatin rarely sit. First-timers who arrive pre-approved, understand the neighborhood they want, and have their documentation in order are the ones who close. Those who shop first and figure out financing later tend to lose the homes they want to buyers who did the work ahead of time. For a full picture of what homes look like across different parts of the city, the neighborhoods guide breaks down character and housing stock by area.
The Homebuying Process in Tualatin, Step by Step
Step 1: Check and Clean Up Your Credit First
Before you contact a lender, pull your credit report. Addressing errors or high utilization balances is the highest-leverage move most first-time buyers skip entirely. A difference of 20 to 40 points in your credit score can meaningfully change the rate you are offered at these price levels — and at $600,000-plus, that spread matters.
Step 2: Get Pre-Approved — Not Just Pre-Qualified
Pre-qualification is an estimate based on what you tell a lender. Pre-approval means the lender has actually verified your income, assets, credit, and debt, and issues a letter stating the maximum they will lend. In Tualatin, a pre-approval letter is treated as a near-requirement before agents will show homes and before sellers will seriously consider an offer. Bring recent pay stubs and W-2s, two years of tax returns, bank and asset statements, a list of debts, and a government-issued ID.
Pre-approval is not a commitment to borrow the full amount — it is a ceiling. Most experienced buyers set their shopping range noticeably below their approval ceiling to leave room for closing costs and reserves.
Step 3: Shop With a Clear Budget Ceiling
Once you know your number, tour homes in that range and slightly below — not at the top of it. Move-in-ready properties in Tualatin attract multiple serious buyers; homes with deferred maintenance, while sometimes priced lower, can drain a first-timer's reserves faster than expected. Know what you are willing to take on before you make an offer on a project.
Step 4: Make a Competitive Offer
A competitive offer in Tualatin is not just about price. It means being pre-approved (not pre-qualified), having your earnest money ready, and writing clean offer terms. Requests for seller-paid closing costs have become more common again as buyers have gained a bit of leverage on homes that sit — but on a well-priced, move-in-ready home, those requests may cost you the deal. Your agent will read the specific situation.
Step 5: Inspection and Appraisal — Don't Skip Either
The home inspection is the step first-timers most often feel pressure to waive in a competitive offer. Don't — or if you do, understand exactly what you are giving up. An inspection surfaces deferred maintenance, roof condition, HVAC age, and plumbing issues that are not visible on a showing. An appraisal protects you from paying more than the home is worth to the lender. Both are protections, not formalities, and both belong in your offer unless you are prepared to absorb the financial consequences of waiving them.
Step 6: Clear Conditions and Close
Once your offer is accepted, your lender will work through underwriting while you satisfy any remaining conditions. Budget several weeks for this phase. Closing costs in Oregon typically run 2% to 5% of the purchase price — have that cash ready in addition to your down payment, because it cannot be rolled into most loan types at this stage.
How Much Home Can You Afford in Tualatin
The table below shows estimated cash requirements at closing for several realistic entry points in Tualatin. Down payments are based on minimum program requirements; closing costs use the Oregon range of 2% to 5% of the purchase price and are shown as a range. These are estimates — your actual costs will vary based on lender, loan terms, and negotiated concessions. The interactive calculator below the table lets you model monthly payments at current rates.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs | Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5%) — entry condo/townhome | $450,000 | $15,750 (3.5%) | $9,000–$22,500 | ~$25,000–$38,000 |
| Conventional (3%) — entry condo/townhome | $450,000 | $13,500 (3%) | $9,000–$22,500 | ~$23,000–$36,000 |
| FHA (3.5%) — city-wide typical home | $635,000 | $22,225 (3.5%) | $12,700–$31,750 | ~$35,000–$54,000 |
| Conventional (3%) — city-wide typical home | $635,000 | $19,050 (3%) | $12,700–$31,750 | ~$32,000–$51,000 |
| Conventional (10%) — mid-range single-family | $650,000 | $65,000 (10%) | $13,000–$32,500 | ~$78,000–$98,000 |
| Conventional (20%) — mid-range single-family | $650,000 | $130,000 (20%) | $13,000–$32,500 | ~$143,000–$163,000 |
All figures are estimates based on Oregon-standard closing cost ranges and minimum program down payments. Actual costs depend on your lender, rate, and transaction specifics.
One planning tool worth knowing: Oregon offers a First-Time Home Buyer Savings Account through the Oregon Department of Revenue. Individual account holders may deduct up to $6,285 per year (up to $12,570 for joint filers) from Oregon taxable income on deposits, for a maximum of $50,000 over 10 years. Accounts must be opened by December 31, 2026, and funds must be used to purchase a qualifying single-family home in Oregon. If you are 12 to 24 months from buying, this account can meaningfully reduce your tax bill while you save.
Looking to buy in Tualatin? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Tualatin quote.
Common First-Time Buyer Mistakes in Tualatin
Shopping Before You Have a Pre-Approval Letter
This is the most common and most costly mistake in this market. Touring homes without a verified pre-approval letter means you cannot make a serious offer when something you love hits the market. It also means you may fall for a home that is outside your actual borrowing range — which makes everything else feel like a compromise. Get the letter first. Pre-qualification does not count; sellers here know the difference.
Waiving the Inspection on a Move-In-Ready Home
Move-in-ready properties in Tualatin attract competitive offers, and first-timers sometimes feel pressure to waive the inspection to win. The impulse is understandable; the outcome is often expensive. Tualatin's housing stock includes a mix of 1970s and 1980s construction alongside newer builds, and older homes can carry issues — aging systems, drainage concerns near the river greenway, moisture in crawl spaces — that are invisible on a showing. If you feel you must compete on inspection terms, negotiate a shortened review period rather than waiving it entirely.
Ignoring the School Boundary and Commute Reality
Tualatin sits in the Tigard-Tualatin School District 23J, but individual school boundaries matter, and they do not always align with the neighborhood you expect. A home in one part of the city may feed into a different elementary school than a home two blocks away. Check the specific boundary before you make an offer — not after. Similarly, the I-5 commute to Portland runs about 25 minutes in off-peak hours and considerably longer during morning rush. If your job is not near the freeway corridor, factor that in before you anchor to a neighborhood based on price alone. The schools page and the living in Tualatin guide cover both in more detail.
Underestimating the Cash You Need at the Table
First-timers consistently undercount closing costs. Oregon buyer closing costs run 2% to 5% of the purchase price, and at Tualatin's price levels that can mean $13,000 to $32,000 on top of your down payment. Many first-timers budget for the down payment and then find themselves short when the closing disclosure arrives. Your pre-approval should tell you the loan amount you qualify for — it does not automatically account for cash reserves. Budget for down payment, closing costs, and a post-close reserve separately, and make sure all three are funded before you start making offers.
Treating Pre-Approval as Your Shopping Ceiling
Lenders approve you for the maximum you qualify for — not the maximum you should spend. In Tualatin, where the typical home price is already above what most households can comfortably carry, buying at the very top of your approval leaves almost no cushion for property tax, maintenance, or an unexpected repair in year one. Most buyers here who feel stretched in their first two years of ownership bought at or above 95% of their approval ceiling. Set your shopping range, then stick to it even when a home at the edge of your limit looks perfect.
Local Expert Takeaway: Tualatin rewards first-time buyers who treat the process like a job before it becomes a house hunt. Pull your credit report, build your savings toward both a down payment and closing costs, and get a real pre-approval letter — not a pre-qualification — before you set foot in an open house at Bridgeport Village or schedule a showing in Fox Hill. The buyers who lose homes here are almost never outbid by a huge margin; they lose because they were not ready when something right came available. At these price levels, that preparation gap is expensive.
Quick Takeaways & FAQs
✅ Tualatin's commute runs about 25 minutes to Portland via I-5, making it a genuinely practical base for Portland-area workers who want more space than the city offers.
⚠️ The typical home price of $635,314 (July 2026) means first-timers need to budget carefully for both down payment and Oregon closing costs, which can add $13,000 to $32,000 on top of the down payment at local price levels.
📍 Oregon's First-Time Home Buyer Savings Account lets individual filers deduct up to $6,285 per year in deposits from state taxable income — a concrete planning tool if your purchase is 12 to 24 months out.
What credit score do I need to buy a home in Tualatin, Oregon?
How much do I need to save before buying a home in Tualatin?
Is Tualatin a competitive market for first-time buyers?
What is the difference between pre-approval and pre-qualification in Oregon?
Can I still qualify as a first-time buyer in Oregon if I owned a home years ago?
Moving to Oregon?
Tell us what you need help with and we'll connect you with local resources.
