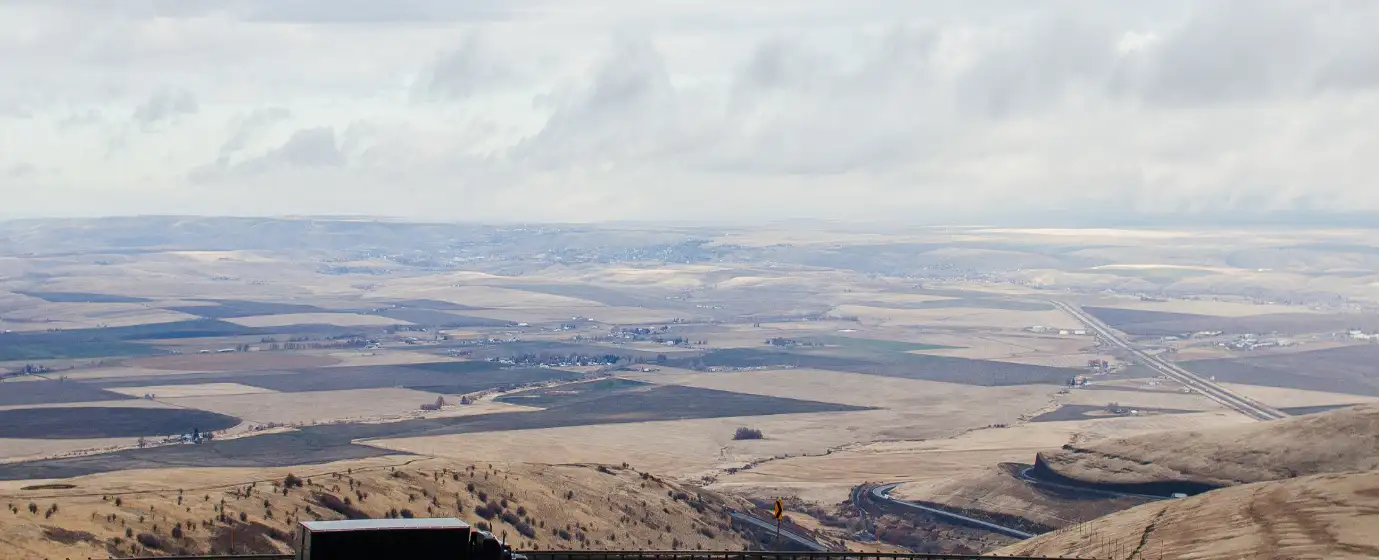
Pendleton doesn't behave like the rest of Oregon's housing market, and that works heavily in your favor if you're buying for the first time. While buyers in Portland and Bend were routinely waiving inspections and writing letters to sellers a few years ago, the market here — anchored by stable public-sector employment and a city of 16,950 people in Eastern Oregon's high desert — has always moved at a more measured pace. The city sits along I-84, roughly equidistant between Portland to the west and Boise to the east, and its housing inventory reflects that geography: older craftsman and ranch-style homes, a modest but real supply of move-in-ready stock, and prices that are a fraction of what you'd pay west of the Cascades.
The economic foundation here is unusually durable for a city this size. The Confederated Tribes of the Umatilla Indian Reservation, Umatilla County government, Pendleton School District, Blue Mountain Community College, and a regional health system collectively provide the kind of stable, place-anchored employment that insulates local real estate from the boom-bust cycles that rattle markets dependent on a single private-sector industry. That stability matters to a first-time buyer: the value of the home you're buying is partly a function of the economic health of the people around you, and Pendleton's fundamentals are solid. The Pendleton School District holds a B- rating, according to Niche, which you can dig into further on the schools page.
For a first-timer weighing renting against buying, the math in Pendleton is unusually clear. The cost of living page has the full breakdown, but the short version is that home prices here sit well below Oregon's coastal and metro markets, making a monthly mortgage payment genuinely competitive with local rent — and building equity in the process. The city averages 195 sunny days a year, outdoor access along the Umatilla River Parkway is walkable from most neighborhoods, and commutes inside city limits average well under 20 minutes, which frees up real time in your day.
Whether you've been renting in Pendleton for years and finally feel ready, or you're relocating from somewhere larger and want to understand what the local buying process actually looks like, the sections below walk through what your budget buys here, how the purchase process works step by step, a concrete budget table to stress-test your numbers, and the specific mistakes that trip up first-timers in this market.
The Pendleton First-Time Buyer Reality
The typical home price in Pendleton is $304,381 (Zillow Home Value Index, July 2026). That number is not a misprint, and it is not a reflection of declining quality — it reflects Eastern Oregon's cost structure, where land is abundant and construction history predates the coastal price run-up. For a first-time buyer who has spent any time researching Oregon real estate, this figure lands differently than you might expect.
What that price range actually buys you: three-bedroom, two-bath homes with functional layouts, established yards, and in many cases original hardwood floors and built-in character that newer construction can't replicate. A meaningful portion of Pendleton's inventory consists of homes built before 1990, which means you're not typically looking at new builds with fresh warranties — you're looking at homes that have a history, and a good inspection will tell you what that history cost the structure. Entry-level homes, meaning smaller square footage or properties needing cosmetic updates, are available below the city median. Well-maintained homes in neighborhoods like Sunridge Estates or Grecian Heights sit above it. The neighborhoods page walks through the character of each area in detail.
The competitive dynamics here genuinely favor a first-timer. Homes in Pendleton give buyers time to sleep on an offer, schedule a second walkthrough, or wait for the right property rather than the first available one. Recent sold data shows homes frequently closing at or slightly below list price. That is not a buyer's market in the dramatic sense, but it is meaningfully different from the pressure you'd face in Bend or Portland, and it means you can approach the process deliberately rather than reactively.
The Homebuying Process in Pendleton, Step by Step
Step 1: Get Pre-Approved Before You Look at a Single House
This is not a formality in Pendleton — it's the filter that tells you whether you're shopping for a $220,000 home or a $350,000 home, which in this market are genuinely different product classes. Sellers here will not take an offer seriously without a pre-approval letter, and in a market where inventory is real but not unlimited, losing a well-priced home because your letter wasn't ready is an avoidable mistake.
Pre-approval requires two years of tax returns, recent pay stubs, bank statements, and a credit pull. It typically takes a few business days with a lender who knows the Oregon market. FHA loans — which require as little as 3.5% down and carry flexible qualification guidelines — are one of the most common paths for first-timers here, and the 2026 FHA loan limit for a single-family home in Oregon starts at $541,287, comfortably above Pendleton's typical price point. Conventional loans with 3% or 5% down are also available if your credit profile supports them.
Step 2: Tour Properties with a Local Agent
A buyer's agent costs you nothing directly — the seller pays the commission structure — and a local agent knows which streets run quiet, which neighborhoods flood after a hard rain, and which listings have been sitting because of a structural issue versus a pricing mismatch. In Pendleton, that knowledge matters more than it would in a city with a more homogeneous housing stock.
Step 3: Write a Clean Offer
Earnest money deposits in Umatilla County typically run $1,000–$3,000. On a competitive listing, the upper end of that range signals you're serious without overcommitting cash you'll need elsewhere. Your offer will include a purchase price, earnest money amount, contingencies (inspection, financing, appraisal), and a proposed closing date. Closing timelines in Pendleton average 30–45 days from accepted offer.
Step 4: Inspection and Appraisal — Do Not Skip Either
With a significant share of Pendleton's inventory consisting of pre-1990 construction, the inspection is the most consequential step in your purchase. Older homes here can carry deferred maintenance on roofs, plumbing, and electrical that isn't visible in a showing. Buyers in this market are not routinely waiving inspections — and that norm exists for a reason. If a seller is pressuring you to waive it on a 40-year-old house, that pressure itself is information.
The appraisal is ordered by your lender and confirms the home's value supports the loan amount. If the appraised value comes in below your offer price, you'll need to negotiate with the seller, cover the gap in cash, or walk away. Oregon buyer closing costs typically run 2%–5% of the purchase price, covering loan origination fees, title insurance, appraisal, and the inspection — earnest money paid upfront is credited against this total at closing.
Step 5: Closing
At closing, you sign the loan documents, wire your down payment and remaining closing costs, and receive the keys. The process typically happens at a title company. Oregon is a dry-funding state, meaning the lender releases funds after documents are signed and reviewed — your agent will walk you through the exact timing. Budget the full 30–45 days and don't schedule a moving truck for the day of signing.
How Much Home Can You Afford in Pendleton
The table below stress-tests common first-time buyer scenarios against Pendleton's price range. Closing costs are estimated at approximately 2%–5% of the purchase price — use the midpoint (3%) as a working figure, and ask your lender for a Loan Estimate early in the process since the exact figure varies by loan type and lender. Earnest money paid upfront is credited back at closing, so it reduces the total cash you'll owe on closing day. The interactive mortgage calculator below this section will calculate estimated monthly payments at current rates once you enter your specifics.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (3%) | Est. Cash Needed at Table |
|---|---|---|---|---|
| FHA — 3.5% down, entry-level | $220,000 | $7,700 (3.5%) | ~$6,600 | ~$14,300 |
| FHA — 3.5% down, near median | $304,000 | $10,640 (3.5%) | ~$9,120 | ~$19,760 |
| Conventional — 3% down, entry-level | $220,000 | $6,600 (3%) | ~$6,600 | ~$13,200 |
| Conventional — 5% down, near median | $304,000 | $15,200 (5%) | ~$9,120 | ~$24,320 |
| Conventional — 10% down, above median | $360,000 | $36,000 (10%) | ~$10,800 | ~$46,800 |
| Conventional — 20% down, above median | $360,000 | $72,000 (20%) | ~$10,800 | ~$82,800 |
A 20% down payment eliminates private mortgage insurance (PMI) on a conventional loan, which meaningfully reduces your monthly payment — but it requires substantially more cash at the table. Most first-time buyers in Pendleton are entering the market with 3%–5% down and budgeting for PMI as a short-term cost until they've built equity. If you're looking at older homes and want to bundle purchase and renovation costs into a single loan, ask your lender about FHA 203(k) renovation financing — it's designed exactly for the kind of pre-1990 stock that makes up a real share of Pendleton's inventory.
Looking to buy in Pendleton? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Pendleton quote.
Common First-Time Buyer Mistakes in Pendleton
Shopping Before Pre-Approval
Touring homes before you have a pre-approval letter is one of the most common mistakes first-time buyers make here. In a market where the right property at the right price doesn't sit forever, showing up to a seller without a letter means someone else — who did the paperwork — takes the house while you're still talking to a lender. Get the letter first, then go look at houses.
Waiving the Inspection on Older Inventory
Pendleton's housing stock skews older. A home that shows well in a weekend viewing can carry a roof with two seasons left, an electrical panel that needs upgrading, or plumbing that hasn't been touched since the Nixon administration. Buyers in this market are not waiving inspections as a rule, and you shouldn't either. The inspection contingency is not a negotiating chip — it's the mechanism by which you learn what you're actually buying before you're legally obligated to buy it.
Underestimating the Cash Needed at Closing
First-time buyers consistently underbudget closing costs. The down payment is what they plan for; the 2%–5% in closing costs is what catches them off-guard two weeks before the closing date. On a $304,000 purchase, that's roughly $6,000–$15,000 on top of your down payment — money that needs to be liquid and in your account before closing day. Start saving for both at the same time, not sequentially.
Ignoring School Boundaries If Kids Are Part of the Plan
The Pendleton School District serves the whole city, but individual school assignments within the district can depend on which street you buy on. If the specific elementary school matters to you — or you're thinking about a home just outside city limits where district assignment might differ — confirm the boundary before you make an offer, not after. The schools page has the district overview, but a quick call to the district office with a specific address is the only reliable answer. This is the mistake that people don't discover until their kid is assigned to the school they didn't plan on.
Treating This Market Like a Fire Sale — Or Like Portland
Pendleton's price point surprises buyers coming from western Oregon, and that surprise sometimes produces two opposite errors: lowballing on a well-priced home because "it can't really be worth that little," or assuming the market is so calm that any offer will be accepted. Neither is right. Homes priced correctly for their condition move without drama. Homes priced above their condition sit. Reading the difference requires knowing the local inventory, which is one more reason to work with an agent who has closed deals specifically in Umatilla County.
Local Expert Takeaway: Pendleton is genuinely one of the more approachable first-time buyer markets in Oregon — not because the homes are perfect, but because the pace gives you room to be deliberate. The cash required at closing is the number most buyers get wrong: budget for both your down payment and 2%–5% in closing costs from the start, get pre-approved before you walk through a single door, and never waive the inspection on a home built before 1990, which describes a large portion of what's listed here. The employment base — anchored by the Confederated Tribes, Umatilla County, and the school district — gives the market unusual stability for a city of 16,950. If you're weighing Pendleton against Hermiston or Milton-Freewater, the difference usually comes down to job proximity and neighborhood character, not price tier. This is a market where doing the preparation work actually pays off.
Quick Takeaways & FAQs
✅ Pendleton's typical home price of $304,381 (July 2026) puts genuine homeownership within reach for first-time buyers who have saved for both a down payment and closing costs.
⚠️ Pendleton's housing stock skews toward pre-1990 construction — never waive the inspection here, even when a seller pushes back.
📍 Get your pre-approval letter before touring homes; sellers in Pendleton won't take an unleveraged offer seriously, and the right property at the right price doesn't wait.
What credit score do I need to buy a home in Pendleton, Oregon?
How long does it take to close on a home in Pendleton?
Is it cheaper to buy or rent in Pendleton right now?
Are there active-adult or 55+ communities in Pendleton for buyers who want to downsize?
What are closing costs in Oregon, and who pays them?
Moving to Oregon?
Tell us what you need help with and we'll connect you with local resources.
