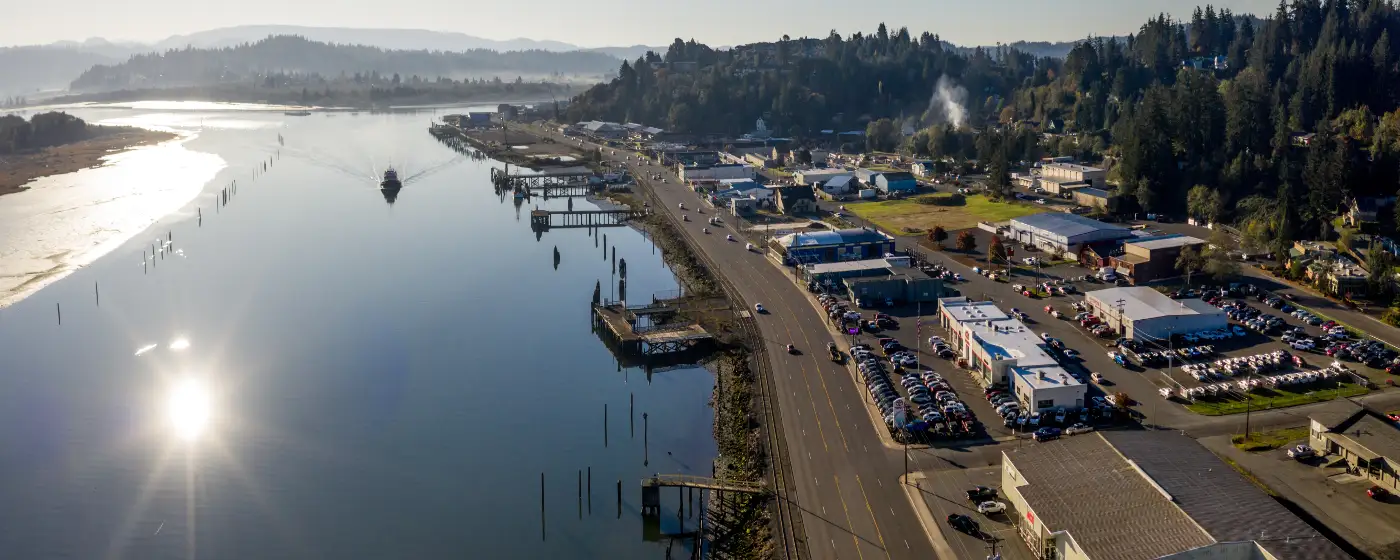
Most people who move to North Bend from Portland or the Willamette Valley have the same reaction: they can actually afford a house here. That observation is grounded in something real — the typical home price of $362,945 (Zillow Home Value Index, July 2026) sits noticeably below the Oregon state average and well below most coastal communities in the Pacific Northwest. But affordability on the coast comes with its own texture. The local job market is thinner than what buyers moving from larger metros are used to, and the median household income here falls short of what most lenders want to see behind that purchase price. The math still works for many buyers — it just requires honest budgeting upfront.
North Bend sits on the southern Oregon Coast in Coos County, a city of 10,049 residents connected to Coos Bay by a short drive and to the wider world by US-101. The local economy draws on healthcare workers at a regional hospital in Coos Bay, Coos County and City of North Bend municipal employment, the Oregon International Port of Coos Bay, timber and wood products, and tourism anchored by the Oregon Dunes National Recreation Area. Southwestern Oregon Community College provides workforce training and represents another employment anchor in the area. The North Bend School District 13 — which holds a B rating, according to Niche — rounds out the major institutional employers locally. These are the employers that determine who can realistically afford to buy here, and understanding that labor market before you commit to a price range is half the battle.
Oregon's lack of a state sales tax makes everyday costs feel lighter than they do in many states, and the effective property tax rate of approximately 0.71% is among the lower rates on the West Coast. That helps the monthly carrying cost stay manageable even when the down payment feels like a stretch. Buyers from higher-cost California and Willamette Valley markets have noticed: North Bend is one of the few coastal Oregon cities where a first-time buyer with a standard salary and a conventional loan can realistically close a deal without a six-figure down payment. For a fuller picture of ongoing costs, see the cost-of-living breakdown.
Whether you've been renting in Coos Bay and watching the market, or you're relocating from out of state and still getting your bearings, the sections below walk through what your budget actually buys here, how the purchase process works step by step, realistic cash-to-close scenarios, and the specific mistakes that trip up first-timers in this market.
The North Bend First-Time Buyer Reality
The typical home price in North Bend is $362,945 (Zillow Home Value Index, July 2026). That number represents the middle of the actual market — genuinely entry-level homes sit below it, while move-in-ready properties in established neighborhoods tend to run above it. For a detailed look at what different neighborhoods offer and how they compare, see the neighborhood guide.
The affordability tension here is real and worth naming directly: the median household income in North Bend falls short of the income a lender typically wants to see behind this purchase price by about $14,000. That gap is not insurmountable, but it means first-timers who are buying on a single income or a modest dual income need to be strategic — either targeting homes below the typical price, bringing a co-borrower, or building reserves that demonstrate financial stability to an underwriter. Buyers from Coquille or other nearby communities where prices run somewhat lower will find North Bend a step up in cost.
North Bend is eligible for USDA Section 502 Guaranteed Loan financing, which allows qualifying buyers to purchase with no down payment. That program designation reflects North Bend's population and rural classification under federal rules, and it opens a door that does not exist in most Oregon cities of comparable amenity level. USDA eligibility can change when maps are updated, so any buyer pursuing this route should verify their specific parcel directly with the USDA before structuring their offer around it. For buyers who do not qualify for USDA, FHA financing — requiring as little as 3.5% down for borrowers with credit scores of 580 or above — is the most common path into a first home here. Oregon also defines first-time homebuyer broadly: anyone who has not owned a home in the past three years qualifies for most state-administered programs, which means some repeat buyers may have more options than they realize.
The Homebuying Process in North Bend, Step by Step
Step 1: Get Pre-Approved Before You Tour a Single House
This is the step most first-timers get wrong in North Bend, and the one sellers' agents here notice immediately. The coastal Oregon market moves at a different pace than Portland, but well-priced homes in established neighborhoods still attract multiple offers. Showing up without a pre-approval letter signals that you are not ready to compete, and sellers will not wait while you go find one. Pre-approval — not pre-qualification, which is a softer, unverified estimate — means a lender has pulled your credit, verified your income and assets, and issued a letter stating the loan amount you qualify for.
Compare at least three lenders before committing, and ask each one which first-time buyer loan options you qualify for given your income, credit, and the Coos County market. A lender experienced with Oregon coastal transactions will also be less surprised by coastal-specific underwriting considerations like wind exposure and the inspection items that commonly come up on older housing stock here.
Step 2: Define Your Price Range Honestly
Pre-approval tells you the maximum you can borrow — not what you should spend. Build your actual budget around monthly carrying costs, not the purchase price alone. Use the interactive calculator below this section to stress-test your numbers at current rates. Most financial advisors suggest keeping housing costs at or below 28% of gross monthly income; in North Bend's market, buyers who stretch past that threshold to get into a preferred home often find the ongoing carrying costs uncomfortable within the first year.
Step 3: Shop Strategically — Neighborhood and School Boundaries Matter
North Bend's neighborhoods vary in character more than the city's modest size might suggest. Glasgow, Simpson Heights, and Hillcrest each attract different buyer profiles and have different proximity to employers, US-101 traffic, and the school boundary lines that feed into the district's elementary schools. If school placement is relevant to your decision — and for families with school-age children, it often is — verify the specific boundary for any address you are considering before you make an offer. The neighborhood guide covers character and fit in more detail.
Step 4: Make a Clean, Well-Structured Offer
In North Bend, offers need to be complete and credible from the start. Include your pre-approval letter, state your earnest money clearly, and if the seller has reviewed multiple offers before, your agent will be able to advise on whether an escalation clause makes sense. Waiving contingencies to compete is a separate question — covered in the mistakes section below.
Step 5: Inspection, Appraisal, and Closing
The inspection period is your last real chance to catch problems before you own them. Coastal Oregon homes face specific exposure: salt air accelerates corrosion on metal components, older rooflines in neighborhoods like Cooston and East Bay can show deferred maintenance that is not obvious from the street, and the marine climate means moisture intrusion is worth looking at carefully. Budget for the inspection without trying to save money on it — a thorough inspector on a $300,000 house is worth every dollar. The appraisal follows and is required by your lender; if it comes in below the purchase price, you will need to renegotiate, make up the difference in cash, or walk away. Closing in Oregon typically takes 30–45 days from accepted offer. You will owe closing costs, prepaid items, and any lender fees — all of which are detailed in the table below.
How Much Home Can You Afford in North Bend
The table below models realistic cash-to-close requirements across several purchase price scenarios. Closing costs are estimated at 2–3% of the purchase price, which is a reasonable range for Coos County transactions and includes lender fees, title insurance, prepaid property taxes, and homeowners insurance escrow setup. These are estimates only — your actual costs will depend on your loan type, lender, and negotiated terms.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (2–3%) | Est. Cash Needed at Table |
|---|---|---|---|---|
| FHA minimum (3.5% down, 580+ credit score) | $250,000 | $8,750 (3.5%) | $5,000–$7,500 | ~$13,750–$16,250 |
| FHA minimum (3.5% down, 580+ credit score) | $300,000 | $10,500 (3.5%) | $6,000–$9,000 | ~$16,500–$19,500 |
| FHA minimum (3.5% down, 580+ credit score) | $362,945 (typical home price) | $12,703 (3.5%) | $7,259–$10,888 | ~$19,962–$23,591 |
| Conventional minimum (3% down) | $300,000 | $9,000 (3%) | $6,000–$9,000 | ~$15,000–$18,000 |
| Conventional minimum (3% down) | $362,945 (typical home price) | $10,888 (3%) | $7,259–$10,888 | ~$18,147–$21,776 |
| USDA (0% down, if eligible) | $300,000 | $0 | $6,000–$9,000 | ~$6,000–$9,000 |
USDA financing eliminates the down payment but does carry a guarantee fee that is typically rolled into the loan balance, so the effective loan amount will be slightly above the purchase price. North Bend is currently listed as a USDA-eligible area — verify your specific parcel before structuring an offer around this program, since eligibility maps are updated periodically.
FHA loans carry an upfront mortgage insurance premium (typically 1.75% of the loan amount, often rolled into the loan) and an annual mortgage insurance premium charged monthly. Conventional loans with less than 20% down require private mortgage insurance (PMI), which cancels automatically once you reach 20% equity — a meaningful long-term advantage over FHA's mortgage insurance structure. The interactive mortgage calculator below this section lets you model monthly payments at current rates for any of these scenarios.
One honest note on credit score: most state-administered programs in Oregon require a minimum score of 620, though FHA loans are technically available down to 580 for the 3.5% down option. If your score sits between 580 and 619, your loan program options narrow considerably, and the rate you are offered on the programs that remain will be higher. Spending three to six months improving your score before applying is often the highest-return financial move a first-time buyer can make.
Looking to buy in North Bend? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a North Bend quote.
Common First-Time Buyer Mistakes in North Bend
Mistake 1: Touring Homes Before You Have a Pre-Approval Letter
It is genuinely easy to lose a house in North Bend to another buyer while you are assembling your pre-approval documents. The coastal Oregon market is not the frenzied pace of 2021, but sellers of well-priced homes have no incentive to hold for an unverified buyer. Fall in love with a house in Hillcrest without a letter in hand, and you may watch it go under contract while your lender is still waiting on your tax returns.
Mistake 2: Waiving the Inspection to Compete
First-time buyers sometimes hear that waiving the inspection contingency makes an offer stronger, and in some high-competition markets that logic has merit. In North Bend, it rarely does. The coastal environment — salt air, marine humidity, the age of much of the city's housing stock — means inspection surprises are common and sometimes expensive. Older homes in Cooston and East Bay in particular can carry deferred maintenance on roofs, crawlspaces, and electrical panels that a street-level walkthrough will never reveal. Waiving an inspection to save money and then discovering a significant structural or systems problem after closing is one of the most consistent regrets buyers in this market report after the first year.
Mistake 3: Ignoring the Commute and School-Boundary Reality
North Bend is only about 10 minutes to Coos Bay, which makes the two cities feel interchangeable to an outsider. They are not. Buyers who assume any address in either city gives them equal access to the regional hospital, Southwestern Oregon Community College, or the Port of Coos Bay employment base sometimes find their daily drive longer and less convenient than they modeled. School boundaries are a related trap: two houses on the same block can feed into different elementary schools, and in a district with 2,698 students enrolled in 2025-26, those distinctions matter to families. Verify the boundary for your specific address through the North Bend School District directly — do not assume the neighborhood name tells you which school your child attends.
Mistake 4: Underbudgeting the Cash Needed at Closing
First-time buyers almost universally focus on the down payment and forget the closing costs sitting next to it. In a North Bend transaction, closing costs typically add another 2–3% of the purchase price on top of the down payment, plus prepaid homeowners insurance, the initial property tax escrow deposit, and any lender origination fees. On a $300,000 purchase with 3.5% down, that means arriving at the table needing somewhere around $16,500–$19,500 in liquid cash — not the $10,500 the down payment alone would suggest. Buyers who discover this math two weeks before closing sometimes scramble in ways that introduce real risk to the transaction. Budget for the full cash-to-close figure from day one, not just the down payment.
Local Expert Takeaway: North Bend is one of the more accessible entry points on the Oregon Coast for a first-time buyer with a standard income and conventional financing — the typical home price of $362,945 (July 2026) is well below most comparable coastal markets, and the city's USDA eligibility opens a zero-down path that does not exist in many Oregon cities its size. The catch is that the local income base is thinner than buyers from Portland or California are used to, and the median household income here runs short of what most lenders want behind that purchase price. The buyers who succeed here are the ones who get pre-approved before they tour, budget for the full cash-to-close figure rather than just the down payment, and do not waive the inspection on a coastal home that may be carrying decades of salt-air wear.
Quick Takeaways & FAQs
✅ North Bend's typical home price of $362,945 (July 2026) sits noticeably below the Oregon state average and most other Oregon coastal communities, giving first-time buyers genuine entry-level options.
⚠️ The median household income in North Bend falls about $14,000 short of what most lenders want to see behind the typical home price here — buyers need to be strategic about price range, co-borrowers, or loan programs.
📍 North Bend is a USDA-eligible area, meaning qualifying buyers may be able to finance a home with no down payment — a rare option for an Oregon coastal city — but eligibility maps update periodically, so verify your specific parcel before structuring an offer around it.
What is the typical home price in North Bend, Oregon for a first-time buyer?
Can I buy a home in North Bend with no down payment?
What credit score do I need to buy a home in North Bend?
How much cash do I actually need to close on a home in North Bend?
Is it better to use FHA or conventional financing to buy a first home in North Bend?
Moving to Oregon?
Tell us what you need help with and we'll connect you with local resources.
