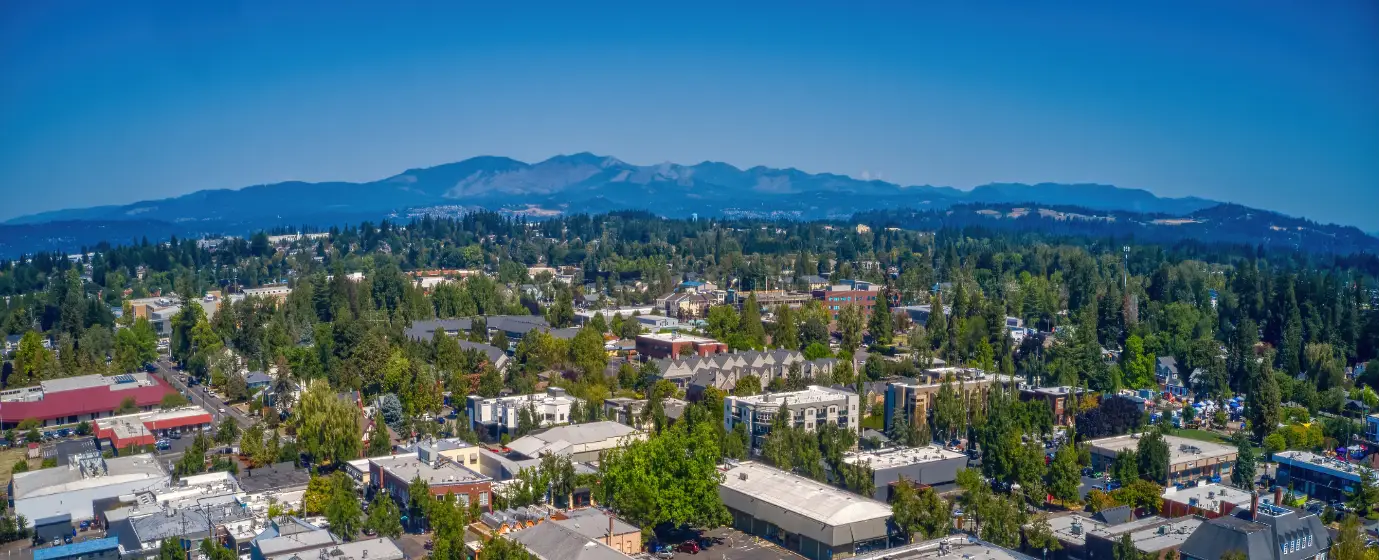
Maybe you've been priced out of Portland proper and someone mentioned Gresham. Maybe you ran the numbers and the typical home price looked manageable compared to the west side. Here is what the spreadsheet won't tell you: Gresham is the 4th-largest incorporated city in Oregon, with 112,378 residents, a real economy anchored by manufacturing and health care, and a direct MAX Blue Line connection to downtown Portland — yet its entry-level housing stock can still land a first-timer in a single-family home rather than a condo. That combination is real and it matters, but it comes with honest trade-offs worth knowing before you make an offer.
The economic backbone here is a mix of school districts, the City of Gresham itself, and Microchip Technology's semiconductor campus. Health care and retail round out the job base. The Gresham-Barlow School District 10J serves most of the city. Many buyers moving here from Portland are in their early thirties, often working remotely or commuting via MAX, and drawn by the price gap between Gresham and the neighborhoods they are leaving behind. The city also pulls buyers who simply want more square footage and a garage — things that are genuinely hard to find in Portland at similar price points.
Cost of living is the central reason Gresham draws first-timers from across the metro. The typical home price of $470,730 (Zillow Home Value Index, July 2026) sits noticeably below Portland, while Troutdale and Fairview come in at roughly the same level — so Gresham isn't a dramatic outlier from its immediate neighbors, but the gap with Portland is real and felt. There is no state income tax in Oregon, which helps with monthly cash flow, though property taxes still add up at an effective rate of approximately 0.98%. Day-to-day life includes access to the Gresham Farmers' Market, Main City Park, and the newly reopened East County Library — a renovated 95,000-square-foot Multnomah County branch — alongside independent coffee shops and a dining scene that leans toward local rather than chain-driven.
Whether you are just starting your research or ready to write an offer, the sections below break down what your budget actually buys in Gresham, the step-by-step buying process, a realistic cash-needed snapshot, and the specific mistakes that trip up first-timers in this market.
The Gresham First-Time Buyer Reality
The typical home in Gresham costs $470,730 (Zillow Home Value Index, July 2026). That figure puts a single-family home within reach for a dual-income household — but the median household income here is $77,795, which falls noticeably short of what most lenders need to see to carry that purchase comfortably at current rates. That gap is the central tension first-timers face, and it is worth confronting before you fall in love with a listing.
What does that price actually buy? In the Centennial area, which runs below the city median, you can find older ranch-style homes from the 1970s and 1980s — smaller square footage, sometimes needing updates, but with yards and driveways that condos simply do not offer. Powell Valley and Northwest Gresham trade at roughly the city median and tend to offer a bit more polish. Kelly Creek, Gresham Butte, and Pleasant Valley all sit above the median, meaning a first-timer shopping there should expect to stretch the budget or wait for the right listing to surface.
Oregon's statewide median down payment for a single-family purchase was $65,341 in 2024 — more than double the national figure — which tells you something real about the cash barrier in this market. First-timers entering without existing home equity face a steeper uphill climb than the headline price suggests. The good news is that Gresham's price point keeps many purchases within FHA loan limits, and the city's direct transit link to Portland means buyers who need downtown access do not have to pay Portland prices to get it. For a fuller breakdown of what the typical home price means for your monthly costs, see the cost of living page.
The Homebuying Process in Gresham, Step by Step
Step 1 — Get Pre-Approved Before You Tour Anything
This is the step first-timers in Gresham most consistently skip or delay, and it costs them. Sellers in this market expect a pre-approval letter attached to any serious offer. Showing up to open houses in Hollybrook or Powell Valley without one puts you at a structural disadvantage the moment a competing buyer appears. Pre-approval is not the same as pre-qualification — a full pre-approval involves a hard credit pull, income verification, and a conditional commitment from the lender.
Step 2 — Set Your Search Radius Honestly
Once you have a pre-approval letter and a purchase ceiling, build your search around it. In Gresham, that means being clear-eyed about which neighborhoods are within your range. Centennial tends to be the entry point for buyers at tighter budgets; Gresham Butte and Kelly Creek are where the same budget stretches thinner. Your buyer's agent should pull active listings only in the tiers that match your approval — browsing above your ceiling is how buyers end up overbidding to compensate emotionally.
Step 3 — Make an Offer With All Contingencies Intact
A Gresham purchase contract will include an inspection contingency, a financing contingency, and an appraisal contingency. In a competitive offer situation, buyers sometimes feel pressure to waive one. Don't waive the inspection contingency on a 1970s ranch in Centennial — older homes here can carry deferred maintenance that isn't visible at a showing. The financing contingency protects you if your loan falls through; the appraisal contingency protects you if the home appraises below your offer price. All three exist for a reason.
Step 4 — Inspection and Appraisal
Oregon does not require a seller to make repairs, but your inspection gives you the information to negotiate or walk away. Budget enough time in your escrow period for the inspection report to come back and for you to actually read it. The appraisal is ordered by your lender, not by you — if it comes in below the contract price, you have options: negotiate the price down, make up the gap in cash, or exercise your contingency.
Step 5 — Closing in Oregon
Oregon is an escrow state, meaning a title or escrow company — not an attorney — handles the closing. You will sign a large stack of loan documents, pay your closing costs and remaining down payment, and receive keys typically the same day. Budget two to three weeks from clear-to-close to actual closing. One step first-timers often underestimate: the final walk-through, which should happen within 24 hours of closing to confirm the property's condition hasn't changed since inspection.
How Much Home Can You Afford in Gresham
The table below shows what different purchase scenarios look like in terms of upfront cash. These are estimates using standard rate assumptions — the actual figures depend on your credit score, lender, and the specific loan program you qualify for. Closing costs in Oregon typically run 2–3% of the purchase price and include title, escrow, lender, and prepaid costs. The interactive calculator below the table lets you plug in your own numbers for a more precise monthly picture.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (2–3%) | Cash Needed at Table |
|---|---|---|---|---|
| FHA — 3.5% down, entry-level | $350,000 | $12,250 (3.5%) | $7,000–$10,500 | ~$19,250–$22,750 |
| FHA — 3.5% down, near city median | $470,000 | $16,450 (3.5%) | $9,400–$14,100 | ~$25,850–$30,550 |
| Conventional — 3% down, entry-level | $350,000 | $10,500 (3%) | $7,000–$10,500 | ~$17,500–$21,000 |
| Conventional — 3% down, near city median | $470,000 | $14,100 (3%) | $9,400–$14,100 | ~$23,500–$28,200 |
| Conventional — 5% down, above median | $530,000 | $26,500 (5%) | $10,600–$15,900 | ~$37,100–$42,400 |
| Conventional — 10% down, above median | $530,000 | $53,000 (10%) | $10,600–$15,900 | ~$63,600–$68,900 |
FHA loans require a credit score of at least 580 to qualify at 3.5% down; scores between 500 and 579 require 10% down. Note that FHA loans carry an upfront mortgage insurance premium — typically 1.75% of the loan amount — which can be rolled into the loan rather than paid at closing, so your out-of-pocket cash need is as shown above. Conventional loans at less than 20% down require private mortgage insurance, which adds to the monthly payment but is cancellable once you reach 20% equity.
One item the table cannot capture: the City of Gresham administers a city-run loan program for qualified low-income first-time buyers that can assist with down payment and closing costs on purchases within its price cap. Ask your lender whether you meet the income and purchase-price thresholds to pursue it alongside your primary financing.
Looking to buy in Gresham? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Gresham quote.
Common First-Time Buyer Mistakes in Gresham
Shopping Without a Pre-Approval Letter
This is the most common and most consequential mistake. The Gresham market is not moving at the frenetic pace of 2021, but well-priced homes in Powell Valley and Northwest Gresham don't sit. A buyer who tours on Saturday and then spends the following week gathering pay stubs will lose the listing while a pre-approved buyer moves forward. Get the letter before you tour anything — it also forces a realistic conversation about what you actually qualify for, which is often different from what an online calculator suggested.
Waiving the Inspection on Older Housing Stock
A meaningful share of Gresham's entry-level inventory was built in the 1970s and 1980s. These homes can carry aging electrical panels, original plumbing, and roofs that are closer to the end of their useful life than a showing reveals. Waiving the inspection to strengthen an offer on a 45-year-old ranch in Centennial is a specific mistake that buyers in this price range sometimes make under competitive pressure. The cost of a thorough inspection is small compared to the deferred maintenance it can surface.
Ignoring School Boundaries and District Lines
Gresham sits within multiple school district boundaries — Gresham-Barlow School District 10J, Reynolds School District, and Centennial School District all serve parts of the city. Two homes on the same block can feed into different districts. If the school assignment matters to your family, confirm the boundary before you make an offer, not after. The schools page has more detail on what each district covers.
Underestimating the Cash Needed at Closing
First-timers routinely budget for the down payment and forget that closing costs are a separate line item. In Oregon, 2–3% in closing costs on a $470,000 purchase adds up to roughly $9,400 to $14,100 on top of whatever you are putting down. Add to that the earnest money deposit (typically 1–2% of the purchase price, paid upfront and applied toward closing), prepaid homeowners insurance, and the first year's property taxes that lenders often require in escrow at closing — and the total cash requirement can surprise buyers who planned only for the down payment figure.
Buying Based on the Commute You Think You'll Have, Not the One You'll Actually Have
Gresham is about 25 minutes to Portland by car — in ordinary conditions, midday, on a clear day. The MAX Blue Line from Gresham Central Transit Center into downtown Portland is a genuine option for car-free commuters. But if your job is not along the Blue Line corridor and you're counting on I-84 every morning, the actual commute experience during peak hours can differ substantially from the number you ran in Google Maps on a Tuesday afternoon. Drive the route at the time you would actually leave before you make an offer on a home at the east end of the city. See the living in Gresham page for more on what the commute looks like day to day.
Local Expert Takeaway: Gresham's entry-level price point is real, but the upfront cash requirement — down payment plus 2–3% in closing costs plus the earnest money deposit — is where first-timers most often get caught flat-footed. A $470,000 purchase with 3.5% down still needs roughly $25,000 to $30,000 in total cash at the table before you account for moving costs or any immediate repairs. Get pre-approved first, shop within your actual approved range rather than your hoped-for one, and never waive an inspection on 1970s or 1980s construction in Centennial without understanding what you're agreeing to.
Quick Takeaways & FAQs
✅ The MAX Blue Line gives Gresham buyers car-free access to downtown Portland — a genuine commute alternative that adds real value to homes near the Gresham Central Transit Center.
⚠️ The median household income in Gresham falls about $48,000 short of what is needed to carry the typical home price comfortably — upfront cash and careful budgeting matter more here than the headline price suggests.
📍 School district boundaries in Gresham are not uniform across the city — two homes on the same street can feed into different districts, so confirm boundaries before writing an offer.
What credit score do I need to buy a home in Gresham, Oregon?
How much cash do I actually need to buy a home in Gresham?
Is Gresham a buyer's or seller's market right now?
What is the difference between the school districts in Gresham?
Can I use the MAX Blue Line to commute from Gresham to Portland?
Moving to Oregon?
Tell us what you need help with and we'll connect you with local resources.
