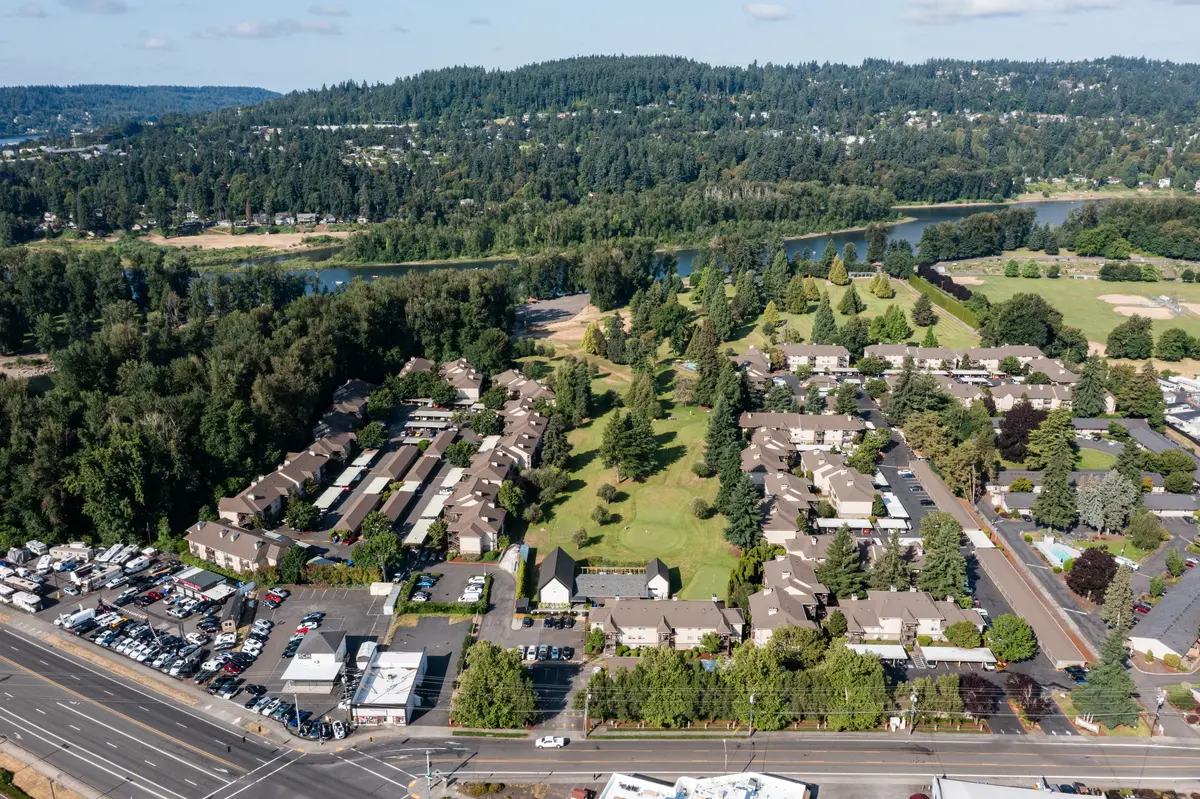
You've probably looked at Portland and felt the sticker shock, then looked at Oregon City or Milwaukie and found the same inventory arguments with slightly different zip codes. Gladstone sits in a quieter corner of that conversation — a 4-square-mile city at the confluence of the Willamette and Clackamas rivers, about 8 miles south of downtown Portland along OR-99E (McLoughlin Boulevard). At 11,898 residents, it is small enough that neighbors recognize each other, but connected enough that a commute of about 20 minutes to Portland is realistic for most of the workforce. For a first-time buyer, that combination is genuinely worth understanding before you get priced out of the markets around it.
The economic picture here is modest by design. The largest local employers are the Gladstone School District and the City of Gladstone itself, meaning most residents commute to Oregon City, Milwaukie, or the broader Portland metro for work. The Gladstone School District 115 holds a B- rating, according to Niche, and serves 1,564 students enrolled in 2025-26 — a small district where parent involvement tends to be high and familiar faces are common. The community skews toward working families and long-term residents rather than the investor-heavy speculation that drives turnover in some Portland suburbs.
The cost case for Gladstone is specific. The typical home price is $518,084 (Zillow Home Value Index, July 2026) — noticeably below Oregon City and West Linn, and roughly on par with Milwaukie. That figure matters for a first-timer because it puts a real purchase within reach of conventional and FHA loan programs without the financing gymnastics required in pricier corners of the metro. The catch is real, though: the median household income of $91,250 sits meaningfully below what is needed to carry the typical home here comfortably, so budgeting precisely before you start touring is not optional — it is the whole game. Full cost-of-living context is on the cost of living page.
Whether you have never bought before or you have not owned a home in the last three years — which is how Oregon programs typically define a first-time buyer — this guide walks through what Gladstone's market actually demands: what your budget buys, how the process works step by step, what cash you genuinely need at the table, and the specific mistakes that derail first-time buyers in this market before they ever make an offer.
The Gladstone First-Time Buyer Reality
The typical home price in Gladstone is $518,084 (July 2026), and that number is doing a lot of work for a first-time buyer. It is low enough that FHA and 3%-down conventional loans are viable tools — you are not being pushed into an impossible down payment — but high enough that the cash you need at the table, once you add closing costs and earnest money, routinely surprises buyers who planned only for the down payment itself.
At that price point, you are mostly competing for detached single-family homes built between the 1950s and 1980s — the core of Gladstone's housing stock in neighborhoods like Sherwood Forest, Ridgewood, and the Webster Road area. Entry-level homes, meaning older construction or properties needing cosmetic work, may come in below the typical price, but they rarely sit long. Gladstone is small enough that well-priced homes attract multiple interested buyers quickly, and first-timers who are not pre-approved before they start touring will lose them before they have a chance to move.
One fact many first-time buyers don't realize: Oregon programs broadly define a first-time homebuyer as someone who has not owned a principal residence in the past three years. If you rented after a previous ownership, you may qualify for loan programs and rate advantages you assumed were off the table. That is worth a direct conversation with a lender before you assume your options are limited. The full neighborhood breakdown is on the neighborhoods page.
The Homebuying Process in Gladstone, Step by Step
Step 1: Get Pre-Approved Before You Tour Anything
In Gladstone's market, this is not a formality — it is a prerequisite. Sellers and their agents in this price range expect a pre-approval letter attached to any offer, and a pre-qualification letter (a softer, less verified version) will not carry the same weight. Use the pre-approval process to establish your actual purchase ceiling, not just a ballpark.
Step 2: Define Your Budget Including All Cash Needed
The down payment is only part of what you need liquid. Closing costs in Clackamas County typically run 2 to 4 percent of the purchase price — on a home at the $518,000 level, that means roughly $10,000 to $20,000 separate from your down payment. Earnest money in this county runs around 1% of the purchase price, deposited within a day or two of offer acceptance and applied toward your costs at closing. Budget for all three before you make your first appointment.
Step 3: Shop With an Agent Who Knows This Corridor
Gladstone is small, and the OR-99E corridor from Milwaukie through Gladstone to Oregon City has its own rhythms. An agent who regularly works this stretch will know which neighborhoods have active listings, which homes have been relisted and why, and where school boundaries fall — all things that matter once you are in contract and making decisions quickly.
Step 4: Write a Competitive Offer
A competitive offer in Gladstone is not necessarily the highest price. It is a clean offer — pre-approved, with earnest money ready, and with contingencies that are reasonable rather than stripped. The two contingencies first-time buyers most often get wrong here are the inspection contingency and the appraisal contingency. Both are standard in Oregon contracts; neither should be waived casually (more on this in the mistakes section).
Step 5: Inspection and Appraisal Window
Oregon inspection periods typically run 10 to 15 business days from mutual acceptance. During that window, your inspector examines the property, you review the findings, and you can request repairs, negotiate a credit, or — if the findings are serious — walk away. Home inspections are not legally required in Oregon, but skipping one on a 1960s ranch in Ridgewood because you want to look competitive is a risk that rarely pays off.
The appraisal, ordered by your lender, confirms the home's value supports the loan. If it comes in below the purchase price and you have an appraisal contingency, you have options: renegotiate, cover the gap in cash, or exit the contract. Without that contingency, you are on the hook for the difference.
Step 6: Clear to Close and Closing Day
Once the lender issues a clear to close, you will receive a final closing statement — a detailed accounting of every cost — at least three business days before the closing date. Review it carefully against your original Loan Estimate. Closing in Oregon typically happens at a title company. Bring a cashier's check or arrange a wire transfer for your remaining cash to close; personal checks are not accepted.
How Much Home Can You Afford in Gladstone
The table below shows estimated cash requirements at several realistic price points for Gladstone. Closing cost estimates use the Clackamas County range of 2 to 4 percent. These are approximations — your actual figures depend on your lender, loan type, negotiated seller concessions, and the specific property. Use the mortgage calculator below the table to model monthly payments at current rates.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (2–4%) | Cash Needed at Table |
|---|---|---|---|---|
| FHA — 3.5% down, entry-level home | ~$440,000 | ~$15,400 (3.5%) | ~$8,800–$17,600 | ~$24,200–$33,000 |
| Conventional — 3% down, entry-level home | ~$440,000 | ~$13,200 (3%) | ~$8,800–$17,600 | ~$22,000–$30,800 |
| FHA — 3.5% down, near typical price | ~$518,000 | ~$18,130 (3.5%) | ~$10,360–$20,720 | ~$28,490–$38,850 |
| Conventional — 3% down, near typical price | ~$518,000 | ~$15,540 (3%) | ~$10,360–$20,720 | ~$25,900–$36,260 |
| Conventional — 5% down, near typical price | ~$518,000 | ~$25,900 (5%) | ~$10,360–$20,720 | ~$36,260–$46,620 |
| Conventional — 10% down, near typical price | ~$518,000 | ~$51,800 (10%) | ~$10,360–$20,720 | ~$62,160–$72,520 |
These figures do not include earnest money (typically around 1% of the purchase price in Clackamas County, applied at closing) or cash reserves your lender may require. A larger down payment reduces your loan balance and eliminates private mortgage insurance once you cross the 20% equity threshold on a conventional loan — a meaningful monthly difference worth modeling.
One thing to keep in mind: a 2025 buyer survey found that roughly 46% of purchasers said the process cost more than they had anticipated. In a market like Gladstone, where homes are priced at a level that stretches many first-time budgets, the buyers who stay solvent through closing are almost always the ones who added a cash cushion on top of their "required" figures rather than budgeting to the dollar.
Looking to buy in Gladstone? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Gladstone quote.
Common First-Time Buyer Mistakes in Gladstone
Mistake 1: Shopping Before Pre-Approval
It is tempting to tour homes along the Trolley Trail corridor or through the Riverdale and River Run Village areas before you have a lender's letter in hand. In Gladstone's market, that approach consistently costs buyers the homes they actually want. By the time you circle back with a pre-approval, a well-priced listing at the entry level is often under contract. Get the letter first, then make appointments.
Mistake 2: Waiving the Inspection Contingency to Win an Offer
First-time buyers in competitive situations sometimes drop the inspection contingency to make their offer look cleaner. In Gladstone — where the housing stock skews older and issues like aging sewer laterals, galvanized plumbing, or dated electrical panels are common — this is the mistake that turns into a five-figure repair bill six months after closing. Oregon's standard inspection period gives you 10 to 15 business days to evaluate what you are buying. Use it. A well-written offer with a tight inspection timeline is more attractive to most sellers than one with no contingency at all.
Mistake 3: Ignoring the School Boundary Reality
Gladstone School District 115 is small and compact, so boundary surprises are less common here than in larger districts. But if your offer is on a home right at the city's edge — near the Cason Road area or where Gladstone abuts Milwaukie or unincorporated Clackamas — it is worth confirming which district boundary the address falls in before you fall in love with the property. The schools page has the full district breakdown.
Mistake 4: Underbudgeting the Cash Needed at Closing
Most first-time buyers focus on the down payment and treat closing costs as an afterthought. In Clackamas County, that afterthought can run $10,000 to $20,000 on a home near the $518,000 typical price — on top of the down payment, on top of earnest money, and on top of any cash reserves your lender requires. The buyers who get to the closing table without a crisis are the ones who treated closing costs as a fixed line item in their plan from the beginning, not as a rounding error to sort out later.
Local Expert Takeaway: Gladstone is one of the few places in the Portland metro where a first-time buyer using a 3% or 3.5% down loan can still reach the entry level of the single-family market without being immediately outgunned by investors or high-equity move-up buyers. The catch is that the margin for error is thin — the median household income does not fully support the typical home price, closing costs in Clackamas County run higher than most first-timers expect, and the market moves fast enough that going in without a pre-approval letter is a reliable way to lose homes you genuinely wanted. Get your financing in order first, build a real cash buffer on top of your down payment, and do not skip the inspection contingency on a 1960s ranch just to look competitive. Buyers who do those three things in this market tend to close. The ones who don't, often spend another six months watching listings.
Quick Takeaways & FAQs
✅ Gladstone's typical home price of $518,084 (July 2026) sits noticeably below Oregon City and West Linn, making FHA and 3%-down conventional loans genuinely viable for first-time buyers in this market.
⚠️ The median household income falls meaningfully short of what's needed to carry the typical home here — budget your full cash needs (down payment plus closing costs plus reserves) before you tour a single property.
📍 Earnest money in Clackamas County runs around 1% of the purchase price and must be deposited within a day or two of offer acceptance — have that cash liquid and ready before you make an offer, not afterward.
What credit score do I need to buy a home in Gladstone, Oregon?
How much cash do I actually need to buy a home in Gladstone?
Does the 'first-time homebuyer' definition apply to me if I owned a home before?
How competitive is the Gladstone real estate market for first-time buyers?
Should I waive the inspection contingency to make my offer more competitive in Gladstone?
Moving to Oregon?
Tell us what you need help with and we'll connect you with local resources.
