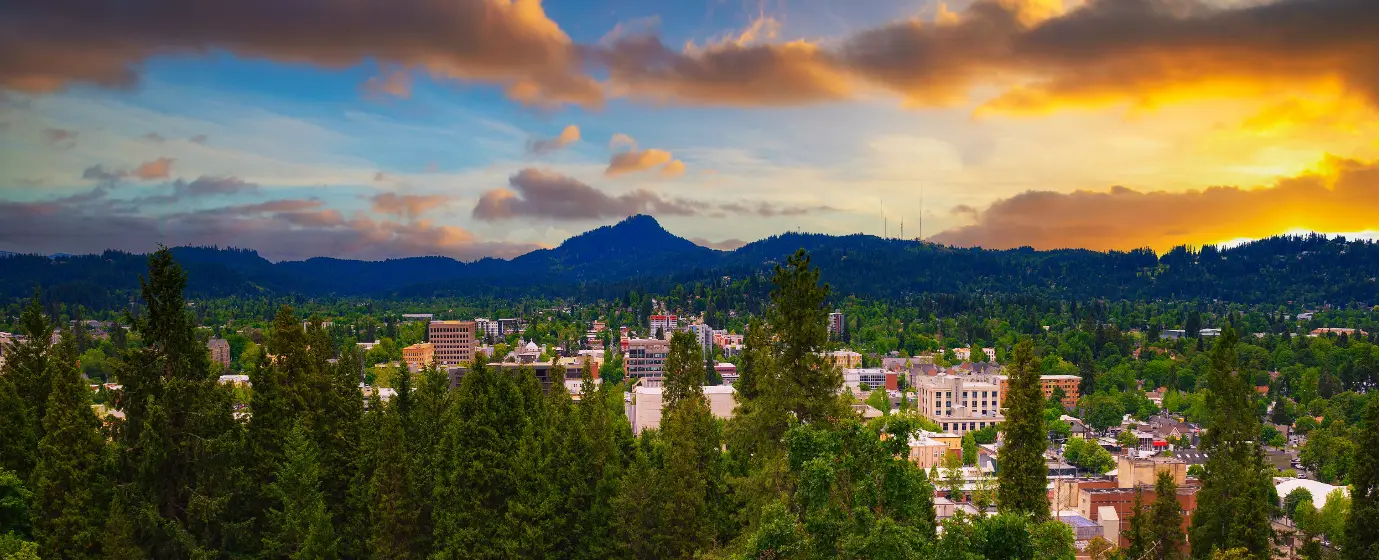
Maybe you've been renting near the University of Oregon for a few years and finally decided the math points toward buying. Maybe you're relocating from a pricier market and Eugene looks affordable by comparison — and it is, relative to Portland or the Bay Area — but the local picture is more complicated than the headline number suggests. The typical home price in Eugene sits at $482,062 (July 2026), which sounds approachable until you run the income math: the median household income here of $66,562 falls meaningfully short of what lenders typically want to see for that purchase price. That gap is the central financial reality every first-time buyer in Eugene needs to reckon with before they start touring homes.
Eugene is the 3rd-largest incorporated city in Oregon, with a population of 178,618. The University of Oregon anchors the economy and drives steady rental demand, which in turn keeps ownership looking attractive to people tired of competing for rentals. Lane County government, Eugene School District 4J, and a regional healthcare presence round out the employer base, giving the city more economic stability than its size might suggest. A micro-LED manufacturing facility being developed on the west side by Stratacache entered its pilot-line phase in 2026 and anticipates up to 400 direct jobs at peak — a sign that the economic base is quietly broadening beyond the university.
The market leans mildly toward sellers. It is not the frenzied environment of 2021, but well-priced homes in desirable neighborhoods — particularly those near the Ridgeline Trail System, Alton Baker Park, or the core of South Eugene — attract real competition. Neighborhoods like Bethel, River Road, and Whiteaker offer entry points below the city median, while Cal Young and Fairmount run above it. For buyers who haven't shopped Eugene specifically, the range of neighborhood personalities across those areas is wider than the city's size implies — something the neighborhoods guide covers in depth.
Whether you've just started thinking about buying or you're ready to make an offer, the sections below walk through what your budget actually buys in Eugene, the step-by-step process for getting to closing, how to stress-test your numbers before you tour a single home, and the mistakes that cost first-time buyers the most in this specific market.
The Eugene First-Time Buyer Reality
The typical home in Eugene is priced at $482,062 (Zillow Home Value Index, July 2026). That figure puts genuine homeownership within reach for buyers with solid credit and a plan — but it does not come easy on a median local income. The median household income of $66,562 falls roughly $62,000 short of what most lenders want to see to carry a home at that price comfortably, which means the first real task for most first-timers here is not finding a house but stress-testing whether the numbers work for their specific situation.
Entry points exist below that median — Bethel, River Road, and Whiteaker all price below the city-wide figure, and those neighborhoods are where the realistic first purchase often lands for buyers stretching to get in. The trade-off is that each of those areas has its own character and tradeoffs worth understanding before you commit: Whiteaker, for instance, is one of Eugene's more culturally interesting districts, but roughly a third of its properties carry elevated flood exposure, which adds insurance costs that don't show up in the list price. Review FEMA flood maps before you go under contract in that neighborhood — not after.
The market itself is mildly seller-leaning. Sellers still hold leverage and well-priced homes don't linger long, but this is not a market where you need to waive every protection just to compete. First-timers who walk in pre-approved, focused on realistic price bands, and coached by a buyer's agent who knows Eugene specifically are well-positioned. Buyers who show up with vague pre-qualification letters and champagne tastes on an entry-level budget tend to learn the hard way that the gap between what feels affordable at the open house and what the lender will actually approve is significant here.
The Homebuying Process in Eugene, Step by Step
Step 1: Get Pre-Approved — Before You Look at a Single Home
This is the step Eugene buyers most commonly skip or treat as optional, and it is the one that costs them the most. A pre-approval letter from a lender is not just paperwork — in a mildly competitive market, it signals to sellers that you are a serious buyer who has already cleared the financial hurdles. Sellers here are not desperate, and they will take the offer from the buyer who looks ready over the one who needs to "check with their bank."
To get pre-approved, gather your two most recent pay stubs and W-2s, two years of tax returns, bank and asset statements, documentation of any existing debts, and a government-issued ID before you approach a lender. Oregon uses HUD's definition of a first-time homebuyer — generally, someone who has not owned a primary residence in the past three years — so if you owned a home before but have been renting for several years, confirm your eligibility with your lender directly. A credit score of at least 620 is the common floor for most loan programs, though FHA loans can allow lower scores in some cases.
Step 2: Define Your Price Band and Pick Neighborhoods
Once you have a pre-approval amount, resist the urge to shop at the top of it. Build your realistic range around monthly payment, not purchase price — property taxes in Eugene run at an effective rate of approximately 0.95%, homeowner's insurance and routine maintenance are real ongoing costs, and the interactive calculator below this section can help you stress-test what different purchase prices actually look like monthly.
Use the neighborhood tiers from the neighborhoods guide to anchor your search geographically. If your pre-approval puts you below the city median, focus your touring time on Bethel, River Road, and Whiteaker rather than spending weekends looking at homes in Cal Young or Fairmount that will always be out of reach.
Step 3: Make Offers Strategically
Eugene homes can attract multiple offers and move quickly once a well-priced property hits the market. Have your offer terms discussed with your agent before you tour, not after — know your earnest money amount, your preferred closing timeline, and which contingencies are non-negotiable.
Step 4: Inspection and Appraisal
Do not waive your inspection. Eugene's older housing stock — particularly in the below-median neighborhoods where first-time buyers often land — includes homes with deferred maintenance, older electrical systems, and drainage issues that a thorough general inspection will surface. The inspection is the point in the process where you find out what you are actually buying. If the seller resists an inspection contingency, that resistance itself is information.
Your lender will order an appraisal independently. If the home appraises below the purchase price, you will need to negotiate with the seller, make up the difference in cash, or walk away using your appraisal contingency. First-timers are often surprised that an appraisal gap can emerge even in a modestly competitive market — if you are bidding above list price to win, understand what happens if the appraisal doesn't follow.
Step 5: Closing
Oregon closings are handled by escrow companies and title officers rather than attorneys. Expect to receive a closing disclosure at least three business days before your closing date — read it carefully and compare it to your Loan Estimate. Budget 2%–5% of the purchase price for closing costs on top of your down payment; those costs cover loan origination fees, appraisal, title insurance, and escrow setup. That cash needs to be in a verified account well before closing day.
How Much Home Can You Afford in Eugene
The table below gives you a working sense of how different purchase prices translate into cash required at the table, using common loan structures. These are estimates based on approximate ranges — your actual figures will depend on your credit profile, lender fees, and the specific property. The calculator that follows this section is where you model your real monthly payment; use this table to understand the upfront cash picture first.
Closing costs are estimated at 3% of the purchase price here — a reasonable midpoint of the 2%–5% Oregon range — but ask your lender for a Loan Estimate early in the process so you're not surprised by the real number.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (3%) | Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5%) — entry-level | $350,000 | $12,250 (3.5%) | ~$10,500 | ~$22,750 |
| Conventional (3%) — entry-level | $350,000 | $10,500 (3%) | ~$10,500 | ~$21,000 |
| FHA (3.5%) — near city median | $482,000 | $16,870 (3.5%) | ~$14,460 | ~$31,330 |
| Conventional (3%) — near city median | $482,000 | $14,460 (3%) | ~$14,460 | ~$28,920 |
| Conventional (5%) — mid-range stretch | $550,000 | $27,500 (5%) | ~$16,500 | ~$44,000 |
| Conventional (10%) — stronger position | $482,000 | $48,200 (10%) | ~$14,460 | ~$62,660 |
A larger down payment does more than reduce your loan balance — it eliminates private mortgage insurance (PMI) on a conventional loan once you reach 20%, and it can make your offer more attractive in a competitive situation. FHA loans allow lower credit scores and smaller down payments but carry an upfront mortgage insurance premium and ongoing monthly insurance costs that raise your effective payment; factor those in when comparing loan types with your lender.
One number that surprises many first-timers: the cash needed at the table is often larger than the down payment alone, because closing costs are due simultaneously. If a seller agrees to contribute toward closing costs as part of your negotiation, that reduces the cash you need to bring — worth asking for, particularly on homes that have been sitting longer or need work.
Looking to buy in Eugene? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Eugene quote.
Common First-Time Buyer Mistakes in Eugene
Shopping Before You're Pre-Approved
It feels harmless to browse Zillow and tour a few open houses before you have a lender lined up. In Eugene, it is a real problem. When a well-priced home in Bethel or the Friendly Area hits the market, it can receive multiple offers within days. A buyer who falls in love with a home before they have a pre-approval letter cannot move fast enough to compete — and the emotional investment in a home you can't actually make an offer on is a painful way to start the process.
Ignoring Neighborhood-Level Realities
Eugene's neighborhoods are genuinely different from each other in ways that matter for daily life. Buyers focused purely on price sometimes land in a neighborhood that works on paper but not in practice — a Whiteaker property that turns out to carry flood insurance costs that push the real monthly number well above what they budgeted, or a home in Bethel that feels like a deal until they realize the commute to the University of Oregon is longer and more congested than expected. Before you make an offer, spend time in the neighborhood at different times of day, and review the neighborhoods guide for what each area is actually like to live in.
Waiving the Inspection to Win
Eugene's older housing stock makes inspection waivers particularly risky here. In the below-median price bands where most first-timers start — River Road, Bethel, Whiteaker — you are often looking at homes built decades ago with deferred maintenance, aging roof systems, and drainage quirks that won't appear on any listing disclosure. Waiving the inspection to win a competitive offer is understandable; losing significant money to a foundation issue the inspection would have caught is avoidable. If the market requires you to waive the inspection to get a home, consider whether that is the right home.
Underestimating the Total Cash Required
First-time buyers in Eugene often budget for the down payment and forget that closing costs — running 2%–5% of the purchase price — are due at the same time, in verified funds. On a $482,000 purchase at 3.5% down, the down payment alone is under $17,000, but cash needed at closing can easily reach $31,000 or more once loan origination, title insurance, appraisal, and escrow fees are included. Add the earnest money deposit (typically 1%–2% of the purchase price, due when your offer is accepted and credited back at closing) and the reserve funds a lender may require, and the cash picture is meaningfully larger than the down payment number alone. Run the full cash-needed figure with your lender before you set your price ceiling, not after.
Local Expert Takeaway: Eugene is a buyable market for first-timers who do the work upfront — get pre-approved with real documentation, set your price band around total cash needed rather than just the down payment, and focus your search on the below-median neighborhoods like Bethel, River Road, or Whiteaker where entry points genuinely exist. If Whiteaker is on your list, pull the FEMA flood maps before you fall in love with a specific property — flood insurance can move the real monthly cost in ways that don't show up on any listing page. The market is competitive enough that hesitating costs you homes, but not so frantic that you need to strip out every protection to win.
Quick Takeaways & FAQs
✅ Eugene's below-median neighborhoods — Bethel, River Road, and Whiteaker — offer realistic entry points for first-time buyers who can't yet stretch to the city-wide typical home price of $482,062 (July 2026).
⚠️ The median household income in Eugene falls roughly $62,000 short of what most lenders want to see to comfortably carry the typical home price — running your actual numbers with a lender before touring is not optional, it's the first step.
📍 Whiteaker is one of Eugene's most culturally rich below-median neighborhoods, but roughly a third of its properties carry elevated flood exposure — review FEMA flood maps before going under contract there.
What credit score do I need to buy a home in Eugene, Oregon?
How much do I need for a down payment to buy a home in Eugene?
Is it hard to buy a home in Eugene as a first-time buyer?
What are the best neighborhoods in Eugene for first-time buyers on a tighter budget?
Does Oregon have a definition of 'first-time homebuyer' that affects loan eligibility?
Moving to Oregon?
Tell us what you need help with and we'll connect you with local resources.
