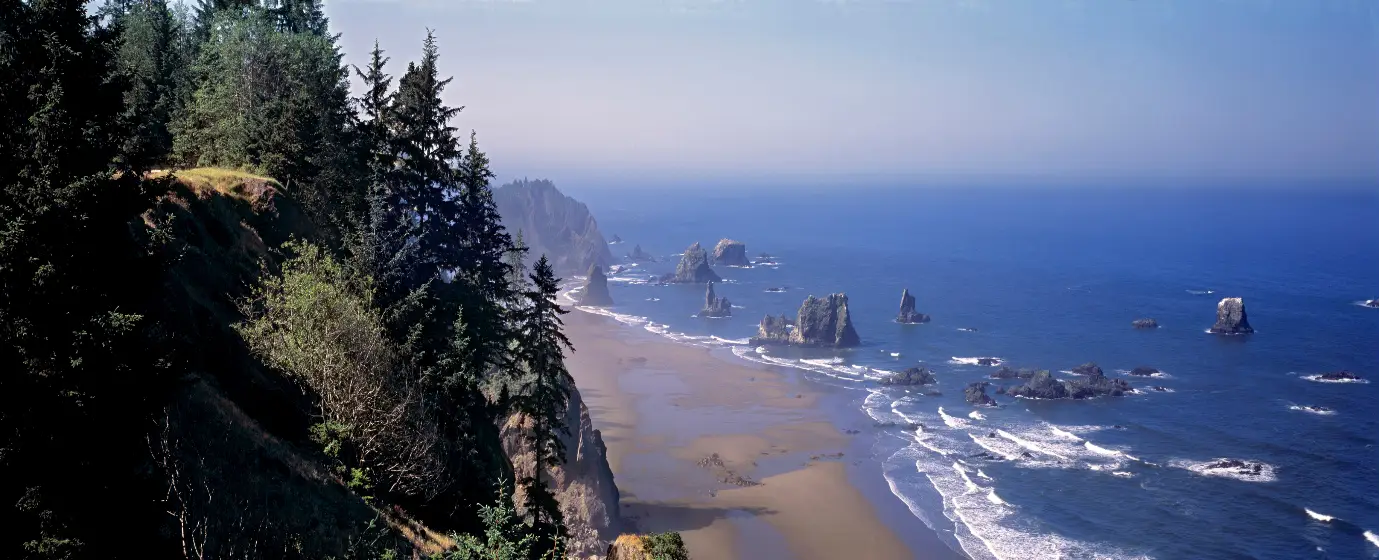
Maybe you've been watching listings in Brookings for a while, drawn by the Oregon Coast lifestyle and prices that look reasonable compared to the Willamette Valley. Or maybe you're relocating from Northern California and Brookings is suddenly the more affordable option on your map. Either way, the first thing to understand is that this is a small, slow-moving coastal market — 6,703 residents, a limited housing stock, and a buyer pool that includes both local families and out-of-state cash buyers chasing the same limited inventory. That dynamic shapes almost everything about how a first-time buyer should approach a purchase here.
The economic picture is honest and worth knowing upfront. The major employers in Brookings are the school district, a regional health system, and local government — not the kind of industry base that drives wage growth. The median household income sits below what's typically needed to carry the city's median home price, which means first-time buyers often need to look carefully at loan programs, down payment sources, and what price band is genuinely within reach. That's not a reason to walk away — it's a reason to go in with a clear-eyed budget before you fall in love with a specific address.
The Oregon Coast location also introduces a few variables that inland buyers don't face. Coastal wind and flood exposure drive homeowners insurance costs higher than the state average, and securing a policy before closing takes more lead time than many first-timers expect. On the upside, Brookings sits in one of the more temperate stretches of the Oregon Coast — with more than 191 sunny days a year — and the proximity to Harris Beach State Park, the Samuel H. Boardman State Scenic Corridor, and the Port of Brookings Harbor gives daily life a texture you genuinely can't replicate inland for this price.
Whether you're months away from an offer or just starting to research the area, the sections below break down what first-time buyers actually face in Brookings — the real numbers, the local process step by step, a budget snapshot table, and the specific mistakes that cost buyers in this market.
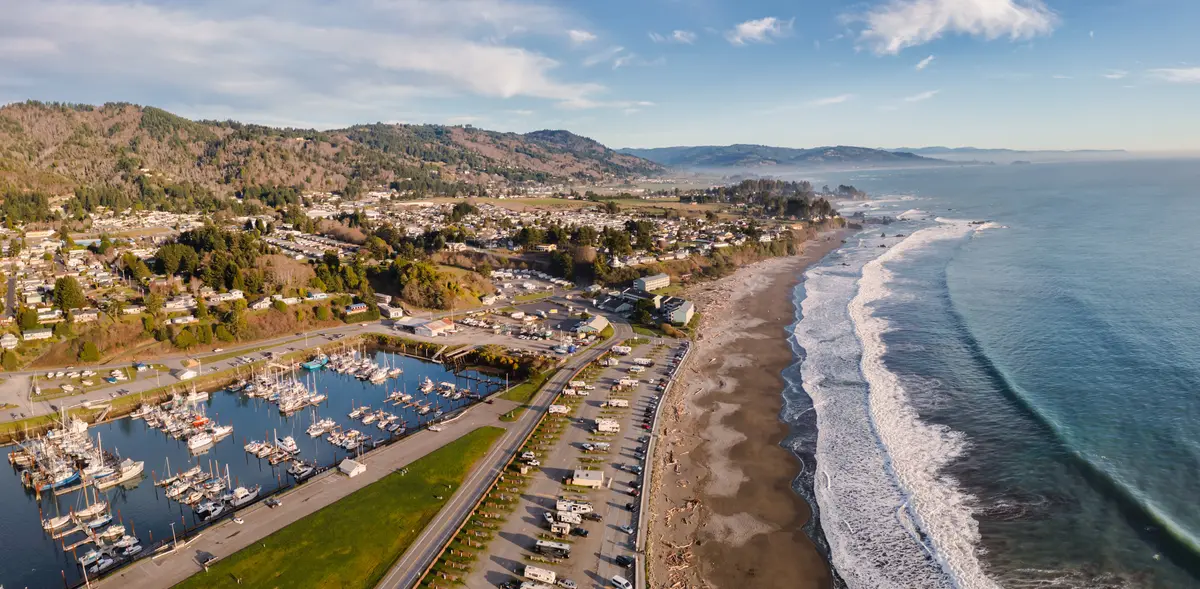
The Brookings First-Time Buyer Reality
The Zillow Home Value Index puts the typical home price in Brookings at $486,371 (July 2026). That figure sits well above what the city's median household income can comfortably carry, which means most first-time buyers here are stretching — either on down payment, on monthly obligation, or both. The honest entry point into this market is somewhere below that figure, concentrated in older ranch-style and mid-century homes in Harbor and parts of the Downtown Brookings area, where properties in need of updating occasionally come in under the city-wide typical.
The good news for first-timers is that Brookings is not a bidding-war market. Homes here sell at approximately 97% of asking price on average, and only a small fraction close above list — a meaningful contrast to the Portland metro or the Bend market, where first-time buyers routinely competed against multiple offers at the height of the cycle. That lower bidding pressure gives you more room to negotiate and more time to complete due diligence without panic.
The catch is inventory. Brookings is a small city on a remote stretch of US-101, and the pool of available homes at any given moment is thin. When a well-priced entry-level property does appear, competition tends to concentrate on that one listing rather than spreading across dozens of options. Coming in pre-approved, with your financial picture already clear, is not a nice-to-have here — it's the difference between being a credible buyer and watching someone else close on the house you wanted.
The Homebuying Process in Brookings, Step by Step
Step 1: Get a Real Pre-Approval
Oregon sellers expect a written lender pre-approval letter — not a pre-qualification — submitted with any financed offer. A strong letter names you, specifies the loan program, states the maximum loan amount, and includes your lender's contact information. In a town this size, listing agents often know local lenders personally; a letter from Evergreen Federal Bank or Rogue Credit Union, both of which have direct Brookings operations and experience with local transactions, can carry weight in ways an out-of-area online lender's letter sometimes doesn't.
Step 2: Shop with a Local Agent
Because Brookings inventory is thin, some homes sell before formal marketing begins — through agent networks and word of mouth. A local buyer's agent who knows the Harbor neighborhood from Crown Terrace Heights, and who has relationships with other agents in Curry County, is genuinely more valuable here than in a deep-inventory market where every listing is on the MLS the moment it's active.
Step 3: Make an Offer — and Understand the Contract
Oregon uses the OREF 001 Purchase and Sale Agreement as the standard contract. Once your offer is accepted, you'll make an earnest money deposit held by the escrow or title company. Financed purchases in Oregon typically close in 30 to 45 days, though coastal properties on well and septic systems can run longer if inspection results require follow-up.
Step 4: Inspections — Don't Shortcut These
Oregon law requires sellers to provide a property disclosure statement covering structural, mechanical, environmental, and material conditions — including flood zone, landslide, and seismic risk, all of which are genuinely relevant on the southern Oregon Coast. Beyond the general home inspection, plan for a sewer scope and, if the property uses a private system, a well and septic inspection. Coastal exposure also means scrutinizing foundation drainage, roof condition, and any wood in contact with the exterior more carefully than you would inland.
Homeowners insurance deserves its own step here. Coastal wind and flood exposure push premiums above the statewide average, insurers are tightening their appetite along the Oregon Coast, and your lender will require proof of coverage before funding the loan. Start shopping for insurance the week you go under contract — not the week before closing.
Step 5: Closing
Oregon closes through escrow, not a closing attorney. The title company or escrow officer coordinates the payoff of any existing liens, records the deed, and disburses funds. You'll receive a federal loan disclosure document at least three business days before your signing appointment — read it carefully against your Loan Estimate and flag any figures that shifted.
How Much Home Can You Afford in Brookings
The table below gives a rough sense of what different purchase prices and loan structures require at the table. All figures are estimates using standard rate assumptions — the interactive calculator below this section will give you a more precise monthly picture based on current rates and your specific inputs.
The FHA loan limit for Curry County covers the full range of realistic entry-level purchases in Brookings. Buyers with credit scores of at least 580 qualify for the 3.5% down payment minimum; scores between 500 and 579 require 10% down. Closing costs on a purchase this size typically run 2% to 3% of the purchase price, covering lender fees, title and escrow, prepaid insurance, and prepaid property taxes.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs | Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5% down) — lower entry | $360,000 | $12,600 (3.5%) | $7,200–$10,800 | ~$20,000–$23,400 |
| FHA (3.5% down) — mid entry | $430,000 | $15,050 (3.5%) | $8,600–$12,900 | ~$23,650–$27,950 |
| FHA (3.5% down) — near median | $486,000 | $17,010 (3.5%) | $9,720–$14,580 | ~$26,730–$31,590 |
| Conventional (3% down) — lower entry | $360,000 | $10,800 (3%) | $7,200–$10,800 | ~$18,000–$21,600 |
| Conventional (5% down) — mid entry | $430,000 | $21,500 (5%) | $8,600–$12,900 | ~$30,100–$34,400 |
| Conventional (10% down) — near median | $486,000 | $48,600 (10%) | $9,720–$14,580 | ~$58,320–$63,180 |
Note that FHA loans carry an upfront mortgage insurance premium (1.75% of the base loan amount) that is typically rolled into the loan rather than paid at closing, plus an annual mortgage insurance premium paid monthly. Conventional loans with less than 20% down carry private mortgage insurance instead, which cancels automatically once you reach 20% equity — a structural difference worth understanding before choosing between the two programs.
Oregon's effective property tax rate in Brookings is approximately 0.42% — among the lower rates in the state — which helps keep the ongoing ownership cost more manageable than the purchase price alone might suggest. See the full cost of living breakdown for more context on taxes and carrying costs.
Looking to buy in Brookings? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Brookings quote.
Common First-Time Buyer Mistakes in Brookings
Shopping Before You're Pre-Approved
In a thin-inventory market, this is how you lose the house. When a well-priced property appears in Harbor or near Azalea Park, the window between listing and accepted offer can be short. Showing up without a pre-approval letter means you either rush the process — and make mistakes — or watch someone else close while you're still gathering bank statements.
Waiving the Inspection Contingency
Because bidding pressure in Brookings is lower than in competitive Oregon metros, there's rarely a good reason to waive inspections. Coastal homes face real exposure: wind-driven moisture, foundation drainage issues, aging septic systems, and seismic zone disclosures are all part of the picture here. Skipping a sewer scope or well inspection on a Harbor property to speed things up is a gamble that has cost buyers significantly in deferred repairs. Keep your inspection contingency — it's the right call in this market.
Underestimating the Insurance Timeline
This is the mistake that surprises first-time buyers the most. Coastal wind and flood exposure make homeowners insurance harder to place in Brookings than in an inland Oregon city, and the statewide insurance market has tightened considerably in recent years. Buyers who wait until two weeks before closing to shop insurance risk delaying funding — or scrambling into Oregon's FAIR Plan, which provides basic dwelling coverage only and at higher premiums than the standard market. Start the insurance conversation before you're fully under contract.
Ignoring the Geographic and Commute Reality
Brookings sits on a remote stretch of US-101, and the nearest larger employment centers are roughly 110 miles from Rogue Valley International-Medford Airport and about 20 minutes to Crescent City, CA. Buyers who purchase here assuming they'll commute regularly to Medford or Eugene for work — or that a larger retail and medical ecosystem is a short drive away — often find the isolation more significant than they expected at month six. If your income depends on an employer outside Curry County, be clear-eyed about what that drive actually means before you're committed to a mortgage. See the full picture on living in Brookings before you finalize your decision.
Local Expert Takeaway: Brookings rewards first-time buyers who do the preparation work before they fall in love with a listing. The market is not frenzied — homes generally sell near asking price, and you have room to negotiate and conduct thorough due diligence. What catches buyers off guard is the combination of thin inventory, coastal-specific inspection requirements, and an insurance market that needs more lead time than most people expect. Get your pre-approval from a lender familiar with Curry County, line up an inspector with coastal experience, and start shopping homeowners insurance the day your offer is accepted. Do those three things and you're ahead of most first-timers who arrive here from California or the valley thinking this is a simpler transaction than it actually is.
Quick Takeaways & FAQs
✅ Homes in Brookings sell at approximately 97% of asking price, giving first-time buyers genuine room to negotiate and conduct full due diligence without competing in bidding wars.
⚠️ The typical home price of $486,371 (July 2026) exceeds what the city's median household income can comfortably carry, so budget clarity before you tour is essential — not optional.
📍 Coastal wind and flood exposure make homeowners insurance harder and slower to place in Brookings than in inland Oregon markets — start shopping insurance the week you go under contract, not the week before closing.
What is the FHA loan limit in Brookings, Oregon?
Do I need a pre-approval letter before making an offer in Brookings?
What inspections should I plan for when buying a home in Brookings?
How long does it take to close on a home in Brookings?
How does Brookings compare to nearby towns for home prices?
Moving to Oregon?
Tell us what you need help with and we'll connect you with local resources.
