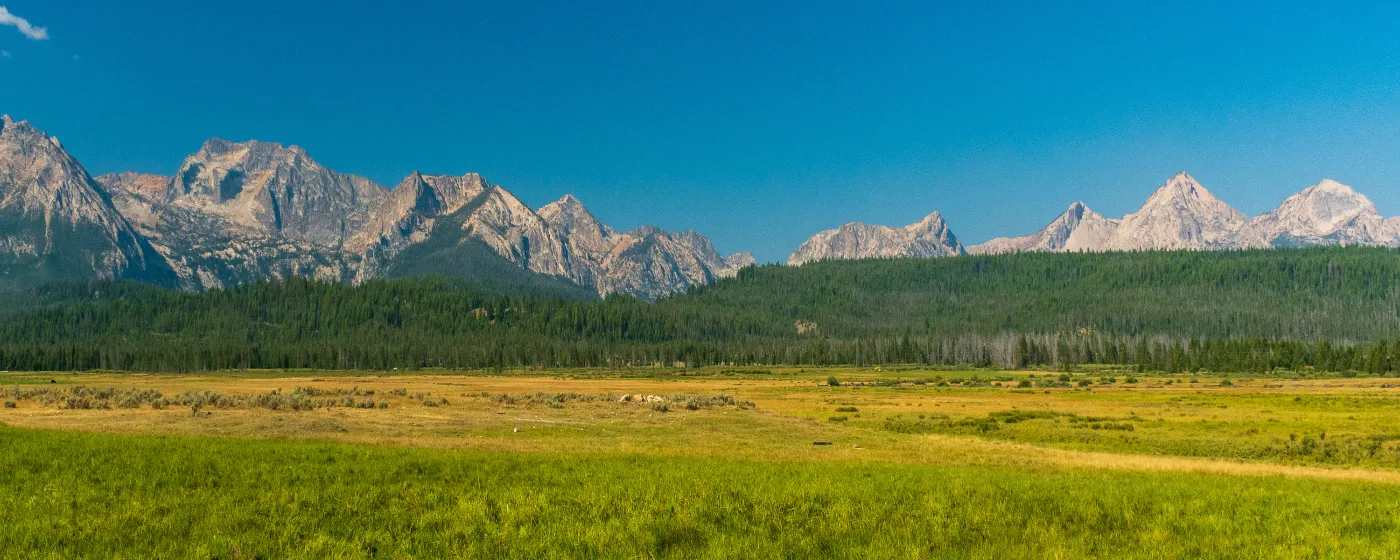
Maybe you've priced out Sun Valley and someone mentioned Stanley. Maybe you stumbled on a listing near Redfish Lake and couldn't believe what the acreage looked like compared to what you'd been browsing in Ketchum. Either way, here's the thing nobody leads with: Stanley has roughly 122 full-time residents and an extremely thin resale pool. At any given moment, there may be only one or two active listings in the entire town. That scarcity, combined with demand from second-home buyers and outdoor-lifestyle seekers, has pushed the Zillow Home Value Index to $582,736 as of May 2026 — a figure that sits well above what the local workforce earns. See the full cost-of-living breakdown for context on how that price compares to local incomes.
The economic engine here is almost entirely seasonal hospitality and federal land management. Redfish Lake Lodge, Mountain Village Resort, and the Sawtooth National Forest employ most of the year-round workforce. That seasonal rhythm matters to first-time buyers in two ways: your income picture must be convincing to lenders if it comes from this economy, and the homes that do hit the market tend to appear in spring and early summer, when the Sawtooth National Recreation Area corridor wakes up. Buyers who wait until July to start their search often find they've already missed the year's best options.
Cost of living here is counterintuitive. The property tax rate in Custer County is approximately 0.32%, among the lowest in Idaho, so the carrying cost on a home is relatively modest once you're in. The entry price is the barrier, not the ongoing taxes. Life at 6,200 feet elevation means real heating costs in winter, and the remote setting shapes everything from grocery runs to contractor availability. The tradeoff is access to the Salmon River, Stanley Lake, and one of the most dramatic mountain settings in the American West, with breakfast at Stanley Baking Company & Café on Wall Street before a morning on the water.
Whether you're seriously considering a purchase or still doing the math, the sections below walk through what a first-timer's budget actually buys in Stanley, the step-by-step process from pre-approval to closing, a plain-English budget snapshot, and the specific mistakes that trip up buyers who don't know this market.
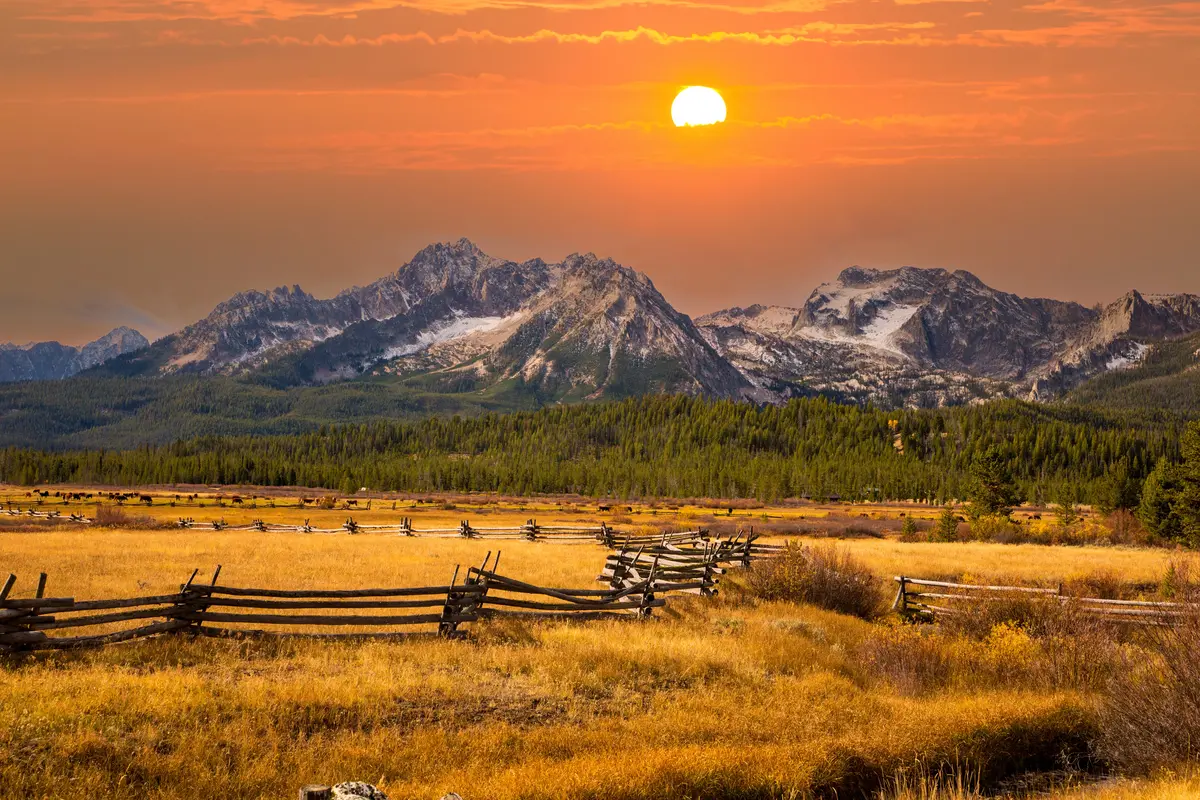
The Stanley First-Time Buyer Reality
The $582,736 Zillow Home Value Index figure (May 2026) tells part of the story. The rest is inventory. With a town of 122 people, the total pool of resale homes is so small that months can pass with nothing listed. When something does come to market near the Valley Creek corridor or the Ace of Diamonds Avenue area, it can draw interest from buyers who have been waiting for months — including cash-rich second-home buyers from Boise and beyond who don't need a lender at all.
For a first-timer financing the purchase, that competitive reality is the central challenge. Entry-level properties — older construction, smaller footprints, or lots requiring significant work — can start in the low-to-mid $400,000s, but they're rare and move fast. More typical listings in areas like Lower Stanley or near the Obsidian corridor come in closer to the city-wide median or above it. Buyers hoping to find a fixer-upper bargain well below $400,000 will likely be disappointed; this market doesn't produce many of those, and the ones that do appear often need substantial capital improvements on top of the purchase price.
Idaho statewide housing inventory grew roughly 18% year-over-year in Q1 2026 to about 2.8 months of supply — still a seller's market by most definitions. Stanley's supply is tighter than that statewide figure by a significant margin. First-timers need to walk in with their financing fully arranged, their must-haves clearly ranked, and the mental readiness to make a decision within days, not weeks.
The Homebuying Process in Stanley, Step by Step
Step 1: Get Pre-Approved — Before You Tour Anything
In a market this thin, showing up without a lender pre-approval letter is not just inefficient — it disqualifies you. Stanley sellers in a multiple-offer situation will not seriously consider an offer that arrives without a pre-approval in hand. Pre-approval means a lender has pulled your credit, reviewed your income documentation, and issued a letter stating a specific loan amount. Pre-qualification — a quick estimate based on self-reported numbers — is not the same thing and won't carry weight here.
Idaho lenders generally require a minimum 620 FICO score for conventional loans. FHA loans allow scores as low as 580 with 3.5% down, which matters for buyers with thinner credit histories. Shop at least two or three lenders — multiple credit inquiries made within a 45-day window count as a single inquiry on your report, so rate-shopping won't hurt your score. Thirty-year fixed rates for well-qualified Idaho borrowers were running approximately 6.0%–6.3% in late 2025 and are expected to remain in a similar range through 2026.
Step 2: Find an Agent Who Knows Rural Resort Markets
Stanley's transaction volume is low enough that most agents in Challis or Ketchum handle these sales. You want someone who regularly works Custer County rural properties, understands well and septic systems, and has experience with land parcels — because many Stanley listings include acreage, outbuildings, or access easements that require careful review. A general residential agent unfamiliar with these property types can miss things that matter.
Step 3: Shop — and Move Quickly
Set alerts on every major listing platform for Stanley and the surrounding Valley Creek and Redfish Lake area. When something appears, plan to tour within 48 hours. Given the distance from larger population centers, some buyers do virtual walkthroughs before making an in-person trip — ask your agent whether that's feasible for a given property, but don't skip the in-person visit before submitting an offer.
Step 4: Make a Clean, Complete Offer
In Stanley, a clean offer matters more than in most markets. Sellers here are often dealing with buyers they're skeptical about — will this person actually close, or will they get cold feet about the remoteness? A strong earnest money deposit (typically 1–3% of purchase price), a realistic closing timeline, and a pre-approval letter from a recognized lender all send the right signal. Escalation clauses can be useful if you expect competition, but confirm with your agent first.
Step 5: Inspection, Appraisal, and Closing
First-timers most often stumble here by underestimating what inspections reveal in rural properties. At 6,200 feet elevation, roofs, heating systems, and foundations face real weather stress. Budget time and money for a thorough general inspection plus, if the property has a well and septic system, separate inspections for both — those are non-negotiable in rural Idaho. The appraisal, ordered by your lender, independently values the home; if it comes in below purchase price, you'll need to renegotiate or cover the gap in cash. Closing costs typically run 2–5% of the purchase price on top of your down payment — plan for that cash to be liquid and ready.
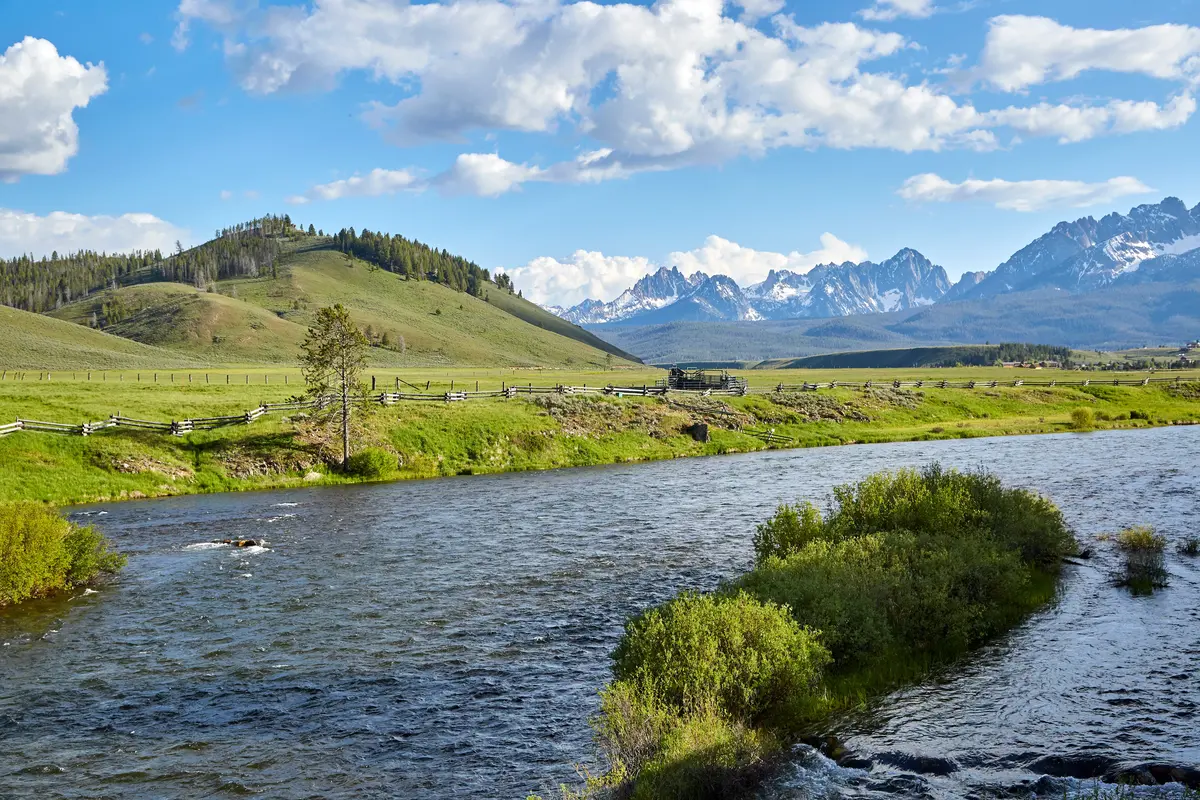
How Much Home Can You Afford in Stanley
The table below shows estimated cash needed at closing for several realistic purchase scenarios in Stanley's market. Closing costs are estimated at 2–4% of the purchase price — use the midpoint as your planning figure. These are approximations to help you budget; your actual numbers will depend on your lender, loan type, and negotiated terms. The interactive mortgage calculator below will let you model monthly payments for any of these scenarios.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (2–4%) | Est. Cash Needed at Table |
|---|---|---|---|---|
| FHA — 3.5% down, entry-level | $400,000 | $14,000 (3.5%) | $8,000–$16,000 | $22,000–$30,000 |
| FHA — 3.5% down, city median | $582,736 | $20,396 (3.5%) | $11,655–$23,309 | $32,051–$43,705 |
| Conventional — 3% down, entry-level | $400,000 | $12,000 (3%) | $8,000–$16,000 | $20,000–$28,000 |
| Conventional — 5% down, city median | $582,736 | $29,137 (5%) | $11,655–$23,309 | $40,792–$52,446 |
| Conventional — 10% down, city median | $582,736 | $58,274 (10%) | $11,655–$23,309 | $69,929–$81,583 |
| Conventional — 20% down, city median | $582,736 | $116,547 (20%) | $11,655–$23,309 | $128,202–$139,856 |
A 20% down payment eliminates private mortgage insurance (PMI), which meaningfully reduces your monthly obligation — but most first-time buyers in Idaho put down 5–10% and carry PMI until they've built enough equity to remove it. The FHA path requires only 3.5% down with a FICO score of 580 or higher, but FHA mortgage insurance premiums persist for the life of the loan unless you refinance into a conventional product later. VA and USDA loans offer 0% down for qualifying borrowers — if you or a co-borrower have military service or the property qualifies for a rural development loan, those programs are worth asking your lender about specifically.
Looking to buy in Stanley? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance.
Common First-Time Buyer Mistakes in Stanley
Skipping Pre-Approval Until After You Fall in Love with a Listing
This is the most predictable mistake, and it's especially costly here. Stanley listings don't wait. A buyer who tours a property on a Saturday, spends the following week getting pre-approved, and submits an offer the next Saturday will almost certainly find that the sellers have already accepted another offer — or that the listing is under contract. Get the pre-approval letter before your first tour, full stop.
Waiving the Inspection to Win a Bidding War
In some heated urban markets, buyers waive inspection contingencies to make offers more competitive. In Stanley, this is a significant risk. Rural properties at high elevation — with wells, septic systems, aging heating infrastructure, and roofs that face real snowload — can carry costly surprises. Waiving inspection to win is understandable in theory; in practice, a failed well or a cracked heat exchanger discovered after closing can cost more than you saved by winning. If the competition is that intense, consider negotiating a shorter inspection window rather than eliminating it entirely.
Underestimating the True Cash Requirement
First-timers consistently budget for the down payment and forget that closing costs — title insurance, lender fees, prepaid interest, recording fees — add another 2–4% on top. On a $582,736 purchase, that's a meaningful additional sum. Some lenders allow sellers to cover a portion of closing costs as a negotiated concession, but don't count on that in a seller's market. Go into the process with your full cash-needed-at-table figure liquid and in a verifiable account, because your lender will ask for proof.
Overlooking the Remoteness Factor Before You Commit
Stanley's setting is genuinely remote — and that reality hits differently after closing than it did during a summer weekend visit. Contractors willing to work at this elevation and distance from supply centers are scarce, which drives up repair costs and timelines. Grocery runs require planning. The buyers who thrive here have thought through the logistics of daily life at 6,200 feet before they sign; the ones who struggle are the ones who fell in love with the landscape and deferred those questions until after they owned the property.
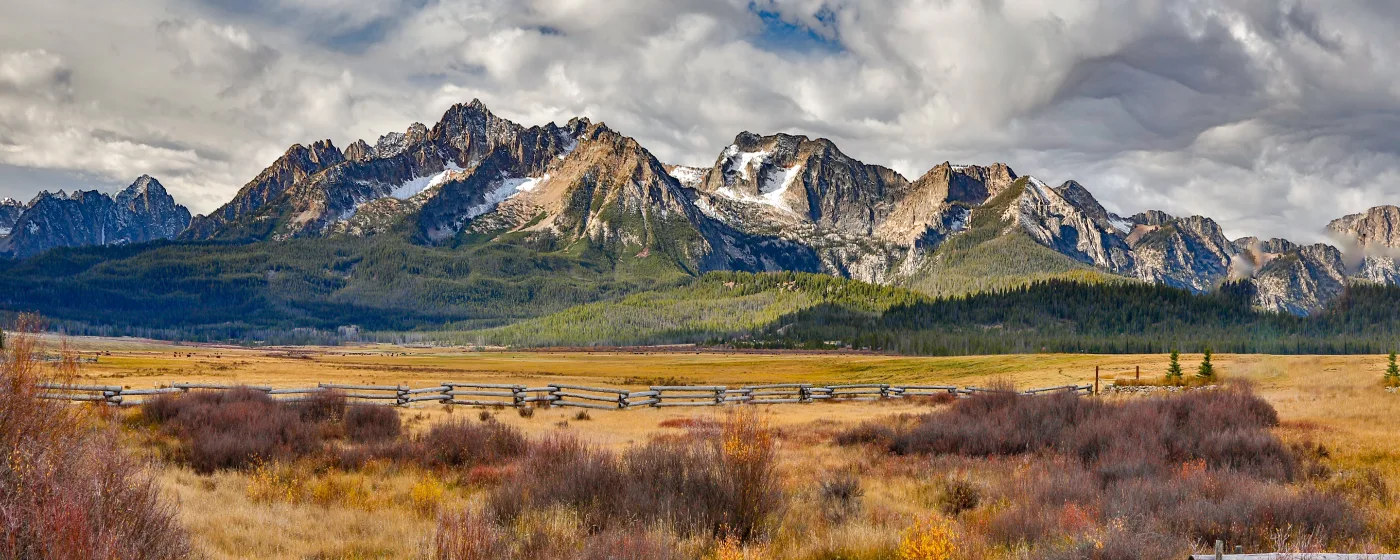
Local Expert Takeaway: Stanley rewards buyers who treat it like the low-inventory resort market it is — not the quiet rural town it looks like on a map. Get fully pre-approved before you set foot in a showing, have your well and septic inspection budget ready before you make an offer, and plan for closing costs on top of your down payment. The Stanley Baking Company & Café on Wall Street is as good a place as any to sit with your numbers before a weekend of touring — but once a listing appears near Valley Creek or the Ace of Diamonds Avenue corridor, you'll have days, not weeks, to decide.
Quick Takeaways & FAQs
✅ Custer County's effective property tax rate of approximately 0.32% means carrying costs stay low once you're past the purchase — one of the more buyer-friendly tax environments in Idaho.
⚠️ With only 122 residents and a handful of active listings at any given time, Stanley's resale market moves faster than almost anywhere in central Idaho — buyers who aren't pre-approved will lose to buyers who are.
📍 Rural properties at 6,200 feet elevation routinely require well and septic inspections on top of a standard general inspection — budget for all three before you make an offer, not after.
What credit score do I need to buy a home in Stanley, Idaho?
How many homes are typically for sale in Stanley at any given time?
Is the property tax rate high in Stanley?
Can I use an FHA loan to buy in Stanley, Idaho?
What are closing costs typically like in Stanley?
Moving to Idaho?
Tell us what you need help with and we'll connect you with local resources.
