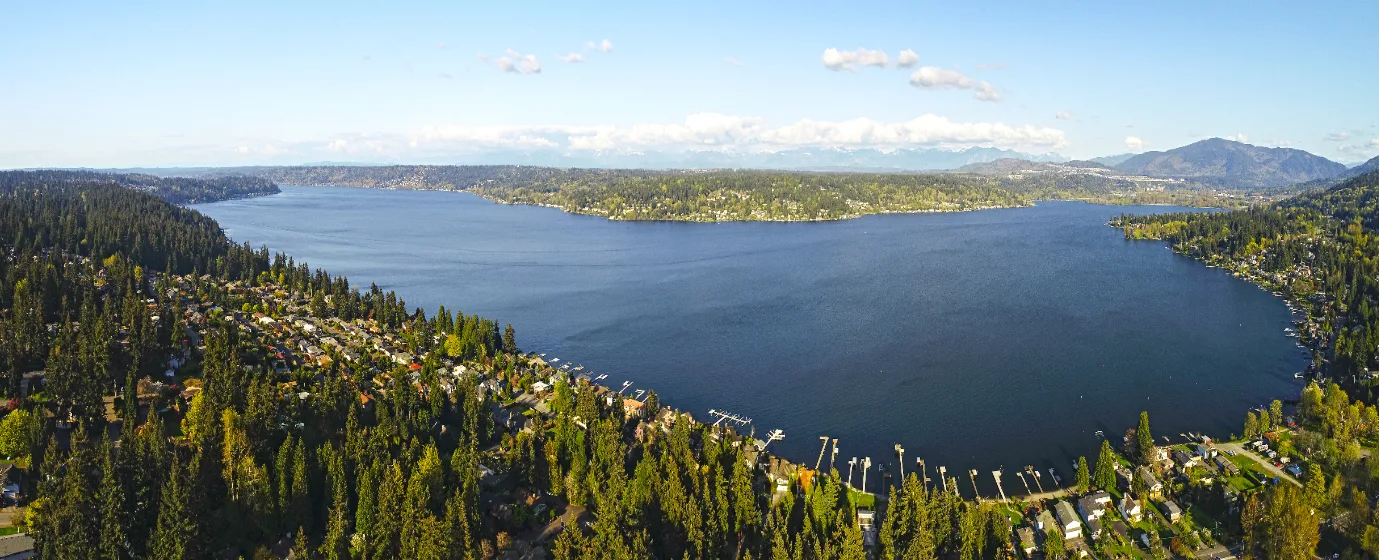
Maybe your company transferred you to Microsoft's Redmond campus and Sammamish kept coming up in conversations. Maybe you've spent a year watching Bellevue prices and someone suggested the Plateau as the more livable alternative at a similar price. Either way, the number that stops most first-timers cold is the Zillow Home Value Index figure for Sammamish: $1,461,158 as of June 2026. That's the median. The conversation about what a first-time buyer can actually do with that reality — not around it — is where this guide starts.
Sammamish is a planned, predominantly residential city of roughly 66,000 people sitting on a plateau between Lake Sammamish and the Cascade foothills, connected to Redmond via SR-202 and to Bellevue via the Issaquah-Pine Lake Road corridor. The district serving most of Sammamish is rated among the strongest in the state, and it's a direct factor in why entry-level inventory gets absorbed so quickly. The city's median household income sits at $239,690, which tells you something important about who your competition is when you make an offer.
Inventory has improved. Realtor.com showed 217 homes for sale in March 2026, up more than 28% year over year. But rising supply hasn't translated into softer competition on well-priced homes — Redfin reported a median of roughly five days to sell in spring 2026, and homes here average five offers. The market has softened from its tightest peak; it has not reset. First-time buyers who treat Sammamish like a buyer's market will lose repeatedly to buyers who understand they're still in a competitive one.
Whether you're just running the numbers or ready to submit your first offer, the sections below walk through what your budget actually buys here, the step-by-step buying process as it works locally, an affordability snapshot table, and the four mistakes first-timers make most often in this specific market.
The Sammamish First-Time Buyer Reality
The Zillow Home Value Index for Sammamish was $1,461,158 in June 2026 — one of the highest city-level medians in Washington State. That figure is not an outlier pulled by a handful of luxury sales; it reflects what a typical home on the Plateau actually trades for. For a first-time buyer, this means the down payment conversation starts at a different level than almost anywhere else you might have been considering.
Entry-level in Sammamish tends to mean older townhomes and smaller single-family homes, typically priced in the upper six figures to just over a million dollars. Condominiums exist below that band — a real option, but one that limits future flexibility and narrows attendance zone choices. Detached single-family inventory opens up meaningfully above $1,200,000.
The honest picture for most first-timers: this market rewards buyers who arrive with strong financing, a clear-eyed sense of their target price band, and the patience to lose a few offers before winning one. Waiting for a meaningful price correction is, as of 2026, a low-probability strategy — approximately five months of housing supply keeps the market tilted toward sellers, and the demand engine behind Sammamish pricing (tech employment on the Eastside) has not meaningfully weakened. Coming in with realistic expectations about what your budget buys — and what it doesn't — is the most useful preparation you can do before your first tour.
The Homebuying Process in Sammamish, Step by Step
Step 1: Get Pre-Approved — Not Just Pre-Qualified
In a market where sellers of $1.5M–$1.8M homes scrutinize buyer financing carefully, a basic pre-qualification letter is close to meaningless. You want a full pre-approval with underwriting started — credit pulled, income documented, assets verified. Sellers and their agents can tell the difference, and in a multiple-offer situation, the buyer whose financing has already been reviewed by an underwriter has a measurable edge.
Pre-approvals typically last 60 to 90 days. Time your application so the window aligns with when you're actually ready to make offers — not three months before you've even started touring. If your credit score is below 680, spending a few months pushing it higher before applying can save more money over the life of the loan than the delay costs.
Step 2: Define Your Price Band Before Touring
Sammamish is not one uniform market. Attendance zone assignments vary by street and shape both offer competitiveness and long-term resale value. Know which zone a home falls in before you fall in love with it — touring multiple neighborhoods without understanding how their zone boundaries differ is how buyers end up confused about why identical-looking homes attract very different levels of competition.
Step 3: Make Competitive Offers — Structure Matters
Well-priced homes here average five offers and go pending in roughly five to seven days. Your offer needs to be clean: pre-approval letter attached, earnest money at or above 1–3% of purchase price, and a short inspection period (five to seven business days is standard in this market). Escalation clauses are common on listings under $1.2M. Your agent should pull recent comparable sales in the specific area — price-per-square-foot can shift meaningfully across the Plateau.
Step 4: Inspection and Appraisal
Do not waive the inspection entirely. With homes built across four decades on the Plateau, an inspection is where you learn about deferred roofing, aging HVAC systems, and drainage issues specific to plateau topography. What first-timers often get wrong: confusing "waiving the inspection contingency" with "skipping the inspection." You can still have an inspection for informational purposes while removing the contingency — understand exactly what you're agreeing to before you sign.
Appraisals at this price level deserve attention. If you're financing at a purchase price above the appraised value, you'll need to cover the gap in cash or renegotiate. Know your appraisal contingency terms before the appraisal comes back.
Step 5: Closing
Washington State closing timelines typically run 30 to 45 days from mutual acceptance. You'll receive a detailed closing disclosure from your escrow and lender at least three business days before closing — read it against your original Loan Estimate and flag any fees that shifted. Budget for a final walk-through within 24 hours of closing to confirm the home's condition matches what you agreed to.
How Much Home Can You Afford in Sammamish
The table below shows approximate cash-to-close requirements at several realistic Sammamish price points. Closing costs are estimated at 2–3% of the purchase price, which is a typical range for King County transactions — your actual figure will depend on lender fees, title, escrow, and prepaid items. These are estimates for planning purposes only; the interactive calculator below this section will run your specific numbers.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (2–3%) | Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5%) — entry condo | $850,000 | $29,750 (3.5%) | $17,000–$25,500 | ~$47,000–$55,000 |
| Conventional (3%) — entry condo | $850,000 | $25,500 (3%) | $17,000–$25,500 | ~$43,000–$51,000 |
| Conventional (5%) — entry townhome | $1,050,000 | $52,500 (5%) | $21,000–$31,500 | ~$74,000–$84,000 |
| Conventional (10%) — entry single-family | $1,100,000 | $110,000 (10%) | $22,000–$33,000 | ~$132,000–$143,000 |
| Conventional (20%) — mid-range single-family | $1,400,000 | $280,000 (20%) | $28,000–$42,000 | ~$308,000–$322,000 |
| Conventional (20%) — upper Plateau tier | $1,600,000 | $320,000 (20%) | $32,000–$48,000 | ~$352,000–$368,000 |
One carrying cost first-time buyers consistently underestimate: property taxes. Sammamish's effective rate is approximately 0.82% — see the full cost-of-living breakdown for how that stacks against other ownership costs. Factor it into your monthly budget before you set your maximum purchase price.
Conventional loans require a minimum 620 credit score; FHA loans accept as low as 580 with 3.5% down. In practice, scores below 680 trigger meaningfully higher interest rates — and at Sammamish price levels, the rate difference compounds quickly over the life of the loan.
Looking to buy in Sammamish? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Sammamish quote.
Common First-Time Buyer Mistakes in Sammamish
Touring Before You Have a Real Pre-Approval
This is the most common and most costly mistake. First-timers tour homes around the Plateau, fall for a listing, and then scramble to get financing lined up — only to lose the home in the four days it takes to get a letter. Sellers in this market expect pre-approval documentation with offers, and listing agents call lenders to verify. Show up ready or you're practicing, not buying.
Waiving Inspection Without Understanding What That Means
In competitive offer situations, some buyers eliminate the inspection contingency entirely — meaning if serious problems surface, they have no contractual exit tied to the inspection. This is a different decision from declining to do an inspection at all. Skipping the inspection completely on an older Plateau home is how first-timers absorb $40,000 in deferred maintenance they didn't see coming. If you're removing the contingency to compete, at minimum pay for a pre-offer sewer scope and a quick walk-through with a contractor.
Ignoring Attendance Zone Boundaries Until After Falling in Love with a Home
Attendance zone boundaries don't follow neighborhood marketing names. Two homes on the same street can feed different schools. These boundaries affect how many buyers compete for a given listing and how the home performs at resale. Confirm the attendance zone through the district directly — not from the listing description — before you invest emotionally in a property.
Underestimating Total Cash Needed
First-timers routinely budget for the down payment and forget that closing costs, prepaid homeowners insurance, and prepaid interest add another 2–3% on top. At a $1,100,000 purchase price, that's an additional $22,000–$33,000 beyond the down payment. Add the earnest money deposit (typically 1–3% of purchase price, due within days of mutual acceptance), and you need that cash liquid — not in a retirement account, not in the process of being transferred. Running short on closing cash after mutual acceptance is an avoidable crisis that happens to first-time buyers in this market more than agents like to admit.
Local Expert Takeaway: Sammamish rewards prepared buyers and punishes reactive ones. The buyers who win here do three things before they tour their first home: they get a full pre-approval with underwriting started, they map out which attendance zones matter to them, and they've built a realistic cash-to-close number that includes closing costs on top of the down payment. The Plateau's competitive pace means a buyer who skips any one of those steps typically spends months losing offers before they circle back and do it right.
Quick Takeaways & FAQs
✅ Inventory rose more than 28% year over year in early 2026, giving first-time buyers more options than they had at the market's tightest point — though well-priced homes still average five offers and go pending in under a week.
⚠️ The $1,461,158 median home price (Zillow Home Value Index, June 2026) means even a 5% conventional down payment requires over $70,000 in cash before closing costs — budget conservatively and have funds liquid before you start touring.
📍 Attendance zone boundaries vary by street, not just by neighborhood name — confirm zone assignments directly with the district before committing to a specific area.
What credit score do I need to buy a home in Sammamish?
How long does it take to buy a home in Sammamish?
What is the minimum down payment for a home in Sammamish?
Is it worth waiting for Sammamish home prices to drop before buying?
What are closing costs in Sammamish and King County?
Moving to Washington?
Tell us what you need help with and we'll connect you with local resources.
