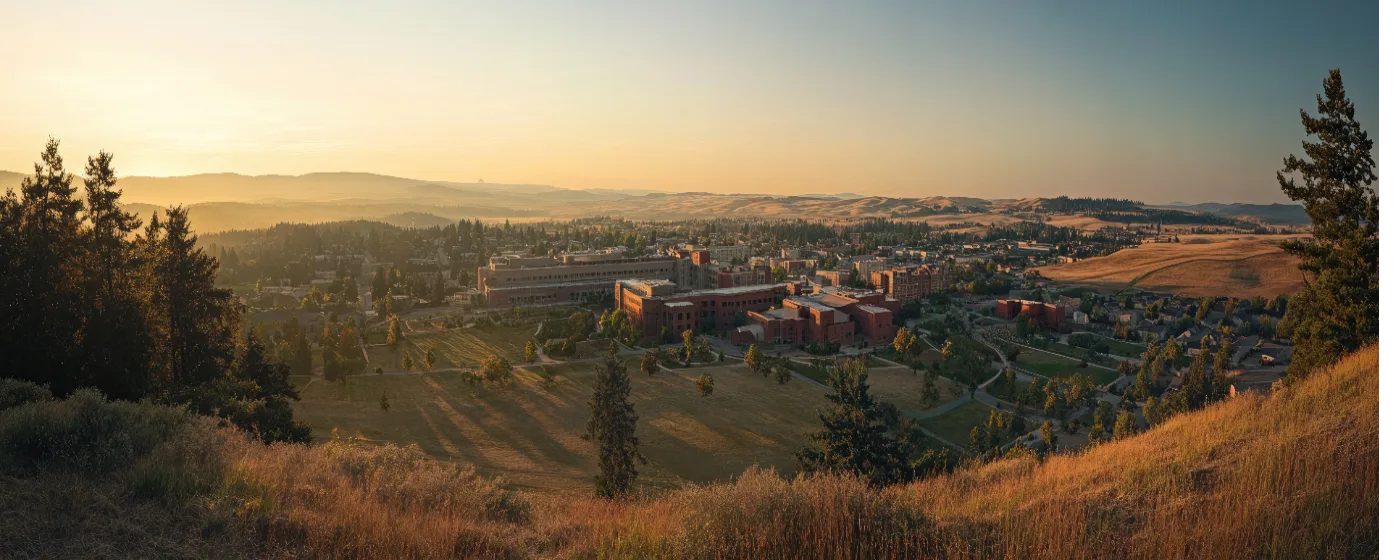
Maybe you've been renting near the Washington State University campus for a few years and finally want to stop watching your rent go up every August. Maybe you're joining WSU or Schweitzer Engineering Laboratories and someone told you Pullman is affordable enough to actually buy on a professional salary. That's mostly true — but the Pullman market is not as simple as the entry price suggests. The Zillow Home Value Index put the city median at $429,145 as of June 2026, noticeably below the Washington State median, yet the market scored 72 out of 100 on Redfin's competitiveness scale. You're not buying in a sleepy small town; you're buying in a university city where demand is structurally persistent and inventory is tight by geography.
The economic backbone here is WSU and Schweitzer Engineering Laboratories, and that shapes who buys and why. Faculty, staff, and engineers form a stable buyer pool that doesn't evaporate when interest rates tick up. New construction is limited — the Palouse hills and existing zoning leave little room to build outward — so resale homes are the primary path for most first-time buyers. That means you're competing for the same finite inventory as everyone else, and the homes that price within reach of a first-timer's budget tend to move fast. Median days on market fell to 19 days for the period ending May 2026, down from 35 days the prior year. That tightening is the defining reality of buying here for the first time. See the full cost of living breakdown for context on what your dollar does once you're in.
Washington's lack of a personal income tax is a quiet but real advantage for first-time buyers stretching to qualify. Compared to buyers in income-tax states, a household earning the local median can effectively keep more of each paycheck, which matters when every dollar of qualifying income counts. The trade-off is that property taxes carry more of the state's burden — worth understanding before you set your price ceiling. This guide covers the step-by-step buying process in Pullman, an honest budget snapshot with closing-cost estimates, and the specific mistakes that cost first-timers most in this market.
The Pullman First-Time Buyer Reality
The $429,145 Zillow Home Value Index figure (June 2026) is the number that draws people in, and it's real — but it's a median, not a floor. Entry-level homes, meaning older two-bedroom and three-bedroom houses in the more affordable pockets of the city, can start in the low-to-mid $300,000s, which is genuinely within reach for a dual-income household or a buyer with a solid down payment. The catch is that those homes surface infrequently and attract multiple offers quickly.
Competition is real but not irrational. Homes are selling at roughly 98.44% of asking price (early 2026 data), which means frenzied overbidding is not the norm — but lowball offers don't land either. With approximately 3.3 months of supply on hand, the market sits in balanced territory overall, yet specific price bands below $375,000 tend to feel much tighter than that number implies.
The seasonal calendar matters more here than in most markets. Because WSU drives so much of the city's housing demand, buyer competition peaks in late spring when the next academic year's arrivals are house-hunting. August through December is historically the more favorable window for first-timers — supply is higher, competition is lower, and sellers who didn't move their home during spring are often more flexible. If you can time your search to fall semester, you have a measurable advantage.
The Homebuying Process in Pullman, Step by Step
Step 1: Get Pre-Approved Before You Open Zillow
This is the step most first-timers in Pullman skip or do too late. With homes going under contract in a median of 19 days, showing up to a tour without a pre-approval letter is not just a weak position — it's effectively a disqualification when competing with any other interested buyer. A local in-person option is the Guild Mortgage branch at 245 E Main St, where a loan officer can walk through your documents face to face. Online lenders work too, but the pre-approval has to exist before you fall in love with a house on NE Stadium Way.
Step 2: Set Your Search Parameters Honestly
Talk to your agent about which Pullman neighborhoods fit your price ceiling, not just your wish list. College Hill properties near the WSU campus skew toward investor-owned rentals — great for a student, complicated for a first-time buyer who wants a clean owner-occupant purchase. Military Hill and Pioneer Hill tend to have more stable owner-occupied inventory. Define your price ceiling, your must-haves, and your deal-breakers before your first tour, not after your third.
Step 3: Make an Offer That Reflects the Market
Near-list-price offers are the expectation here, not the opening. Your agent should pull the last 90 days of comparable sales in the specific neighborhood before you write anything. Pullman is small enough that two blocks can mean a meaningfully different set of comps — don't rely on city-wide averages for individual offer decisions.
Step 4: Inspection and Appraisal — Don't Skip Either
The inspection contingency is the one most first-timers in competitive markets are pressured to waive, and it's rarely a good idea on a Pullman resale. Many of the entry-level homes here were built in the 1960s through 1980s, and deferred maintenance — aging roofs, older electrical panels, crawl-space moisture issues — is common. An appraisal contingency protects you if the contract price outruns the appraised value, which is less common in a balanced market but still happens.
Step 5: Close — And Budget for the Full Cash Requirement
Washington charges a Real Estate Excise Tax (REET) that the seller typically pays, but as a buyer you carry closing costs that usually run 2–3% of the loan amount. On a $430,000 purchase, that's roughly $8,600–$12,$900 in closing costs before your down payment. Have this cash available and documented before you make an offer — lenders will verify the source of funds, and last-minute scrambles to cover closing costs are one of the most common reasons Pullman deals fall apart in the final week.
How Much Home Can You Afford in Pullman
The table below shows five realistic first-time buyer scenarios at current Pullman price points. Closing costs are estimated at approximately 2.5% of the purchase price — a reasonable middle estimate that can vary based on your lender, title company, and any negotiated seller concessions. These are estimates; your lender will give you a Loan Estimate document with the precise figures for your transaction. The engine's mortgage calculator below the table lets you model your specific rate and term.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (~2.5%) | Approx. Cash Needed at Table |
|---|---|---|---|---|
| FHA minimum (3.5%) — entry range | $320,000 | $11,200 (3.5%) | ~$8,000 | ~$19,200 |
| FHA minimum (3.5%) — near median | $430,000 | $15,050 (3.5%) | ~$10,750 | ~$25,800 |
| Conventional (3%) — entry range | $320,000 | $9,600 (3%) | ~$8,000 | ~$17,600 |
| Conventional (3%) — near median | $430,000 | $12,$900 (3%) | ~$10,750 | ~$23,650 |
| Conventional (5%) — mid-range | $430,000 | $21,500 (5%) | ~$10,750 | ~$32,250 |
| Conventional (10%) — upper entry | $490,000 | $49,000 (10%) | ~$12,250 | ~$61,250 |
FHA financing is a practical option for buyers targeting the current Pullman median — the FHA loan limit for Whitman County was $472,030 for a single-family home as of 2025, covering the vast majority of what you'll find in active inventory. Ask your lender to walk through how assessed value history on any property you're considering may affect your ongoing tax obligation at the city's effective property tax rate.
Looking to buy in Pullman? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Pullman quote.
Common First-Time Buyer Mistakes in Pullman
Touring Without a Pre-Approval Letter
In a market where the median home goes under contract in 19 days, showing up pre-approved is table stakes. First-timers who spend two or three weekends touring before starting their pre-approval routinely lose homes they would have qualified for. Get the letter first. Every week without it is a week of real exposure to the market that costs you nothing but a few hours of paperwork.
Waiving the Inspection on an Older Resale
The pressure to waive inspection contingencies is real in competitive markets, but Pullman's entry-level housing stock is old. A 1970s house may look solid on the surface and reveal a compromised crawl space, an aging electrical panel, or a roof within two years of replacement on inspection. A $500 inspection fee is cheap insurance against a $15,000 surprise. If the competition requires waiving it entirely, consider a pre-offer inspection instead — legal in Washington and increasingly common here.
Ignoring the WSU Academic Calendar
Pullman's rental and resale market both move on the WSU clock. If you close on a home near campus in July or early August, you may discover that the neighborhood transforms dramatically in September — foot traffic, parking pressure, and noise change substantially when roughly 20,000 students return. This isn't a reason to avoid those areas, but it's information that should shape which block you buy on. Walk the street on a Tuesday in September, not a Sunday in July.
Underestimating Total Cash at Closing
First-timers consistently budget for the down payment and forget about closing costs, prepaid interest, homeowners insurance due at closing, and the initial escrow reserve. On a $430,000 purchase with a 3.5% FHA down payment, your total cash requirement is closer to $25,000–$28,000 — not the $15,050 the down payment figure suggests. This gap is the single most common reason pre-approved buyers in Pullman fail to close. Model the full cash-to-close number with your lender before you make an offer, not after you're under contract.
Local Expert Takeaway: Pullman is genuinely more accessible to first-time buyers than most of Washington State, but 'accessible' and 'easy' are not the same thing. The market moves fast — 19 days median — and the homes that price within a first-timer's reach go fastest. Time your search toward late summer or fall to catch the post-WSU-move-in dip in competition, get pre-approved at a lender like Guild Mortgage on E Main St before you tour a single property, and budget your full cash-to-close figure (down payment plus 2.5% in closing costs) before you write an offer. The buyers who struggle here are almost always the ones who arrived at the offer table surprised by one of those three things.
Quick Takeaways & FAQs
✅ Pullman's median home price sits noticeably below the Washington State median, making it one of the more accessible entry points for first-time buyers in the Pacific Northwest.
⚠️ Homes are moving in a median of 19 days — nearly half as long as the prior year — so buyers who aren't pre-approved before touring routinely lose properties they could have afforded.
📍 The WSU academic calendar creates a real seasonal buying window: late August through December brings more inventory and less competition, which is the opposite of what most first-timers expect.
What credit score do I need to buy a home in Pullman with an FHA loan?
Is Pullman a buyer's market or a seller's market right now?
When is the best time of year to buy a home in Pullman?
How much cash do I actually need to buy a home in Pullman?
Should I buy near WSU campus as a first-time homebuyer?
Moving to Washington?
Tell us what you need help with and we'll connect you with local resources.
