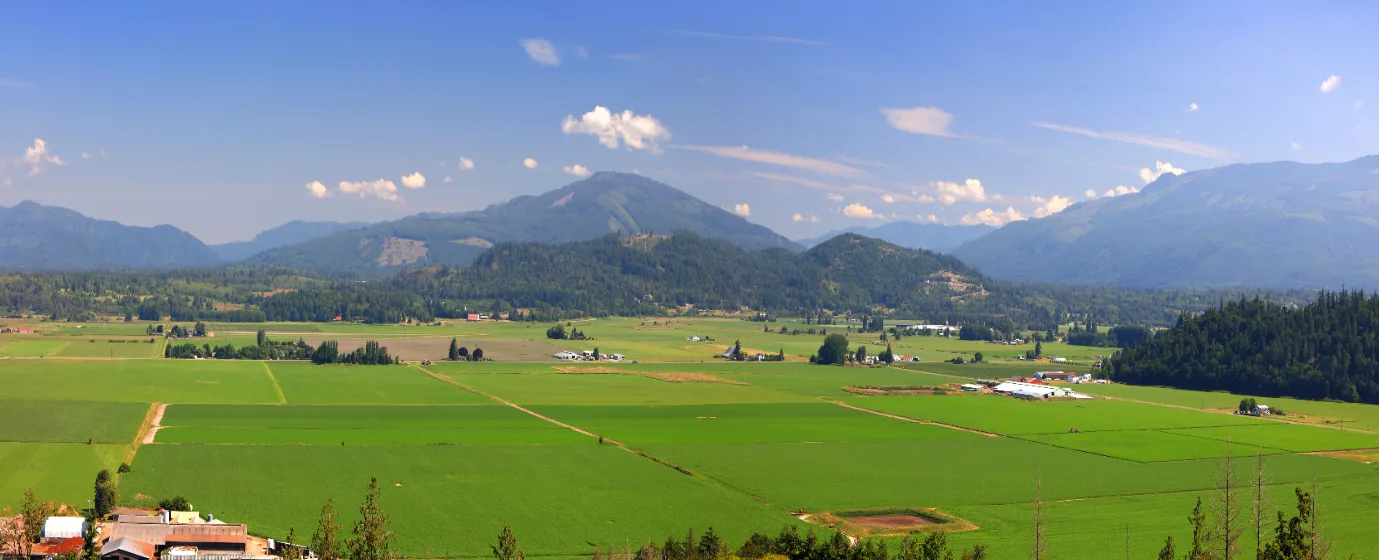
Maybe you've been priced out of Bellingham or Anacortes and someone mentioned Burlington. Maybe you're commuting from the Skagit Valley already and finally want to stop renting. Either way, Burlington has a way of surprising first-time buyers — not because it's cheap by any absolute standard, but because it's meaningfully more affordable than almost every other I-5 corridor city with a reasonable Seattle commute. The tradeoff is real: Burlington is a small city of roughly 11,000 people, 65 miles north of Seattle, and the inventory that hits the market here moves fast. Understanding that rhythm before you start touring homes is the difference between buying in six months and buying in two years.
The city's economic backbone runs through Skagit Valley College, Janicki Industries, and a cluster of regional employers that bring steady, mid-income households into the market each year. That demand base keeps Burlington from being a sleepy outlier; it's a working city with actual competition for entry-level homes. The Zillow Home Value Index (ZHVI) for Burlington stood at $489,679 as of July 2026 — noticeably below the statewide median — but that figure doesn't stay static, and it doesn't mean the buying process is easy. See the full cost-of-living breakdown for how that price fits into the broader picture.
What daily life in Burlington actually looks like matters for your budget, too. The city is functionally organized around I-5 and Burlington Boulevard, with grocery stores, the Burlington Plaza retail corridor, and most services within a short drive. The Skagit River Park and Railroad Park Amphitheater are gathering anchors for residents. After work, Railroad Pub & Pizza on S. Spruce Street is a reliably local spot where you'll run into neighbors — the kind of place that tells you something real about the size and character of the community you'd be joining.
Whether you're setting a budget for the first time or already have a pre-approval letter in hand, the sections below walk through what the Burlington market actually requires of a first-time buyer: what your money buys, how the process works locally, a concrete budget table, and the four mistakes that most often derail people before they get to closing.
The Burlington First-Time Buyer Reality
The Zillow Home Value Index for Burlington, WA sat at $489,679 in July 2026 — a figure that puts the city within reach for a dual-income household but demands honest math from a single-income buyer. That's the median across all home types; entry-level single-family homes in older sections of the city start closer to the low $400s, while newer construction pushes well past the median. Attached condominiums offer the lowest absolute price points in the city, often in the high $200s to mid $300s — a real option for buyers whose priority is getting into the market before prices drift further.
The competitive reality: homes here were selling after a median of approximately 27 days on market as of April 2026, down from 33 days the year before. That pace is faster than the statewide average and means first-timers don't have the luxury of slow deliberation. A move-in-ready home priced at or below median will typically draw multiple offers within the first weekend. Distressed or dated homes in the same areas tend to linger — but they carry renovation costs that a first-time buyer's budget rarely absorbs without friction.
The honest constraint is income. Burlington's median household income is $80,475, and at current rates a buyer putting 5% down on a median-priced home would carry a principal-and-interest payment that represents roughly 46% of that income — above what most lenders prefer for total housing costs. That's not a dealbreaker, but it means a larger down payment, a co-borrower, or targeting the lower end of the price range makes a meaningful difference in the quality of the monthly budget you'll be living with.
The Homebuying Process in Burlington, Step by Step
Step 1: Get Pre-Approved Before You Tour Anything
This is the step Burlington first-timers most commonly skip — or treat as optional. It is not optional here. With homes moving in under four weeks on average, showing up to a Saturday open house without a pre-approval letter means you're practicing, not buying. A lender will pull your credit, verify income and assets, and issue a letter that tells both you and the seller's agent that your offer is real. Do this before you set foot in a single house.
The Washington state average 30-year fixed rate was approximately 6.93% as of July 2026, per Curinos LLC data reported by Experian — slightly above the national average at the time, though individual lender quotes vary. Shopping at least three lenders before committing to one is worth the extra week.
Step 2: Define Your Non-Negotiables (and Know Your Boundaries)
Burlington is small enough that address-level details matter before you make an offer. If a specific attendance zone matters to your family, verify the exact boundary for that address with the district directly — a home two streets over can feed into a different building, and that's a detail worth confirming before you're in contract, not after.
Step 3: Make an Offer — and Know What's in It
A standard Washington purchase agreement includes a financing contingency, an inspection contingency, and an appraisal contingency. In a moderately competitive Burlington market, sellers will sometimes push back on timelines or ask for contingency waivers. The inspection contingency is the one first-timers most often feel pressured to waive — and the one that most often costs them money when they do. A pre-inspection (paid for by you, conducted before the offer) is an increasingly common middle path that satisfies the seller's desire for speed while keeping you protected.
Step 4: Inspection, Appraisal, and the Wait
A licensed home inspector in the Skagit Valley will typically charge $400–$600 for a standard single-family inspection. Expect the report within 24 hours. The appraisal — ordered by your lender, paid by you at closing — confirms the home's value supports the loan amount. If the home appraises below the purchase price, you either negotiate the price down, make up the difference in cash, or walk away.
Step 5: Closing
Washington is an escrow state, meaning a neutral third-party escrow company handles the closing process rather than an attorney. Closing typically runs 30–45 days from accepted offer. You'll do a final walkthrough within 24–48 hours of closing to confirm the property's condition hasn't changed since inspection. Closing day itself is largely paperwork and wire transfer — the keys come at the end.
Washington does not require homebuyer education for conventional financing, but the Washington State Housing Finance Commission (WSHFC) does require completion of a free course — available online through heretohome.org — for anyone using a WSHFC mortgage program. Even if you don't need it for your specific loan, the course is genuinely useful for first-timers navigating this process for the first time.
How Much Home Can You Afford in Burlington
The table below gives five realistic budget scenarios for a Burlington first-time buyer. Closing cost estimates reflect typical Washington state ranges (roughly 2–3% of purchase price for the buyer's side, including lender fees, title, escrow, and prepaid items). These are estimates for planning purposes — not lender quotes, and not inclusive of monthly property tax, insurance, or HOA costs, which the mortgage calculator below can help you model.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs | Cash Needed at Table |
|---|---|---|---|---|
| FHA — entry attached condo | $310,000 | 3.5% (~$10,850) | ~$6,200–$9,300 | ~$17,000–$20,150 |
| FHA — lower end, older SFR | $390,000 | 3.5% (~$13,650) | ~$7,800–$11,700 | ~$21,450–$25,350 |
| Conventional 3% — mid-range | $450,000 | 3% (~$13,500) | ~$9,000–$13,500 | ~$22,500–$27,000 |
| Conventional 5% — near median | $489,679 | 5% (~$24,484) | ~$9,794–$14,691 | ~$34,278–$39,175 |
| Conventional 10% — move-in ready SFR | $525,000 | 10% (~$52,500) | ~$10,500–$15,750 | ~$63,000–$68,250 |
| Conventional 20% — newer construction | $575,000 | 20% (~$115,000) | ~$11,500–$17,250 | ~$126,500–$132,250 |
A 20% down payment eliminates private mortgage insurance (PMI), which adds meaningfully to a monthly payment at 3–5% down — factor that cost into any comparison between scenarios. Also worth knowing: Washington's definition of first-time homebuyer is broader than most people expect. If you haven't owned a primary residence in the past three years, you may qualify as a first-time buyer for state program purposes even if you owned a home before.
FHA loans accept credit scores as low as 580 for the 3.5% down path, making them the most accessible entry point for buyers whose credit profiles aren't yet at conventional thresholds. Conventional financing typically requires a score of approximately 620–660 and a debt-to-income ratio near 36%, though individual lender requirements vary. The effective property tax rate in Burlington is approximately 0.82% annually — see the cost-of-living page for the full tax picture.
Looking to buy in Burlington? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Burlington quote.
Common First-Time Buyer Mistakes in Burlington
Mistake 1: Shopping Without a Pre-Approval Letter
In a market where well-priced homes go under contract in days, touring without pre-approval isn't just inefficient — it trains you to fall in love with homes you can't realistically compete for. Sellers' agents in Burlington will ask for your pre-approval before they even schedule a showing in some cases. Get it done first, then set your search radius.
Mistake 2: Waiving the Inspection Contingency on a Skagit Valley Home
The Pacific Northwest's wet climate means wood rot, moisture intrusion, and foundation drainage issues show up in older Burlington homes more often than buyers from drier markets expect. Homes in older sections near the floodplain carry additional risk that a standard listing photo won't reveal. Waiving your inspection contingency to win a bidding war is a reasonable strategy in some markets — it's a higher-stakes bet here. A pre-inspection before you write the offer is the smarter path when you feel competitive pressure.
Mistake 3: Ignoring the I-5 Commute Math
Burlington's position roughly 65 miles north of Seattle looks attractive on a map. In practice, the I-5 corridor south of Everett is among the most congested in the state, and buyers who model the commute on a Sunday afternoon get a very different picture than the Tuesday-morning reality. If you're planning to commute to Seattle regularly, drive or ride the route during actual peak hours before you commit to a purchase. The distance is real; the commute is longer than the mileage implies.
Mistake 4: Underestimating Cash Needed at Closing
Most first-time buyers focus on the down payment and forget that closing costs in Washington run an additional 2–3% of the purchase price on the buyer's side. On a $490,000 home, that's roughly $9,800–$14,700 on top of the down payment — cash that must be in your account and fully documented by the time escrow opens. Lenders will also verify that funds have been sitting in your account long enough to rule out undisclosed loans; moving large sums from a relative the week before you apply creates documentation headaches. Plan your cash position at least 60–90 days before you intend to make an offer.
Local Expert Takeaway: Burlington's entry point is real — but the cash requirement surprises nearly every first-timer. A buyer targeting the $390,000–$450,000 range with an FHA or 3% conventional loan needs $20,000–$27,000 liquid before they write a single offer, and they need that pre-approval letter in hand before they walk through a front door in any Burlington neighborhood. The market here moves in weeks, not months — and the buyers who close are the ones who treated the paperwork as the first step, not the last.
Quick Takeaways & FAQs
✅ Burlington's Zillow Home Value Index of $489,679 (July 2026) sits noticeably below the Washington state median, making it one of the more accessible I-5 corridor entry points for first-time buyers.
⚠️ Homes were selling in approximately 27 days on market as of April 2026 — fast enough that buyers who show up without pre-approval are effectively locked out of competitive listings.
📍 Washington's first-time homebuyer definition includes anyone who hasn't owned a primary residence in the past three years, so some repeat buyers who've been renting may still qualify for state mortgage programs.
What credit score do I need to buy a home in Burlington, WA?
How much cash do I actually need to buy a home in Burlington?
Is Burlington, WA a competitive market for first-time buyers?
What loan types are available for first-time buyers in Burlington?
Do I need to take a homebuyer education course to buy in Burlington?
Moving to Washington?
Tell us what you need help with and we'll connect you with local resources.
