You've done the math and Waco looks like it might actually work. At a typical home price of $197,359 (Zillow Home Value Index, July 2026), this is one of the few cities in Texas where a first-time buyer with a conventional income can still reach the finish line without an inheritance or a co-signer. But the median household income of $54,365 sits below what you'd need to carry the typical home comfortably — by roughly $13,000 — which means budgeting carefully from the start is not optional. The good news is that the gap is closeable with the right loan structure, and the market has shifted toward buyers in ways that weren't true two or three years ago.
Waco is a city of 147,788 anchored by Baylor University, a substantial healthcare sector, and a growing aerospace and defense presence through L3Harris Technologies. Those employers matter to first-time buyers for two reasons: they produce a relatively stable job market in a city with modest prices, and they drive steady demand for housing across a wide range of neighborhoods. The tourism pull of Magnolia Market at the Silos — which draws crowds from across the region and has reshaped real estate demand near downtown — means some entry-level neighborhoods have seen real competition even as the broader market has grown more balanced.
The market itself is more buyer-friendly than it was during the pandemic peak. Sellers are more often offering concessions to close deals, and the overall buying timeline from listing to closing runs roughly three months, so you have real time to think. Homes are still selling close to list price — approximately 98.4% — which means lowball offers don't land here, but you're not in a situation where every house goes to a bidding war the first weekend. That's a meaningful shift for first-timers who need time to think clearly. The best neighborhoods page breaks down how Waco's districts compare, and cost of living covers property taxes and ongoing ownership costs.
Whether you're relocating from Austin, Dallas, or somewhere out of state entirely, the sections below walk through what your budget actually buys in Waco, the step-by-step process for buying here, a budget snapshot table so you can see your cash needs at a glance, and the four mistakes that trip up first-timers most often in this market.
The Waco First-Time Buyer Reality
At a typical home price of $197,359 (Zillow Home Value Index, July 2026), Waco is genuinely affordable by Texas standards — noticeably below what you'd pay in the suburbs around Dallas or Austin. But affordability doesn't mean easy. The median Waco household income of $54,365 falls short of what most lenders want to see behind a purchase at the city's typical price point, so your debt-to-income ratio is the first number you need to understand before you tour a single house.
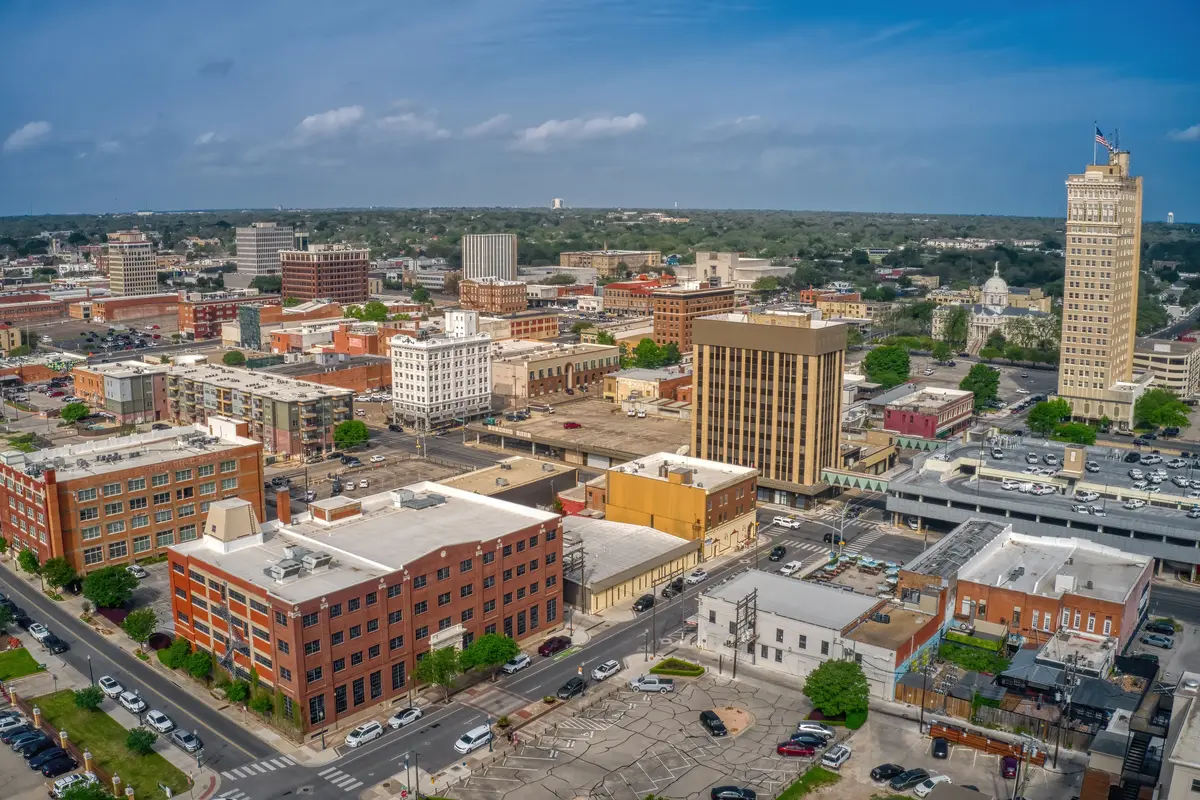
Entry-level inventory here clusters in North Waco and Brookview, both of which sit below the city-wide median in price. Those neighborhoods are where first-timers with tighter budgets tend to land first, and they're worth taking seriously — the trade-off is older housing stock that sometimes needs work, so budget for an inspection and don't assume a low list price means low total cost of ownership. Sanger Heights offers early-20th-century architecture and an established character that has made it a consistent draw for buyers who want walkable streets and proximity to downtown.
The Baylor and Downtown Waco neighborhoods both run above the city median. If you've got your eye on the energy near the university or the riverfront, be prepared for the price to reflect it. Preparation and pre-approval are the actual differentiators in a market where experienced buyers and investors remain active. Come in ready, not curious.
The Homebuying Process in Waco, Step by Step
Step 1: Get Pre-Approved Before You Open Zillow
This is not a formality in Waco. Sellers here are motivated, and many are offering concessions — but they still want to know you're a real buyer on day one. Get a full pre-approval letter (not a pre-qualification) from a lender before you schedule a single showing. The difference matters: pre-qualification is a self-reported estimate; pre-approval means a lender has pulled your credit, verified income, and committed to a loan amount.
Step 2: Find a Local Agent Who Knows McLennan County
Waco's neighborhoods vary dramatically within a short drive — what's happening near Lake Waco is different from what's happening in North Waco. An agent who knows the school boundaries, the flood zone maps along the Brazos and Bosque rivers, and which blocks have seen the most investor activity is genuinely worth the time to find. Don't default to whoever picks up the phone first.
Step 3: Shop With Your Pre-Approval Number, Not Your Dream Number
Your lender will tell you the maximum you qualify for. That is not your shopping budget — it's a ceiling, and Texas property taxes will eat into your monthly payment faster than buyers from low-tax states expect. The effective rate in Waco runs approximately 1.53%, layered across county, city, school district, and special district charges. Use the mortgage calculator on this page to stress-test different purchase prices before you fall in love with a house.
Step 4: Make an Offer That Respects the Market
Waco homes are selling at approximately 98.4% of list price. That means there's some room to negotiate — but not much. A well-structured offer at or just below list, with a reasonable earnest money deposit and clean terms, will outperform a lowball offer with a long list of demands almost every time. If you're asking for seller concessions toward closing costs (which many buyers do in this market), make sure your offer price reflects that ask rather than doubling down on both.
Step 5: Don't Skip or Soften the Inspection
Older housing stock in established Waco neighborhoods — craftsman bungalows in Castle Heights, mid-century homes in Sanger Heights — can carry deferred maintenance that doesn't show up on a listing photo. A thorough general inspection is non-negotiable. A sewer scope is worth adding for homes built before 1980. Budget the time and cost for both; the findings will either give you peace of mind or save you from a painful surprise.
Step 6: Homestead Exemption — File It the Day After Closing
Texas voters approved Proposition 13 in November 2025, raising the school district homestead exemption from $100,000 to $140,000 in taxable value. Filing with the McLennan Appraisal District is not automatic — you'll need a Texas driver's license or state ID showing your new address, and the deadline is April 30 of the tax year. The exemption also caps annual appraisal increases at 10% for your primary residence, which is a meaningful long-term protection. Missing the deadline is the single most common and most avoidable financial mistake first-time buyers make in their first year of ownership here.
Step 7: Close and Plan for Three Months
The full timeline from accepted offer to closing keys in your hand typically runs about three months in the current Waco market. Build that into your rental lease, your moving plans, and your cash reserves — running out of runway at the end because you didn't account for closing costs is more common than you'd think.
How Much Home Can You Afford in Waco
The table below gives you a practical look at cash needed at the closing table across several realistic purchase-price scenarios for Waco. Closing costs are estimated at 2–3% of the purchase price, which is a standard range for Texas — the actual figure varies by lender, title company, and negotiated seller concessions. These are estimates; use the mortgage calculator below for a payment estimate at current rates.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (2–3%) | Est. Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5% down) — entry level | $150,000 | $5,250 (3.5%) | $3,000–$4,500 | $8,250–$9,750 |
| Conventional (3% down) — entry level | $150,000 | $4,500 (3%) | $3,000–$4,500 | $7,500–$9,000 |
| FHA (3.5% down) — city typical | $197,359 | $6,908 (3.5%) | $3,947–$5,921 | $10,855–$12,829 |
| Conventional (3% down) — city typical | $197,359 | $5,921 (3%) | $3,947–$5,921 | $9,868–$11,842 |
| Conventional (5% down) — mid-range | $225,000 | $11,250 (5%) | $4,500–$6,750 | $15,750–$18,000 |
| Conventional (10% down) — above median | $260,000 | $26,000 (10%) | $5,200–$7,800 | $31,200–$33,800 |
A few things worth knowing before you anchor to a number. Texas has no state income tax, which frees up monthly cash flow compared with buyers relocating from states like California or Illinois. That said, the 1.53% effective property tax rate — a combined figure covering county, city, school district, and special district charges — is real, and it affects your monthly payment more than buyers from low-tax states typically expect. File your homestead exemption with the McLennan Appraisal District after closing; it reduces your taxable value and caps annual appraisal increases at 10%, both of which lower your long-term tax exposure in a meaningful way. For a deeper look at Waco's full cost of ownership, see the cost of living page.
Looking to buy in Waco? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Waco quote.
Common First-Time Buyer Mistakes in Waco
Mistake 1: Shopping Before You Have a Pre-Approval Letter
In a market where sellers are offering concessions, it's tempting to browse listings before you've talked to a lender. Don't. When a well-priced home in Sanger Heights or near the Baylor campus comes on the market, motivated sellers still move quickly on buyers who look ready. Showing up with a pre-qualification printout instead of a pre-approval letter has cost Waco first-timers real houses. The difference between the two is the difference between a seller taking you seriously and a seller waiting for the next call.
Mistake 2: Waiving the Inspection to Compete
Even with sellers offering concessions, waiving your inspection contingency to sharpen an offer is a bad trade in Waco. The city's older housing stock — particularly in Castle Heights, Sanger Heights, and parts of North Waco — can carry foundation issues, aging HVAC systems, or plumbing that looks fine on a walkthrough and isn't. A full inspection, and a sewer scope on older homes, is not a negotiating chip. It's the thing that keeps a $197,000 purchase from turning into a $197,000 purchase plus $30,000 in immediate repairs you didn't budget for.
Mistake 3: Ignoring School Boundary Realities
Waco Independent School District holds a D rating, according to the Texas Education Agency, and many buyers with school-age children use that rating to steer toward neighboring Woodway or Hewitt — both of which carry noticeably higher home prices than Waco. The boundary question matters here: a house one block from the Hewitt city limit may sit in a completely different district than the one next door, and addresses in the same ZIP code can feed into different schools. Verify the actual school assignment for any specific address before you make an offer, not after. For a fuller picture of the district, see the schools page.
Mistake 4: Underestimating Cash Needed at Closing
The down payment is the number most first-timers fixate on, but closing costs are what actually derail closings at the last minute. Budget 2–3% of the purchase price in closing costs on top of your down payment — title fees, lender fees, prepaid homeowners insurance, and prepaid property taxes are all real line items on a Texas closing statement. At the city's typical home price, that means you need meaningfully more cash on hand than just your down payment figure suggests. The table above gives you the combined totals for realistic Waco scenarios. Build in a cushion: running short by $1,500 a week before closing is a solvable problem if you planned for it and a crisis if you didn't.
Local Expert Takeaway: Waco is one of the few Texas markets where a first-time buyer with a realistic income can still get to the closing table without stretching into uncomfortable territory — but the math is tighter than the sticker price suggests. The homestead exemption filing with the McLennan Appraisal District is the single most important administrative step you'll take after closing, and most first-timers don't know it exists until their first tax bill arrives. Come in pre-approved, respect the inspection process in a city with a lot of older housing stock, and give yourself the full three-month timeline the Waco market actually runs on.
Quick Takeaways & FAQs
✅ Waco's typical home price of $197,359 (July 2026) is one of the most accessible entry points of any mid-size Texas city — giving first-timers real options that have largely disappeared in Austin and Dallas.
⚠️ The median household income falls short of what's needed to comfortably carry the typical Waco home, so your debt-to-income ratio and loan structure matter more here than the headline price suggests.
📍 Filing for the homestead exemption with the McLennan Appraisal District after closing — not automatic, due by April 30 — reduces your taxable value and caps annual appraisal increases at 10%, a protection most first-time buyers in Waco don't know about until their second year of ownership.
What is the typical home price for first-time buyers in Waco, TX?
How much cash do I actually need to buy a home in Waco?
How long does the homebuying process take in Waco?
What is the homestead exemption in Texas, and how do I file it in Waco?
Is Waco a good market for first-time buyers right now?
Moving to Texas?
Tell us what you need help with and we'll connect you with local resources.
