Maybe you've been renting in Austin and the math finally stopped working. Maybe you've been watching Georgetown from the outside — the historic square, the growth, the commute trade-off — and you're trying to figure out whether the numbers actually pencil out for a first-time buyer. The honest answer: they can, but not automatically. Georgetown is a city of 106,907 that has absorbed enormous growth without becoming cheap. The typical home price sits at $427,174 (Zillow Home Value Index, July 2026), and the median household income in the city falls below what you'd need to comfortably carry that mortgage. That gap is the central reality first-timers here have to plan around.
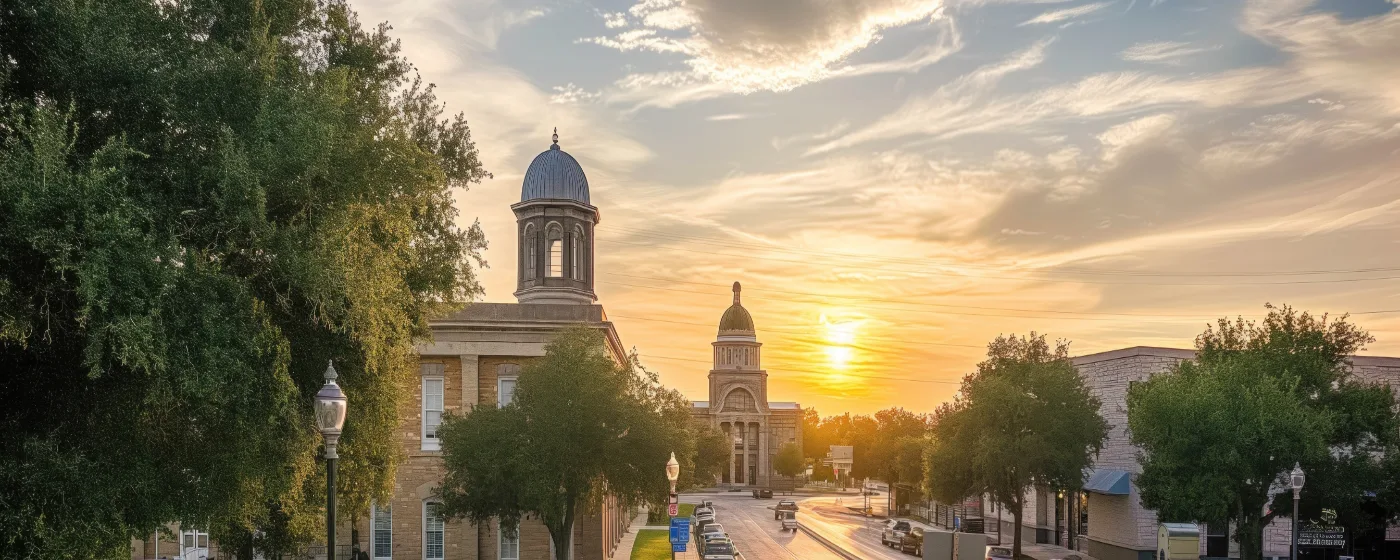
Georgetown's appeal isn't mysterious. The Williamson County Courthouse anchors a genuinely walkable downtown square, I-35 and SH-130 give commuters two routes into Austin, and the city's own property tax rate is the lowest among Austin-area cities with populations over 20,000. The Georgetown Independent School District — with 13,988 students enrolled in 2025-26 — holds a C rating, according to the Texas Education Agency, which matters for families with school-age children weighing this market against Round Rock or Cedar Park. The local employer base is expanding, with recently announced high-tech manufacturing commitments adding to the foundation of established institutions like Southwestern University and a regional hospital that serves the north Austin corridor.
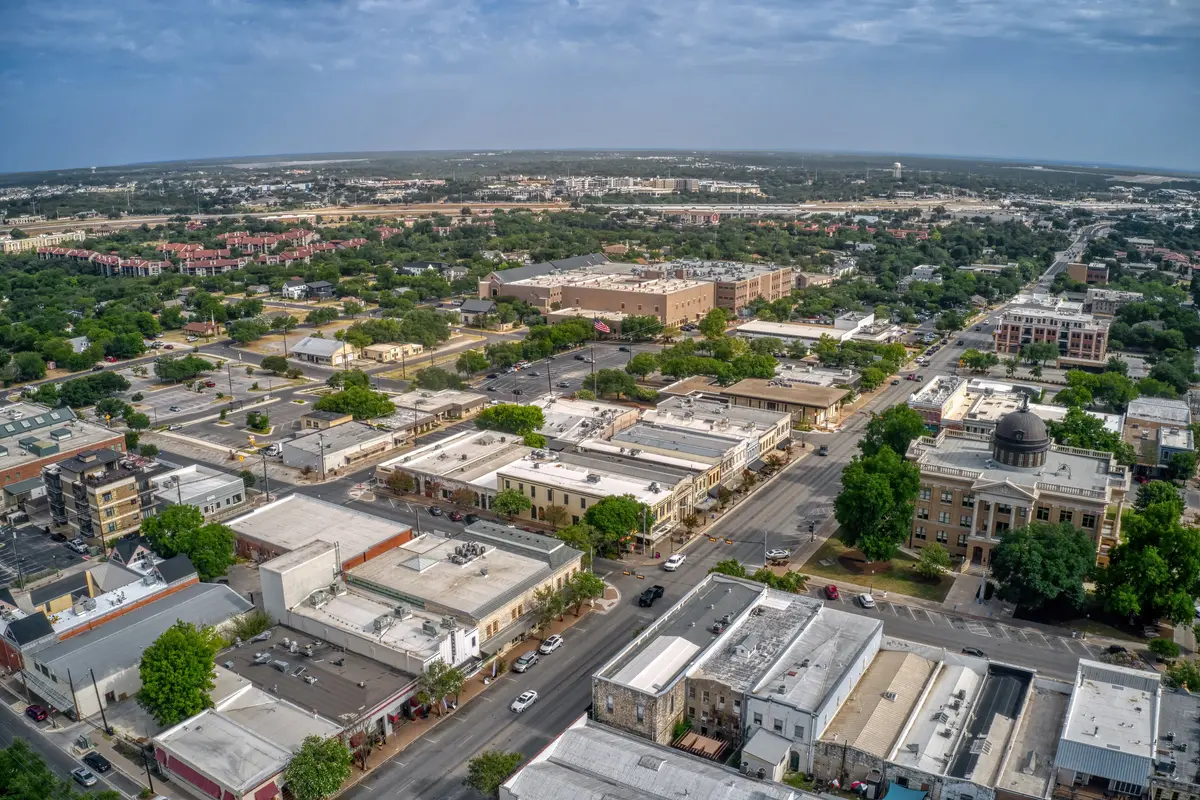
What first-timers often underestimate is the full ownership cost picture. The effective property tax rate of approximately 1.53% — layered from the city, Williamson County, and Georgetown ISD levies — is competitive for the Austin metro, but on a $427,000 home it is still a meaningful annual line item. The typical citywide rent runs $1,657 per month (Zillow, July 2026), which means the rent-versus-buy calculation is genuinely close for many buyers, depending on down payment size and current rates. Georgetown is also one of the most active new-construction corridors in Central Texas, so first-timers have both resale and builder inventory to consider — each with different contract terms and different risks.
Whether you're comparing Georgetown against Round Rock, Leander, or Cedar Park, or just trying to understand whether you can afford to stop renting, the sections below walk through what your budget actually buys here, how the Texas homebuying process works step by step, a concrete affordability table, and the specific mistakes that catch first-timers off guard in this market.
The Georgetown First-Time Buyer Reality
The typical home price in Georgetown is $427,174 (Zillow Home Value Index, July 2026). That figure puts Georgetown noticeably above Round Rock — which runs somewhat lower — and roughly in line with Leander, while sitting somewhat below Cedar Park. For a first-timer coming from Austin proper, those numbers can feel like relief. But the income math here is real: at the city's median household income of $95,062, carrying the mortgage on the city's median home requires careful planning, and many buyers are stretching, relying on a dual income, or buying below the median.
Entry-level inventory does exist, but it tends to cluster in specific pockets. Georgetown Village sits at the city-wide typical price point, making it one of the more accessible neighborhoods for buyers working near that median figure. Sun City Texas runs below the city median, though it is a 55+ community, so age-restricted purchases are the only way in. For buyers without those constraints, the realistic entry point into Georgetown's resale market often means smaller homes, older builds, or accepting a longer commute within the metro — and in many cases, looking at new construction in the city's outer corridors.
Georgetown is one of the most active new-construction corridors in Central Texas, and that matters for first-timers. Builder inventory has historically softened competition in some price ranges, and a planned master-planned community whose first phase was anticipated to begin in 2026 will add single-family homes, a walkable main-street district, 60 acres of parkland with a 4-mile trail, and a site reserved for a future Georgetown ISD high school. The catch: builder contracts are not the same as TREC resale contracts, and the earnest money and termination rights work differently. More on that in the mistakes section. For now, the key framing is this — Georgetown is achievable for a first-timer, but it requires an honest budget conversation before you start touring. See the full cost-of-living breakdown for the complete ownership cost picture.
The Homebuying Process in Georgetown, Step by Step
Get Pre-Approved Before You Schedule a Single Tour
This is the step Georgetown first-timers most often skip or do in the wrong order. In a market where sellers routinely receive multiple offers, showing up with a pre-qualification — a rough estimate based on a conversation — instead of a full pre-approval letter signals that you're not ready. A real pre-approval means a lender has reviewed your income documentation, pulled your credit, and verified your assets. Once you submit your documents, the process typically takes a few days to a week. The letter that comes out the other side sets your real number and tells a Georgetown seller that you can close.
Tour, Make an Offer, and Negotiate the Option Period
Texas has something most other states don't: the option period. Once your offer is accepted, you negotiate a window — typically 3 to 10 calendar days — during which you can walk away from the deal for any reason and recover your earnest money deposit. You pay the seller a separate, nonrefundable option fee for that right; if you proceed to closing, it gets credited toward your costs. This is the window when you get your inspections done. First-timers sometimes try to negotiate this period away to make their offer more competitive — that is almost always the wrong call, and the mistake section covers why.
Inspections, Appraisal, and Title
Use the option period to get a general inspection and any specialty inspections the property warrants — foundation, HVAC, roof condition. After the option period closes, the lender orders an appraisal to confirm the home's value supports the loan. Title work runs concurrently: the title company searches for liens or ownership issues and issues title insurance. These steps overlap, but first-timers often underestimate how much coordination they require in a short window.
Final Loan Approval and Closing
After the appraisal clears and underwriting issues a final approval, you'll receive a federal loan disclosure document at least three business days before your closing date. Review it carefully — line by line — against your earlier Loan Estimate. At the closing table, you'll sign the loan documents and wire or bring a cashier's check for your closing costs and down payment. From start to finish, a first-time purchase in Central Texas typically takes 10 to 14 weeks: roughly 2 to 6 weeks of active touring, followed by the lender's work, inspections, title, and final approval. Budget your timeline accordingly, especially if you're working around a lease end date.
One More Step That Trips People Up: Builder Contracts
If you're buying new construction — and in Georgetown, many first-timers are — the contract you sign is the builder's own form, not the standard TREC resale contract. Builders typically require 3 to 5 percent earnest money and often don't include a standard option period, meaning your termination rights are more restricted. Your agent and an attorney review matter more, not less, in a builder transaction.
How Much Home Can You Afford in Georgetown
The table below shows estimated cash requirements at closing for several realistic price points in Georgetown. Closing costs are estimated at 2–5% of the loan amount and shown as a range; your actual figure depends on lender fees, title costs, and any seller concessions you negotiate. These are estimates, not quotes — use them to stress-test your savings before you start touring.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs | Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5% down) — entry-level | $350,000 | $12,250 (3.5%) | $6,700–$16,800 | ~$19,000–$29,000 |
| Conventional (3% down) — entry-level | $350,000 | $10,500 (3%) | $6,800–$17,000 | ~$17,000–$28,000 |
| FHA (3.5% down) — city median | $427,174 | $14,951 (3.5%) | $8,200–$20,500 | ~$23,000–$35,000 |
| Conventional (3% down) — city median | $427,174 | $12,815 (3%) | $8,300–$20,700 | ~$21,000–$33,000 |
| Conventional (5% down) — mid-range | $475,000 | $23,750 (5%) | $9,000–$22,600 | ~$33,000–$46,000 |
| Conventional (10% down) — mid-range | $500,000 | $50,000 (10%) | $9,000–$22,500 | ~$59,000–$73,000 |
Every scenario above carries an ongoing tax obligation: at Georgetown's effective property tax rate of approximately 1.53%, annual taxes on a $427,174 home are a meaningful monthly line item — factor that into your budget alongside principal, interest, insurance, and any HOA dues. The interactive mortgage calculator below lets you model those monthly figures at current rates.
USDA and VA loans offer 0% down for eligible borrowers — rural-adjacent parcels in Williamson County may qualify for USDA, and active-duty and veteran buyers should ask their lender about VA eligibility before assuming a minimum down payment is required.
Looking to buy in Georgetown? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Georgetown quote.
Common First-Time Buyer Mistakes in Georgetown
Waiving the Option Period to Win the Offer
The Texas option period exists specifically to protect you. Waiving it entirely — or shortening it to 48 hours to look more competitive — leaves you no meaningful window to inspect the property and exit cleanly if something's wrong. A foundation issue in a home that's been through multiple Central Texas droughts is not hypothetical. Keep the option period, pay the fee, and use every day of it. The fee is credited back to you at closing if you proceed; the termination right disappears the moment the period ends.
Shopping Before Pre-Approval
Georgetown's desirable neighborhoods — Wolf Ranch, Berry Creek, Old Town — move. When a well-priced home appears, the buyers who are already pre-approved are the ones making offers. Touring first and scrambling to get a lender's letter after you've found the house you want is a reliable way to miss it. Beyond competition, the pre-approval conversation itself is valuable: it tells you whether FHA or conventional financing is the better fit for your credit profile and savings, which shapes which price ranges are actually realistic for you.
Ignoring School Boundary Details
Georgetown ISD serves the whole city, but which elementary school a home feeds into can vary even within the same neighborhood. For families with school-age children, this matters — and school boundaries do shift as the district grows. Georgetown ISD had 13,988 students enrolled in 2025-26 and the district is adding capacity; verify the specific feeder school for any address you're seriously considering, not just the general district assignment. The Georgetown schools page covers the district in more detail.
Underestimating the Total Cash Needed
First-timers routinely plan for the down payment and forget that closing costs are a separate, additional line item — typically 2 to 5 percent of the loan amount, due at the same closing table. On a $427,000 purchase with 3.5% down, the closing costs can easily match or exceed what you put down. Add in the nonrefundable option fee, the earnest money deposit (held in escrow, returned if you exit during the option period, but tied up in the meantime), and any prepaid items like homeowner's insurance and prepaid interest, and the true cash-to-close figure surprises almost every first-time buyer. Build a realistic cash reserve before you start the process, not after you're already under contract.
Treating a Builder Contract Like a Resale Contract
New construction is everywhere in Georgetown, and builders actively market to first-timers. But the contract you sign with a builder is their contract — not the standard TREC form Texas resale transactions use. The earnest money requirement is typically higher, the option period may not exist, and the termination provisions are more restrictive. Have a buyer's agent and, ideally, a real estate attorney review any builder contract before you sign. The builder's sales agent works for the builder.
Local Expert Takeaway: Georgetown's first-time buyer window is real but narrow: the typical home price of $427,174 (July 2026) requires careful planning against the city's median income, so your pre-approval number — not a wishlist — has to drive the search. The Texas option period is your best tool; use it to inspect thoroughly rather than waive it to win. And if a builder's community in Wolf Ranch or along the SH-130 corridor draws you in, read the contract carefully before you get attached to the floorplan — builder terms differ from resale in ways that matter.
Quick Takeaways & FAQs
✅ Georgetown's effective property tax rate of approximately 1.53% is competitive for the Austin metro, and the city's own rate is the lowest among Austin-area cities with populations over 20,000.
⚠️ At Georgetown's typical home price of $427,174, the city's median household income of $95,062 requires careful financial planning — first-timers should stress-test their budget before touring, not after.
📍 Texas's option period — typically 3 to 10 days — is a negotiated exit right unique to this state; using it fully for inspections is the single most important thing a first-time Georgetown buyer can do.
What is the minimum down payment to buy a home in Georgetown, TX?
How long does it take to buy a home in Georgetown from start to finish?
What is the Texas option period and how does it work in Georgetown?
What are property taxes like for a first-time buyer in Georgetown?
Is it better to buy new construction or resale in Georgetown as a first-time buyer?
Moving to Texas?
Tell us what you need help with and we'll connect you with local resources.
