You've done the math and Johnson City keeps coming up. The cost of living runs noticeably below the national average, the school district holds an A rating, according to Niche, and the Zillow Home Value Index put the typical home price at $295,339 in August 2026 — a figure that would be a down payment in many coastal markets. What the spreadsheet doesn't tell you is that the median household income here sits roughly $14,000 short of what it takes to comfortably carry the typical home, which means budgeting honestly matters more in Johnson City than the headline price suggests.
The city's economy is anchored by three large, stable institutions: Ballad Health, East Tennessee State University, and the James H. Quillen VA Medical Center. Healthcare practitioners make up more than 10% of local employment, well above the national share, and the partnership between ETSU and Ballad Health continues to deepen. That institutional backbone matters to a first-time buyer because it signals a job market that doesn't swing violently — the kind of stability that makes a 30-year commitment feel less risky. General Shale and Eastman Chemical (headquartered in neighboring Kingsport) add a manufacturing layer to the local economy.
Johnson City is a city of 74,943 that punches above its size on livability. BrightRidge, a locally-owned utility, delivers gigabit fiber broadband citywide — a genuine differentiator for remote workers. The Tweetsie Trail gives you 10 miles of paved greenway from downtown to Elizabethton. Wages average noticeably below the national figure, but a cost of living approximately 10% below the national average offsets much of that gap. Nearby Bristol and Elizabethton both carry noticeably lower typical home prices for buyers whose budget is tight and whose commute flexibility is real.
Whether you're shopping for your first home or still figuring out whether Johnson City makes sense for you, the sections below walk through what your budget actually buys here, the buying process step by step, a concrete affordability snapshot, and the mistakes that cost first-timers the most in this specific market.
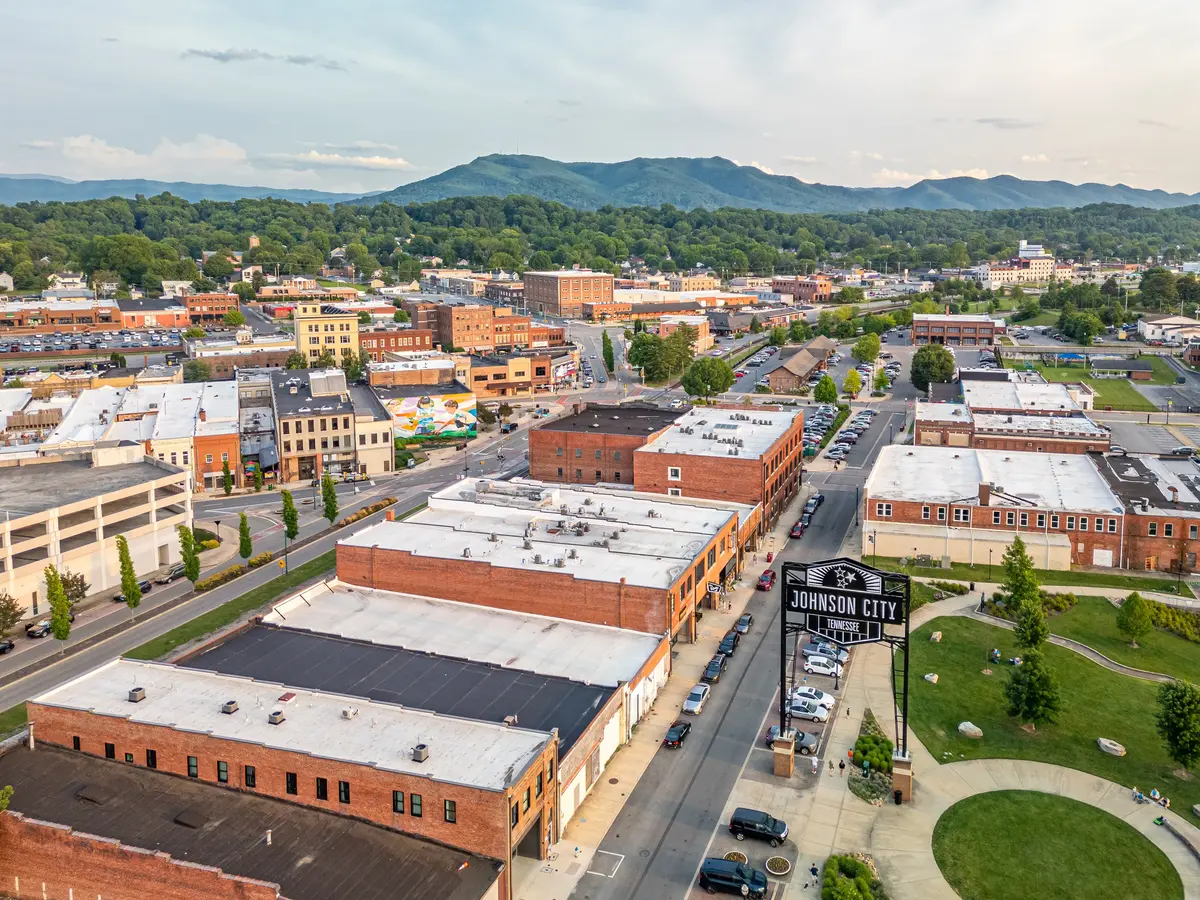
The Johnson City First-Time Buyer Reality
The typical home in Johnson City was priced at $295,339 in August 2026, according to the Zillow Home Value Index. That figure sounds attainable — and compared to most of the country, it is. But the honest entry point for a move-in-ready, single-family home in a desirable neighborhood runs higher than that median suggests, because the lower end of the market is often older construction, needs work, or sits in areas with longer commutes. First-timers who anchor their budget to the median and then shop without flexibility tend to get frustrated fast.
Mountain Home is the clearest example of where entry-level buyers can find real traction. Prices there run below the city median, the housing stock includes established single-family homes built across several decades, and proximity to East Tennessee State University and the VA Medical Center means the area has genuine long-term demand. It's not glamorous, but it's where a buyer with a disciplined budget can actually close.
The broader picture: Johnson City is not a frantically competitive market in the way that Sunbelt boom cities have been. Well-priced homes in good condition still attract serious attention, and sellers in established neighborhoods rarely discount without reason. Coming in pre-approved, with a realistic sense of what the low end of the market actually looks like, is the most important thing a first-timer can do before scheduling a single showing. For a full picture of how prices compare across the region, see the cost-of-living page.
The Homebuying Process in Johnson City, Step by Step
Step 1: Get Pre-Approved Before You Do Anything Else
This is not optional in Johnson City. Listing agents here expect a pre-approval letter — not a pre-qualification — attached to any offer. A pre-qualification is a five-minute phone estimate; a pre-approval means a lender has pulled your credit, verified your income documents, and issued a conditional commitment. Buyers who skip this step and fall in love with a home often lose it to someone who did the paperwork first.
Tennessee Housing Development Agency (THDA) programs, including a 30-year fixed-rate mortgage available to qualifying buyers with a minimum credit score of 640, are worth exploring before you commit to a conventional lender. THDA's definition of a first-time buyer includes anyone who hasn't owned a primary residence in the past three years — so prior homeowners are sometimes eligible. If you're a teacher, veteran, law enforcement officer, firefighter, or EMT, a separate THDA rate-reduction program may apply to you. Talk to a THDA-approved lender early, because their programs require a certified homebuyer education course to be completed before closing, and that course takes time.
Step 2: Define Your Search Before You Shop
Johnson City's neighborhoods feel meaningfully different from each other. The neighborhoods page breaks this down in full, but the practical point for a first-timer is: decide whether you're prioritizing walkability (Tree Streets, downtown), proximity to ETSU (Mountain Home), newer construction (Boones Creek, Lake Ridge), or entry price before you start touring. Touring randomly across the city wastes time and muddies your instincts.
Step 3: Make an Offer With Your Eyes Open
An offer in Johnson City typically includes an earnest money deposit, a financing contingency, and an inspection contingency. Waiving the inspection contingency to win a bidding situation is the single mistake that most often comes back to hurt first-timers here. Homes in the $250,000–$300,000 range frequently have deferred maintenance that isn't visible on a showing — older HVAC systems, roof age, crawl space moisture. A professional inspection is non-negotiable.
Step 4: Inspection, Appraisal, and the Closing Stretch
After the inspection, expect a negotiation. Sellers in this price range are often not in a position to do major repairs themselves, so requesting a credit toward closing costs in lieu of repairs is a common and effective approach. The appraisal — required by your lender — is ordered after the contract is executed and typically takes one to two weeks. If the home appraises below the purchase price, you'll need to renegotiate, pay the gap in cash, or walk away. FHA appraisals also include a basic habitability review, which can create additional negotiating points on older homes.
Closing in Tennessee typically runs 30–45 days from contract execution. Budget time accordingly, especially if your lease end date is fixed.
How Much Home Can You Afford in Johnson City
The table below lays out what different down payment structures and purchase price points mean in concrete cash terms. Closing costs in Tennessee typically run 2–3% of the purchase price and are labelled as estimates here. These figures are approximations — your lender will produce a Loan Estimate with the exact numbers once you're pre-approved. The interactive calculator below the table will let you model monthly payments at current rates.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs | Cash Needed at Table |
|---|---|---|---|---|
| FHA 3.5% | $200,000 | $7,000 (3.5%) | $4,000–$6,000 | ~$11,000–$13,000 |
| FHA 3.5% | $250,000 | $8,750 (3.5%) | $5,000–$7,500 | ~$13,750–$16,250 |
| FHA 3.5% | $295,000 (near median) | $10,325 (3.5%) | $5,900–$8,850 | ~$16,225–$19,175 |
| Conventional 3% | $250,000 | $7,500 (3%) | $5,000–$7,500 | ~$12,500–$15,000 |
| Conventional 3% | $295,000 (near median) | $8,850 (3%) | $5,900–$8,850 | ~$14,750–$17,700 |
| Conventional 5% | $350,000 | $17,500 (5%) | $7,000–$10,500 | ~$24,500–$28,000 |
Two things stand out from this table. First, even at the city-wide typical price, a first-timer using an FHA loan needs roughly $16,000–$19,000 in liquid cash — before moving costs, reserves, or repairs. Second, the gap between a 3% conventional down payment and a 3.5% FHA down payment is smaller than most buyers expect; what differs more is the mortgage insurance structure and the credit-score floor, which your lender can walk through in detail.
Tennessee's effective property tax rate of 0.43% is among the lowest in the country, which meaningfully reduces the monthly carrying cost compared to buyers coming from states like Illinois or New York. That low rate is part of why Johnson City's affordability picture looks better on a monthly basis than the purchase price alone implies. For the full tax and cost breakdown, see the cost-of-living page.
Looking to buy in Johnson City? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Johnson City quote.
Beyond the Monthly Mortgage Payment — What to Factor In
- The property tax rate above — The 0.43% used in the estimate is the median effective rate — tax actually paid as a share of market value — published by Ownwell, 2026. Half of local homes pay more and half pay less: your own bill depends on that property's assessed value and any exemptions it qualifies for, which can differ a lot from its market price. Confirm with the Washington County assessor before you budget.
- Total cost of ownership — Your monthly mortgage payment is just the baseline. Depending on the specific city, county, and service district, homeownership costs also include local utility fees, municipal surcharges, and special assessments (such as water, sewer, storm drainage, or local energy taxes) that vary by location.
- Independent due diligence — Because these recurring local costs and municipal fees change depending on the exact property address, buyers must research them independently during their transaction process.
Tax laws, local municipal fees, and utility costs change frequently and individual situations vary. This page is general information, not tax or legal advice — always consult a qualified tax professional, CPA, or local municipal offices for personalized guidance.
Common First-Time Buyer Mistakes in Johnson City
Mistake 1: Touring Before You're Pre-Approved
It seems harmless to browse open houses on a Sunday afternoon. In practice, first-timers who tour without a pre-approval letter consistently do two things that hurt them: they fall in love with a home they can't move on immediately, and they anchor their expectations to a price range they haven't actually verified. In Johnson City's market, a well-priced home in Mountain Home or Boones Creek at the right price can draw multiple offers. Arriving with documentation gives you a real shot; arriving without it means watching from the sidelines.
Mistake 2: Waiving the Inspection to Win
In competitive offer situations, some buyers are tempted to waive the inspection contingency as a goodwill gesture to the seller. This is the one contingency first-timers in Johnson City most often regret removing. The city's entry-level housing stock includes a significant number of homes built before 1980, and older construction in the region can carry crawl space moisture issues, aging knob-and-tube wiring in older pockets of the Tree Streets neighborhood, and HVAC systems that are functional but end-of-life. A professional inspection is the single most protective step in the process — the cost is real, but it's a fraction of what a missed foundation or roof problem costs after closing.
Mistake 3: Ignoring School Boundaries Until After the Offer
The Johnson City school district holds an A rating, according to Niche, and most buyers assume that means every address in the city feeds into equally strong schools. It doesn't. Elementary and middle school boundaries in Johnson City create real differences in which campus a child attends, and those boundaries don't always follow neighborhood lines cleanly. First-timers with school-age children should verify the exact school assignment for any address they're seriously considering — before the offer, not after. The schools page covers this in more detail.
Mistake 4: Underestimating Cash Needed at Closing
First-timers consistently underbudget for closing. The down payment gets the attention, but the closing cost line — typically 2–3% of the purchase price on top of the down payment — catches people off guard. On a $295,000 purchase, that's roughly $5,900 to $8,850 in additional cash due at closing, covering lender fees, title work, prepaid homeowners insurance, and initial escrow funding. Add a home inspection, and the total cash requirement is meaningfully higher than the down payment alone. Budget for all of it from the beginning, and don't drain your emergency fund to get to the table — owning a home almost always surfaces an unexpected expense in the first year.
Local Expert Takeaway: Johnson City's typical home price of $295,339 (August 2026) is genuinely accessible by national standards, but first-timers here do best when they come prepared: pre-approved before touring, realistic about entry-level inventory, and with enough cash reserves to cover the full closing picture and the first year of ownership. Mountain Home is the most reliable entry point for buyers with tight budgets. The school district's A rating is city-wide, but boundary assignments vary by address — verify before you offer. Tennessee's 0.43% effective property tax rate makes the monthly carrying cost look better than the purchase price alone suggests, and BrightRidge's gigabit fiber is a genuine quality-of-life asset if remote work is part of your household income equation.
Quick Takeaways & FAQs
✅ Johnson City's typical home price of $295,339 (August 2026) and Tennessee's effective property tax rate of 0.43% make monthly ownership costs noticeably more manageable than purchase price comparisons alone suggest.
⚠️ The median household income here sits roughly $14,000 below what it takes to carry the typical home comfortably — so budget planning and pre-approval need to happen before touring, not after.
📍 Mountain Home is the city's most reliable entry-level neighborhood for first-time buyers, with prices running below the city-wide typical and established housing stock close to ETSU and the VA Medical Center.
What credit score do I need to buy a home in Johnson City, TN?
How long does it take to close on a home in Johnson City?
Is it cheaper to buy in Johnson City or in nearby Kingsport or Bristol?
What are closing costs in Tennessee, and who pays them?
What is the THDA first-time buyer program and am I eligible in Johnson City?
Moving to Tennessee?
Tell us what you need help with and we'll connect you with local resources.
