Maybe your company is relocating you to the Portland metro and someone said Tigard is a reasonable alternative to Lake Oswego. Maybe you have been renting in Beaverton and a coworker mentioned that Tigard's prices run somewhat lower. Either way, the number that lands first is the Zillow Home Value Index typical home price of $607,011 (July 2026) — and for most first-time buyers, that figure requires an honest conversation about what you can actually afford, because the median household income in Tigard sits well below what it takes to carry that price at current rates. This guide is designed to close that gap between spreadsheet math and Tigard reality.
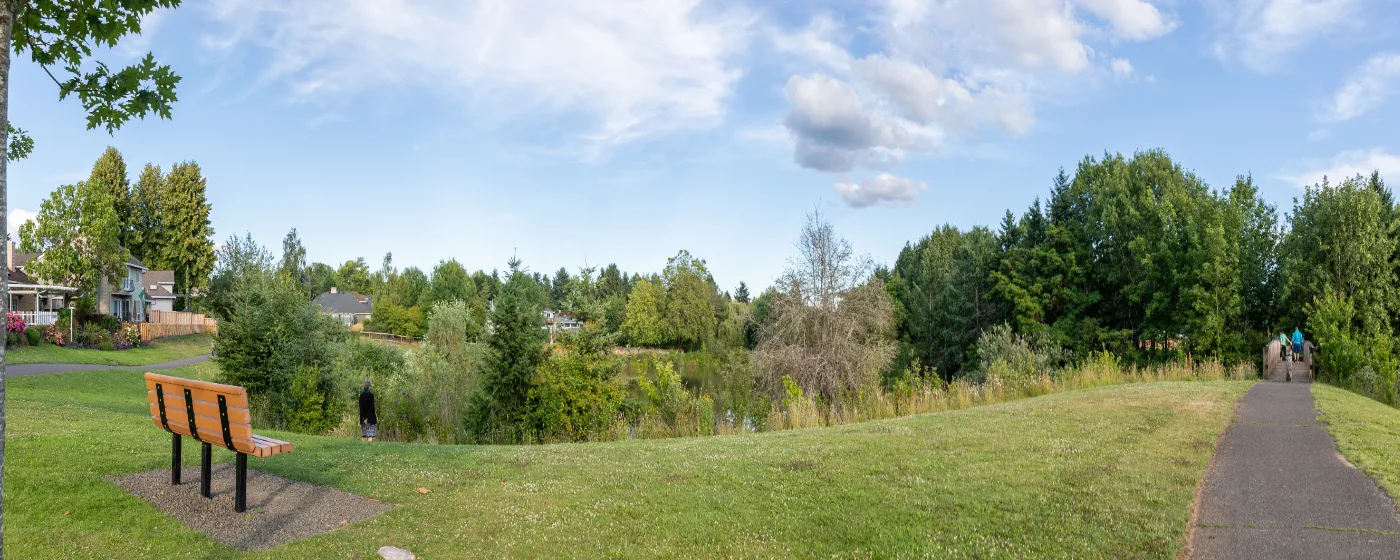
Tigard is the 11th-largest incorporated city in Oregon, with a population of 57,301 spread across neighborhoods that range from the established hillside streets of Bull Mountain to the still-developing subdivision rows of River Terrace. The Tigard-Tualatin School District 23J — which holds a B+ rating, according to Niche — draws a lot of families with kids into the market, and that demand is real and consistent. Major employers include Costco Wholesale and the district itself, and a significant share of residents commute about 20 minutes to Portland or to Nike's Beaverton campus, which shapes where buyers prioritize being in relation to I-5 and OR-217.
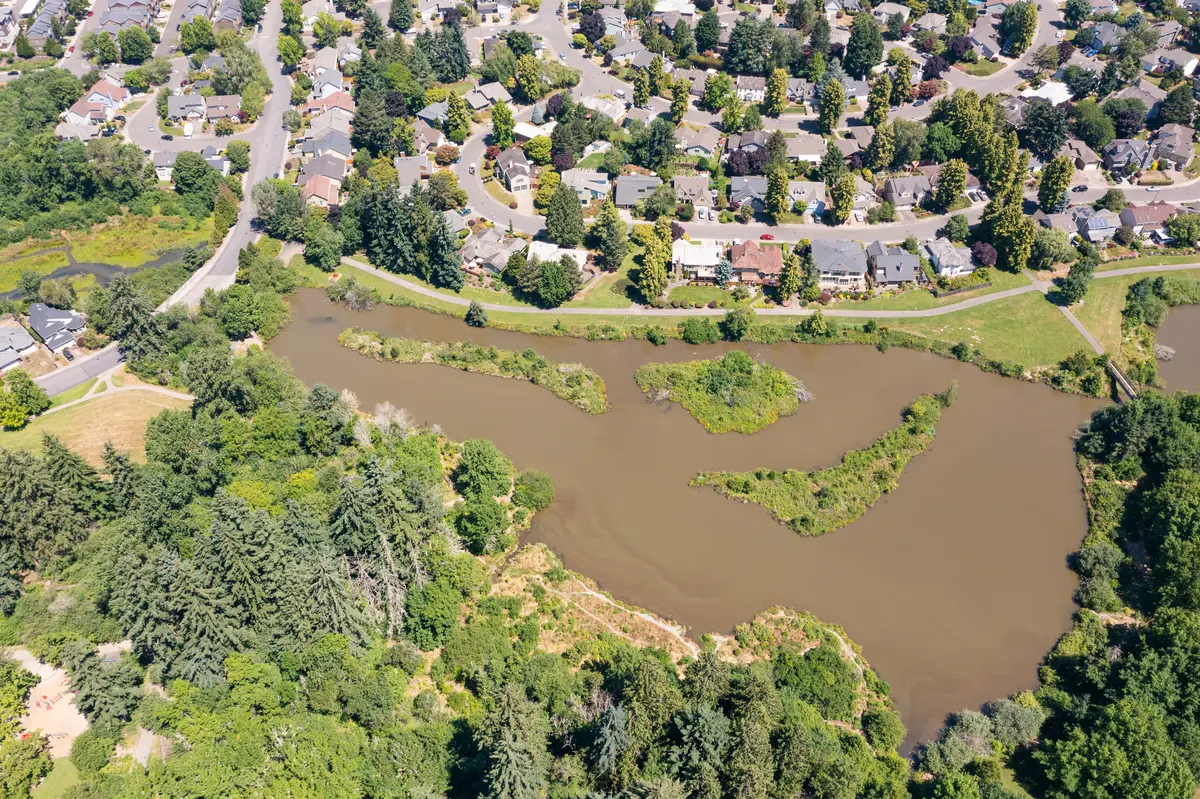
The cost of living in Tigard runs notably above the state average, driven almost entirely by housing. Entry-level inventory — meaning anything priced meaningfully below the city-wide typical — is limited and moves quickly when it appears. Southview tends to offer the most accessible entry points in the city; Tigard Triangle is evolving with mixed-use redevelopment underway on a former cinema site, and River Terrace continues to add new construction on the city's western edge. Fanno Creek Trail and Cook Park give the city genuine outdoor amenity without leaving town, and the WES Commuter Rail line at the Tigard Transit Center connects downtown Tigard to Beaverton and Tualatin on weekdays.
Whether you are just starting to research or already talking to lenders, the sections below break down what a first-timer's budget actually buys in Tigard, the step-by-step buying process, a concrete budget snapshot table, and the specific mistakes that cost local buyers the most.
The Tigard First-Time Buyer Reality
The Zillow Home Value Index puts Tigard's typical home price at $607,011 as of July 2026. That figure is not a ceiling — it is the midpoint. Entry-level homes, meaning older single-family construction or smaller townhomes in Southview or Metzger, can appear in the mid-to-upper $400,000s, but they attract multiple offers when they do. Budget accordingly, not optimistically.
The affordability gap here is real. Tigard's median household income sits at $108,823, and at that income level — even with a strong credit score and a disciplined savings rate — the math on a $600,000 purchase is genuinely tight at current rates. Most first-time buyers in this city either need a meaningful down payment to reduce the monthly obligation, a purchase price well below the city median, or both. There is no version of this market where those numbers disappear.
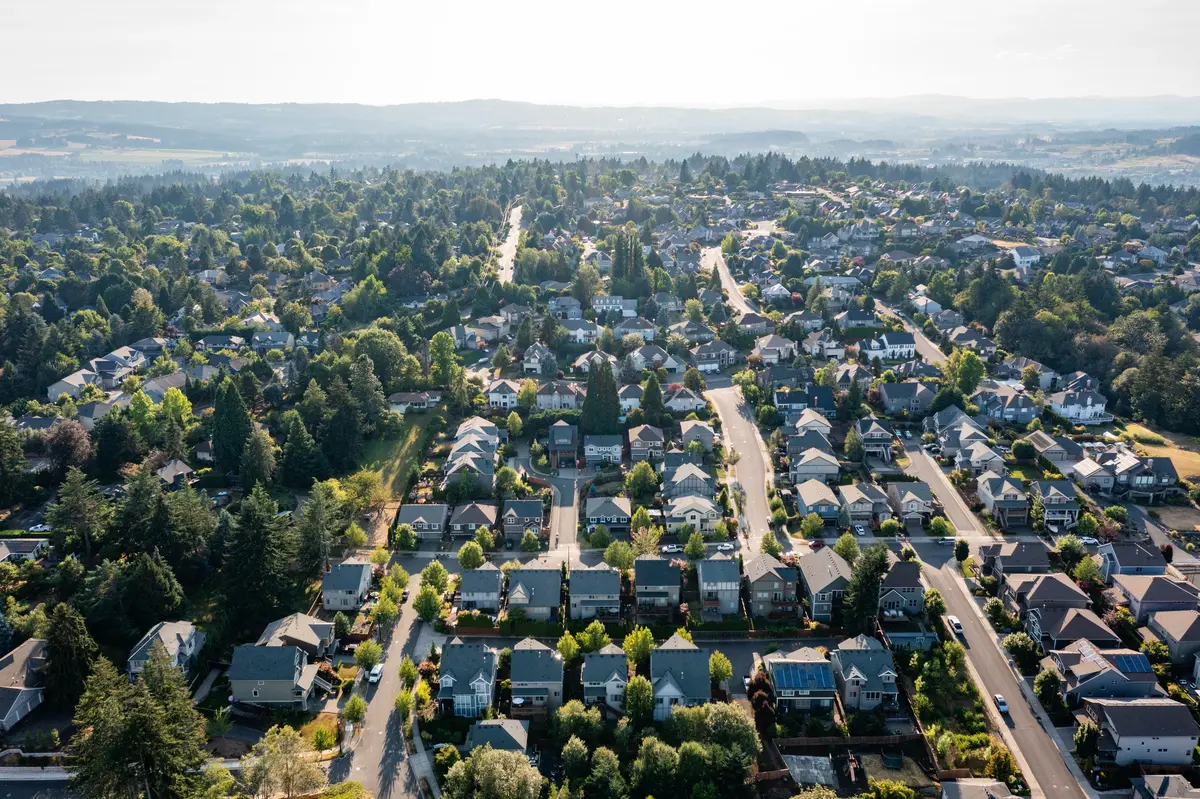
Among the neighborhoods where first-timers have the most traction, Southview prices below the city median — making it the clearest entry point in the city for buyers working with a tighter budget. Metzger offers accessible inventory and sits close to OR-217, though its price position relative to the city median is less uniform; treat it as a neighborhood worth exploring rather than a guaranteed discount. The Tigard Triangle runs above the median but is actively being redeveloped — the City of Tigard released a Request for Qualifications in August 2026 for mixed-use development on a former cinema site in the Triangle, which signals longer-term upside but also some near-term construction noise and transition. River Terrace offers new construction but comes with the trade-off of still-developing commercial infrastructure. Know which of those trade-offs you can live with before you start touring. For a fuller look at how Tigard compares to nearby King City, Beaverton, or Tualatin on price, see the cost of living page.
The Homebuying Process in Tigard, Step by Step
Step 1: Get Pre-Approved Before You Tour Anything
This is the step first-timers most commonly get backward in Tigard. In a market where well-priced homes below the city median attract serious competition, showing up to a tour without a pre-approval letter is not just inefficient — it means you cannot write an offer the same day, and in this market that matters. Pre-approval in Oregon typically requires recent pay stubs, W-2s, two years of tax returns, asset statements, current debt obligations, and a government-issued ID. Have all of it ready before you schedule your first showing.
Step 2: Define Your Search by Neighborhood Logic, Not Just Price
In Tigard, your neighborhood choice is also your commute choice. Buyers on Bull Mountain are not equidistant from I-5 and OR-217 the way someone in Metzger is. River Terrace buyers accept a longer drive to most commercial amenities in exchange for newer construction. Talk through the commute and daily life trade-offs with your agent before you fall in love with a specific zip code.
Step 3: Make an Offer That Accounts for This Market
Oregon is an escrow state, not an attorney-closing state, so your transaction will be managed through a title and escrow company. Your agent will draft the offer using an Oregon Real Estate Agency form. The two contingencies first-timers are most tempted to waive — inspection and appraisal — are also the two that protect you most. Waiving your inspection contingency to be competitive is a legitimate strategy in some markets; in Tigard, where housing stock ranges from 1970s-era construction on Bull Mountain to brand-new River Terrace builds, an uninspected older home carries real risk.
Step 4: Inspection, Appraisal, and the Gap Between Them
Oregon buyers pay for their own home inspection, and it happens after an accepted offer, typically within the first 10 days of the transaction. If the inspection surfaces issues, you negotiate repairs or credits — or you walk. The appraisal, ordered by your lender, establishes whether the property value supports the loan amount. If the appraised value comes in below your offer price, the lender will only finance based on the appraised figure. You will need to cover the gap in cash, renegotiate, or exit — so buying above asking price carries appraisal risk that first-timers often underestimate.
Step 5: Closing
Oregon buyer closing costs typically run 2% to 5% of the purchase price, covering lender fees, title and settlement charges, appraisal and inspection costs, prepaid homeowners insurance, property-tax prorations, and county recording fees. Federal law requires your lender to provide a closing cost summary at least three business days before your scheduled closing date — read it line by line and compare it against your original Loan Estimate. Surprises at the table are almost always traceable to items that were visible in that disclosure and overlooked.
How Much Home Can You Afford in Tigard
The table below models five realistic scenarios for first-time buyers in Tigard. Closing costs use a 2.5% estimate — a conservative midpoint of Oregon's typical 2%–5% range. These are estimates for planning purposes only; your actual costs depend on your lender, loan program, credit profile, and the specific property.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (2.5%) | Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5%) — entry level | $460,000 | $16,100 (3.5%) | $11,500 | ~$27,600 |
| Conventional (3%) — entry level | $460,000 | $13,800 (3%) | $11,500 | ~$25,300 |
| FHA (3.5%) — near city median | $575,000 | $20,125 (3.5%) | $14,375 | ~$34,500 |
| Conventional (3%) — near city median | $575,000 | $17,250 (3%) | $14,375 | ~$31,625 |
| Conventional (5%) — mid-range | $607,000 | $30,350 (5%) | $15,175 | ~$45,525 |
| Conventional (10%) — stronger position | $607,000 | $60,700 (10%) | $15,175 | ~$75,875 |
A larger down payment does more than reduce your monthly obligation — it can eliminate private mortgage insurance on a conventional loan and strengthen your offer in a competitive situation.
VA and USDA loans allow 0% down for qualified buyers. VA loans require documented military service; USDA loans require that the property fall within an eligible rural or suburban area, which some outer edges of Washington County may qualify for — ask your lender to run the address check. Ask your lender which first-time buyer loan options you qualify for, including any state or local programs currently available through participating lenders.
The interactive mortgage calculator below this section lets you model specific purchase prices, down payments, and rate assumptions — use it to stress-test the scenarios above against your own income and debt picture.
Looking to buy in Tigard? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Tigard quote.
Common First-Time Buyer Mistakes in Tigard
Touring Before You Have a Pre-Approval Letter
This one repeats because it costs buyers actual homes. A seller in Tigard reviewing multiple offers on a well-priced house in Metzger or Southview will not wait for you to schedule a lender call. Pre-approval is not a formality — it is your entry ticket to making an offer the day you find the right house.
Waiving the Inspection Contingency on Older Stock
Bull Mountain and Summerfield have significant inventory from the 1970s through the 1990s. Homes in that age range can carry deferred maintenance, aging sewer laterals, outdated electrical panels, and other issues that are invisible on a tour. Waiving your inspection to compete on price is a decision that experienced buyers sometimes make with full awareness of the risk. First-timers rarely have the contractor relationships or cash reserves to absorb what an uninspected older home might reveal after closing. Keep the inspection contingency.
Ignoring School Boundary and Commute Reality Until After the Offer
Tigard-Tualatin School District 23J serves the city, but school boundaries do not align neatly with neighborhood names. Families with school-age children sometimes close on a home in one part of Tigard expecting a specific elementary school, then discover the boundary runs one street over. Verify the boundary before you fall in love with a house, not after. Similarly, buyers who plan to commute to Portland via I-5 sometimes underestimate how differently that drive feels from River Terrace versus Metzger — check the commute page for context.
Underbudgeting the Cash Needed at Closing
Most first-time buyers anchor on the down payment number and treat closing costs as an afterthought. On a $575,000 purchase in Oregon, 2.5% closing costs add another $14,375 to what you need liquid on closing day — on top of your down payment, and separate from any reserve funds a lender may require you to keep in the bank. Run the full cash-to-close number, not just the down payment, before you decide what purchase price is realistic for you.
Treating the Tigard Triangle's Upside as a Certainty
The Tigard Triangle's Opportunity Zone designation and the August 2026 city RFQ for the former cinema site signal genuine long-term investment in that corridor. But redevelopment timelines are never predictable, and a first-time buyer counting on near-term appreciation from a specific project is taking on a risk that experienced investors size carefully. Buy the Triangle because the location and price point make sense for your life today — not because you are betting on a construction timeline you cannot control.
Local Expert Takeaway: Tigard's first-time buyer market rewards preparation more than almost anything else. The typical home price of $607,011 (July 2026) means the entry point into this city asks for real cash — and the buyers who succeed are the ones who arrive with a pre-approval letter, a clear-eyed read on which neighborhoods fit their commute and budget, and enough liquid savings to cover both the down payment and the closing costs without emptying the account. Southview is where first-timers find the most consistent traction below the city median; Metzger offers accessible inventory worth exploring. The Tigard Triangle is the neighborhood to watch for longer-term potential. And the WES Commuter Rail at the Tigard Transit Center is genuinely useful if your commute takes you toward Beaverton or Tualatin on weekdays — factor it into your location thinking before you narrow your search.
Quick Takeaways & FAQs
✅ Tigard sits about 20 minutes from Portland with WES Commuter Rail access from downtown, making it a practical base for westside metro commuters who want more space for the price.
⚠️ The typical home price of $607,011 (July 2026) runs above what the city's median household income can comfortably carry at current rates — first-timers need to budget for the full cash-to-close number, not just the down payment.
📍 Southview offers the clearest entry point below the city median, while River Terrace delivers new construction on the city's western edge in exchange for still-developing commercial amenities.
What credit score do I need to buy a home in Tigard, Oregon?
How competitive is the Tigard housing market for first-time buyers?
How much cash do I actually need to buy a home in Tigard?
Should I get pre-approved before looking at homes in Tigard?
Is River Terrace a good choice for first-time buyers in Tigard?
Moving to Oregon?
Tell us what you need help with and we'll connect you with local resources.
