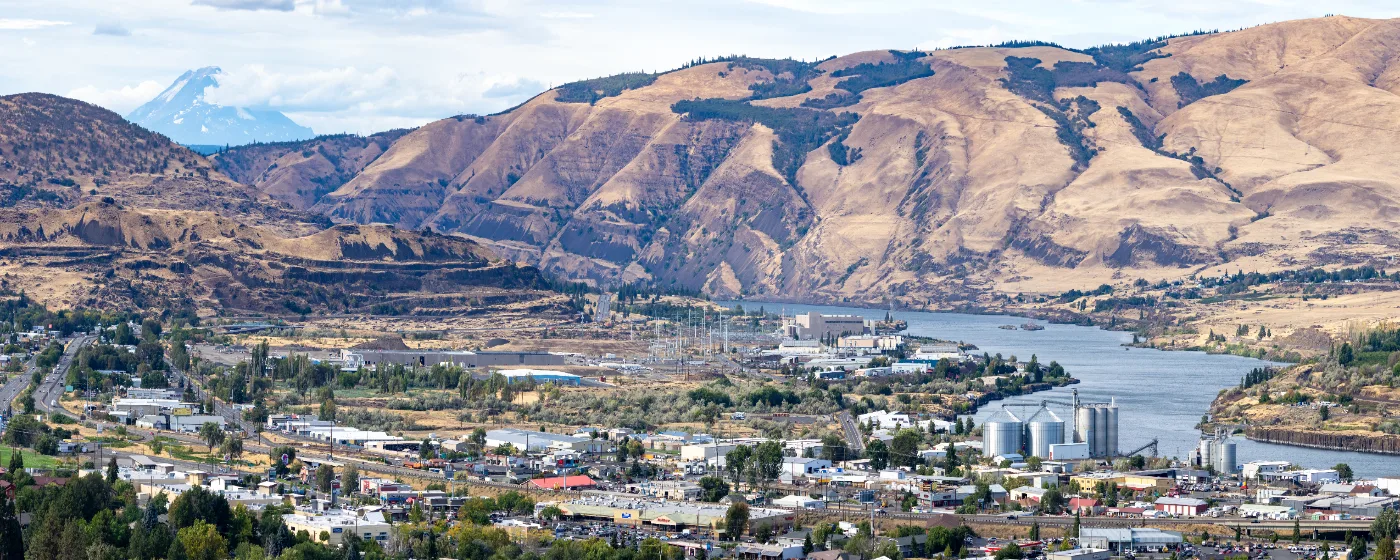
If you've been priced out of Hood River or watching Portland's market from the sidelines, The Dalles is probably the most underrated entry point left in the Columbia Gorge. A city of 15,917 tucked along the Columbia River where I-84 meets the high desert, it offers the kind of price point that still makes first-time ownership genuinely possible — not easy, but possible. The typical home here is $396,291 (Zillow Home Value Index, July 2026), a figure that sits noticeably below Hood River and well below the Portland metro. That gap is real, and it's why buyers who do their homework are showing up here.
The local economy is more stable than the small-population numbers suggest. Mid-Columbia Medical Center, the North Wasco County School District, Wasco County and City government, and Google's data center operation all anchor steady employment. That diversity matters for a first-time buyer: a single-industry town carries different risk than a place with a regional hospital, a school district, and a tech-sector anchor all writing paychecks. For many buyers, the commute to Portland — about 85 minutes along I-84 — is the genuine trade-off. It's a long drive for a daily commuter but workable for remote workers or those making the trip a few times a week.
Affordability here is real but not effortless. The median household income in The Dalles is $62,614, which falls short of what's needed to comfortably carry the typical home at current rates — a gap worth sizing honestly before you start touring. That doesn't mean ownership is out of reach, but it does mean down payment strategy, loan type, and price band matter more here than they would in a city where incomes and prices are better matched. Oregon also offers a tax-advantaged First-Time Home Buyer Savings Account, open for enrollment through December 31, 2026, that lets individual savers subtract up to $6,125 in annual contributions from Oregon taxable income — a practical tool worth knowing about before you start accumulating your down payment.
Whether you're deciding between renting and buying, weighing The Dalles against Hood River or Mosier, or simply trying to understand what $350,000 actually gets you here, the sections below walk through the local buyer reality, the step-by-step purchase process, honest budget scenarios, and the mistakes that cost first-timers the most in this specific market.
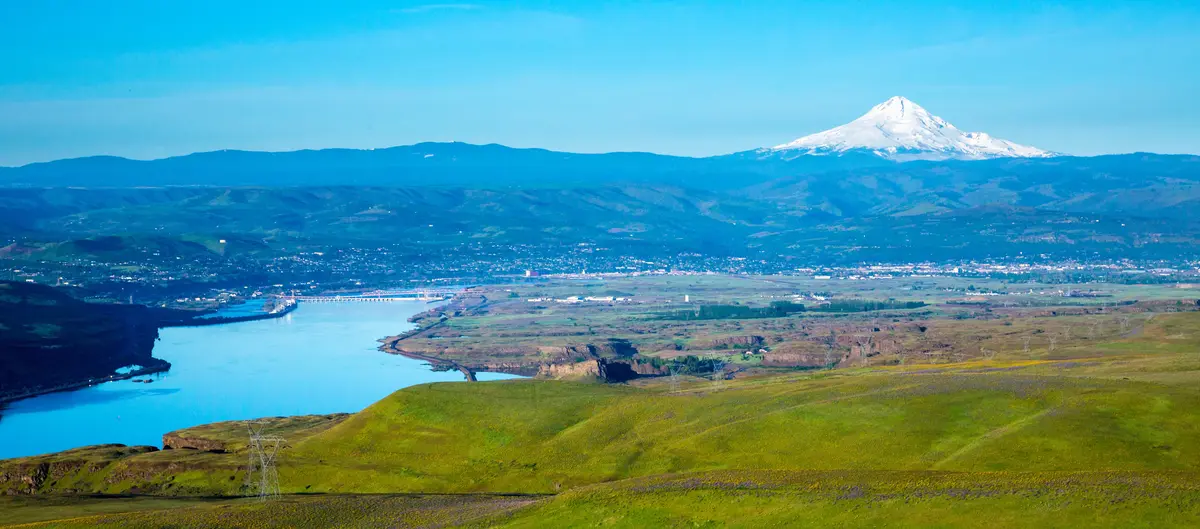
The The Dalles First-Time Buyer Reality
The typical home price in The Dalles is $396,291 (Zillow Home Value Index, July 2026). For a first-time buyer with a 3% or 3.5% down payment, that means roughly $12,000–$14,000 down before closing costs — a cash requirement that's meaningful but achievable with focused saving, especially compared with what that same down-payment percentage would demand in Hood River, where prices run noticeably higher.
What that number buys depends heavily on where in the city you shop. The Chenoweth area and parts of Erickson Addition tend to offer the most accessible entry points, with older single-family homes on established lots. Cherry Heights and Columbia View Heights carry more of the gorge-view premium. Downtown The Dalles and Trevitt's Addition offer walkable streets and historic character, but the housing stock there is older and can carry deferred-maintenance surprises that first-timers underestimate. For a deeper look at how each neighborhood sits relative to the city median, see the best neighborhoods guide.
The honest reality is that the income-to-price gap here is real. The median household income of $62,614 falls short of what's needed to comfortably carry the typical home, which means many first-time buyers in The Dalles are stretching — either on price, on down payment, or on monthly commitment. The market is not as competitive as Portland or Hood River, and homes generally sit long enough that buyers rarely feel forced into a blind bidding war. But well-priced homes in move-in condition do attract multiple offers. Coming in pre-approved, rather than pre-qualified, is the difference between being a serious buyer and being a spectator.
The Homebuying Process in The Dalles, Step by Step
Step 1: Get Pre-Approved Before You Tour
Pre-approval is not a formality in The Dalles — it's the gate. A seller receiving two or three offers will not wait for you to submit paperwork after the fact. Pre-approval means a lender has pulled your credit, reviewed income documentation, and issued a letter with a specific loan amount. Pre-qualification, which many online tools offer instantly, is not the same thing and will not carry weight in an offer.
Step 2: Know Your Loan Type Before You Start Shopping
First-time buyers in The Dalles have four realistic loan paths. FHA requires 3.5% down with a credit score of 580 or above, but carries mortgage insurance for the life of the loan unless you refinance out of it — a cost that adds up over a decade. Conventional 97 requires 3% down with a 620+ credit score and allows mortgage insurance to be cancelled once you reach 20% equity. VA loans require no down payment and no ongoing mortgage insurance for eligible veterans and service members — the strongest product available if you qualify. USDA Rural Development loans also require no down payment for income-eligible buyers; much of the Wasco County area, including properties in and around The Dalles, is USDA-eligible, which is an option many buyers in this market overlook entirely.
Step 3: Shop With a Realistic Price Band in Mind
Work backward from your pre-approval, not forward from your wishlist. Know the price ceiling your lender set, then subtract a buffer for competing offers or needed repairs. Condition varies significantly across The Dalles's housing stock — older homes in established neighborhoods may need updates that newer construction won't — so your effective budget needs to account for what you might inherit at closing, not just what the list price says.
Step 4: Make an Offer — With Contingencies Intact
The step first-timers most often get wrong in The Dalles is the inspection contingency. Because the market isn't as frenzied as Portland, most sellers will accept an offer with a standard inspection period. Waiving inspection to win here is almost never necessary — and given that much of the city's housing stock is older, it's the contingency that most often saves buyers from expensive post-closing discoveries. Write the offer with both an inspection contingency and a financing contingency. The appraisal contingency matters too: if the home appraises below purchase price, you need the contractual right to renegotiate or walk.
Step 5: Inspection, Appraisal, and Closing
Once under contract, the inspection typically happens within the first week. Pay particular attention to roof condition, foundation, and any older oil-heating systems in homes built before 1980 — all common in The Dalles's older housing stock. After inspection, your lender orders an appraisal. Closing in Oregon typically runs 30–45 days from accepted offer. One step many buyers skip: verify the parcel's actual assessed value through Wasco County's online tax records rather than assuming the seller's current tax bill reflects what you'll owe after purchase, since assessed values often differ from sale price.
How Much Home Can You Afford in The Dalles
The table below shows approximate cash requirements for several realistic purchase price scenarios in The Dalles. Closing costs are estimated at 2–3% of the purchase price, which is a standard Oregon range covering lender fees, title, escrow, prepaid property taxes, and homeowner's insurance at closing. These are estimates — your lender's Loan Estimate is the authoritative figure for your specific transaction. The interactive calculator below the table lets you adjust rate, term, and down payment to model your actual monthly payment.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs | Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5%) — entry-level | $310,000 | $10,850 (3.5%) | $6,200–$9,300 | ~$17,050–$20,150 |
| Conventional 97 (3%) — entry-level | $310,000 | $9,300 (3%) | $6,200–$9,300 | ~$15,500–$18,600 |
| FHA (3.5%) — near city median | $396,000 | $13,860 (3.5%) | $7,920–$11,880 | ~$21,780–$25,740 |
| Conventional 97 (3%) — near city median | $396,000 | $11,880 (3%) | $7,920–$11,880 | ~$19,800–$23,760 |
| VA or USDA (0% down) — near city median | $396,000 | $0 | $7,920–$11,880 | ~$7,920–$11,880 |
| Conventional (5%) — move-in-ready range | $430,000 | $2$1,500 (5%) | $8,600–$12,900 | ~$30,100–$34,400 |
Oregon also offers a First-Time Home Buyer Savings Account (open for enrollment through December 31, 2026) that lets individual savers subtract up to $6,125 in annual deposits and earnings from Oregon taxable income — up to $12,245 for joint filers — with a cumulative maximum subtraction of $50,000. Funds can be applied to down payment, closing costs, and related expenses. If you're 12–24 months out from buying, this is worth setting up before the enrollment window closes.
One item the table can't show: property taxes in Oregon are calculated on assessed value, not purchase price, and The Dalles carries an effective property tax rate of approximately 0.80%. Your post-purchase tax bill may differ from the seller's current bill — see the cost of living page for the full breakdown.
Looking to buy in The Dalles? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a The Dalles quote.
Common First-Time Buyer Mistakes in The Dalles
Mistake 1: Touring Before You're Pre-Approved
This is the most common and most costly mistake in sequence. Buyers who tour first and get pre-approved second routinely find that the home they fell in love with accepted another offer while they were gathering pay stubs. In The Dalles, where well-priced move-in-ready homes do attract competing offers, your pre-approval letter is your entry ticket — not your closing paperwork.
Mistake 2: Waiving Inspection to Compete
Some buyers arriving from Portland assume they need to waive the inspection contingency to win, because that's what the Portland market demanded in its most competitive years. The Dalles is a different market. Homes here generally sit long enough that sellers will accept a standard inspection period. Waiving inspection on an older home — where deferred maintenance on roofs, plumbing, and electrical is genuinely common in this city's housing stock — is accepting risk you don't need to take in this market.
Mistake 3: Ignoring the School Boundary and Commute Reality
Parents with school-age children sometimes discover after closing that the specific address they bought falls into a different attendance boundary than they assumed. The North Wasco County School District serves the whole city, but individual school assignments are address-specific. Confirm the boundary before making an offer, not after. Similarly, buyers who plan to commute to Portland underestimate what a drive of about 85 minutes actually means when run five days a week — fuel, wear, and time are all real costs. For a full look at schools, see the schools guide.
Mistake 4: Underbudgeting the Cash You Need at the Table
First-timers consistently budget for the down payment and forget that closing costs — lender fees, title, escrow, prepaid insurance, and property tax reserves — typically add another 2–3% of the purchase price. On a $396,000 home, that's roughly $8,000–$12,000 on top of the down payment. Running short on closing cash can delay or kill a closing. Use the table above and the calculator below to build a complete cash picture before you start making offers. Also verify the parcel's actual assessed value through Wasco County's online tax records — the seller's current tax bill may not reflect what you'll pay after your purchase price triggers a reassessment.
Local Expert Takeaway: The Dalles is one of the few places left in the Columbia Gorge where a first-time buyer with a 3–5% down payment can realistically get into a house — but the income-to-price gap means your loan type, your price band, and your cash reserves all need to be figured out before you tour, not after. USDA eligibility in Wasco County is underused and worth checking early. Homes sit long enough that you don't need to waive inspection to compete, which is a meaningful advantage over what buyers face in Hood River or Portland.
Quick Takeaways & FAQs
✅ The Dalles offers one of the most accessible entry prices remaining in the Columbia Gorge, with the typical home priced at $396,291 (Zillow Home Value Index, July 2026) — noticeably below Hood River.
⚠️ The median household income of $62,614 falls short of comfortable ownership at the typical price, so down payment strategy and loan type matter more here than in a city where incomes and prices are better matched.
📍 Many properties in The Dalles area qualify for USDA Rural Development loans with zero down payment — an option many first-time buyers overlook entirely in this market.
What credit score do I need to buy a home in The Dalles?
Can I buy a home in The Dalles with no money down?
How long does it take to buy a home in The Dalles?
Is The Dalles a good place to buy as a first-time homeowner compared with Hood River?
What is Oregon's First-Time Home Buyer Savings Account and should I open one?
Moving to Oregon?
Tell us what you need help with and we'll connect you with local resources.
