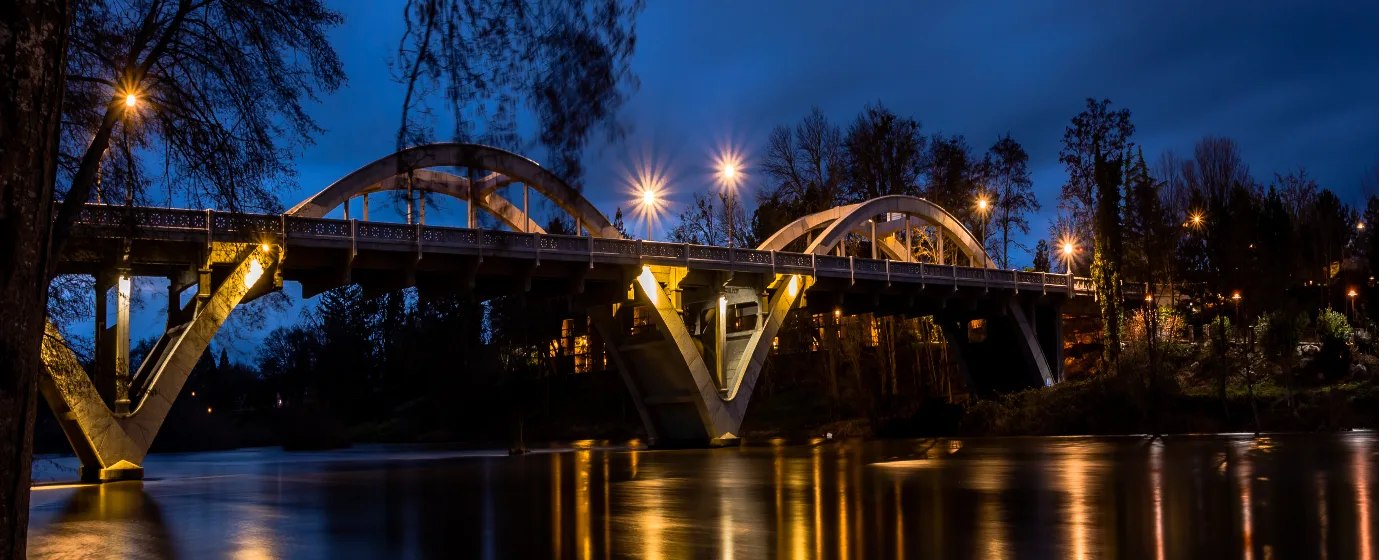
If you've been priced out of the Portland metro and someone mentioned Grants Pass, or your company is relocating you to Southern Oregon and you're doing the spreadsheet math for the first time, the number that catches your eye is the home price. At $404,270 (Zillow Home Value Index, July 2026), Grants Pass sits noticeably below what you'd pay in most Pacific Coast metros — but that figure deserves context before you start scheduling tours. The city of 39,311 sits along the Rogue River in Josephine County, with I-5 as its main artery and a drive of about 30 minutes to Medford putting the larger regional job market within reach. What actually shapes daily life here is the interplay between Southern Oregon's outdoor culture and a local economy anchored by healthcare, retail, and public-sector employment.
The economic backbone is smaller than most first-timers expect. Healthcare and social assistance leads local employment, followed by retail trade and manufacturing — with Asante Three Rivers Medical Center, Josephine County, the City of Grants Pass, and the school district among the largest institutional employers. Nearly 10% of the local workforce works from home, a share that ranks among the highest in the country for a city this size, which is part of why Portland-area and California buyers have been searching this market intensely. That inbound interest creates real competition at entry-level price points, and sellers here have come to expect a pre-approval letter before they'll take an offer seriously.
The affordability picture is more complicated than the headline price suggests. The median household income in Grants Pass is $59,646 — a meaningful gap below what's needed to carry the typical home here at current rates, which means down payment strategy and loan type selection matter more than they would in a cheaper market. The effective property tax rate is approximately 0.60%, which is among the lower rates in Oregon, and that does soften the monthly carrying cost somewhat. For buyers with location-independent income or a dual-income household close to or above six figures, this market is genuinely accessible. For buyers at or near the local median income, it requires careful planning. See the cost of living page for the full breakdown on taxes and household expenses.
Whether you're weighing a move from California, transitioning from renting here in town, or arriving from the Willamette Valley, the sections below walk through what the Grants Pass market actually looks like for a first-timer — the realistic budget, the buying process step by step, an honest affordability table, and the specific mistakes that cost local buyers the most.
The Grants Pass First-Time Buyer Reality
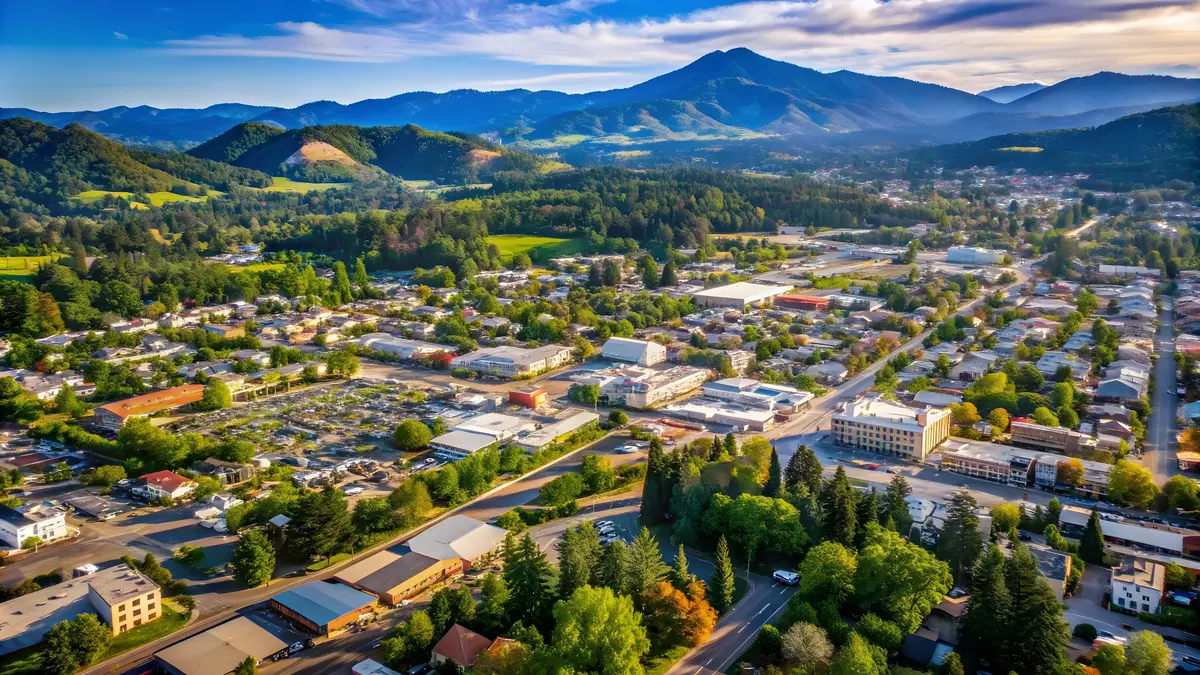
The typical home price in Grants Pass is $404,270 (July 2026), but that number doesn't tell you what a first-timer's budget actually buys. Entry-level inventory — older ranch-style homes, smaller bungalows, and manufactured homes on land — starts in the low-to-mid $300,000s for buyers willing to consider properties that need work or sit further from the core. Move-in-ready homes in neighborhoods that families with school-age children favor, like Fruitdale or Meadow Wood, typically push well above that threshold. The honest truth is that the gap between the city's median household income of $59,646 and what's needed to finance the typical home here is roughly $46,000 — so most first-timers buying in Grants Pass are either bringing equity from a previous market, earning above the local median, or using low-down-payment loan programs to bridge the difference.
Competition is real, particularly from buyers relocating from Portland, San Francisco, and Los Angeles, who often arrive with cash reserves and the ability to waive contingencies that local first-timers cannot afford to skip. This isn't the frenzied market of 2021, but it isn't a buyer's market either — well-priced homes in desirable pockets attract multiple offers quickly. If you're local and buying on a first-time budget, the practical reality is that you're often competing with people for whom Grants Pass feels cheap by comparison.
The northwest corridor along US-199 (Redwood Highway) has absorbed most of the city's newer residential construction and can offer relatively newer stock at accessible price points, though the trade-off is more car dependency and fewer walkable amenities. For buyers open to smaller neighboring communities, Rogue River sits somewhat lower in price than Grants Pass, and Merlin comes in noticeably lower still — but both require more intentional commute planning. If you want to stay in Grants Pass proper, budget honestly for what entry-level actually looks like here, and don't anchor to a median that includes homes well out of your reach. See the neighborhoods guide for a deeper look at which areas suit different buyer types.
The Homebuying Process in Grants Pass, Step by Step
Step 1: Get Pre-Approved Before You Tour Anything
In Grants Pass, sellers heavily favor offers accompanied by a lender pre-approval letter. This is not a courtesy step you can circle back to after finding a home you love — listing agents here will routinely decline to schedule showings without one, and an offer submitted without it rarely moves a motivated seller. Get pre-approved first, in writing, from a lender who has underwritten loans in Southern Oregon and understands the local appraisal environment.
Most Oregon lenders require a minimum credit score of 620 (640 for some conventional loan programs), a debt-to-income ratio in the 45–50% range, and documentation of all income sources. Pull your credit report before you contact a lender so there are no surprises. If your score is below 620, spend 60 to 90 days paying down revolving balances before applying.
Step 2: Shop With Purpose
Once pre-approved, define your must-haves versus nice-to-haves before you see your first home. Grants Pass has distinct neighborhood characters — Downtown Grants Pass, the Cathedral Hills area, Redwood, and the newer Starlight and Colonial Valley developments all feel different from one another. If school proximity matters to you, verify the actual attendance boundary for any specific address with the district directly; Grants Pass School District 7 holds a B- rating, according to Niche, but boundary lines don't always follow neighborhood names.
One step first-timers underestimate locally: check every prospective property against the city's wildfire at-risk area map and verify flood zone status independently. Properties near the Rogue River and Fruitdale Creek carry flood exposure, and standard homeowner's insurance does not cover flooding. Flood insurance is available through private carriers under National Flood Insurance Program guidelines, but it adds a recurring cost you need to budget before falling in love with a home on or near the river.
Step 3: Make a Competitive Offer
Your agent will run recent comparable sales and advise on price. First-timers often make the mistake of offering low on a well-priced home to leave negotiating room — in a market with inbound buyer pressure from larger metros, that approach tends to lose the home rather than save money. Come in at or near list price on anything priced accurately, and make sure your pre-approval letter is attached.
Step 4: Inspection and Appraisal
Do not waive your inspection contingency. This is the step that protects you from buying a home with a failing roof, foundation movement, or deferred maintenance that the seller has not disclosed. Older housing stock is common in Grants Pass, and the inspection is your only window into the physical condition of the property. A sewer scope — a camera inspection of the lateral sewer line — is a smart add-on for any home built before the 1990s.
The appraisal is ordered by your lender, not chosen by you, and it can occasionally come in below purchase price in a market where some homes are priced at the top of their comparable range. If that happens, you have three options: negotiate the price down, make up the gap in cash, or walk away under the appraisal contingency. Know your plan before the appraisal lands.
Step 5: Clear to Close and Closing Day
After inspection negotiations are resolved and the appraisal clears, your lender moves to underwriting. Expect requests for updated financial documentation — don't make any large purchases, open new credit accounts, or change jobs during this period, as any of those can derail final approval. Oregon closings are handled by title and escrow companies; you'll sign a substantial stack of documents and wire your closing cash ahead of the closing date. Budget 2–3 days for the wire to confirm before closing day.
How Much Home Can You Afford in Grants Pass
The table below shows approximate cash requirements at closing for several realistic Grants Pass price points using FHA (3.5% down) and conventional (3% down) structures. Closing costs are estimated at 2–3% of the purchase price, which covers lender fees, title and escrow, prepaid homeowner's insurance, and initial escrow reserves. These are estimates — your actual figures will vary based on lender, loan terms, and the specific property. The interactive calculator below the table applies current rates to any price point you choose.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs | Cash Needed at Table |
|---|---|---|---|---|
| FHA 3.5% — entry-level fixer | $310,000 | $10,850 (3.5%) | $6,200–$9,300 | ~$17,050–$20,150 |
| Conventional 3% — entry-level fixer | $310,000 | $9,300 (3%) | $6,200–$9,300 | ~$15,500–$18,600 |
| FHA 3.5% — near city median | $404,000 | $14,140 (3.5%) | $8,080–$12,120 | ~$22,220–$26,260 |
| Conventional 3% — near city median | $404,000 | $12,120 (3%) | $8,080–$12,120 | ~$20,200–$24,240 |
| Conventional 5% — move-in ready | $450,000 | $22,500 (5%) | $9,000–$13,500 | ~$31,500–$36,000 |
| Conventional 10% — move-in ready | $450,000 | $45,000 (10%) | $9,000–$13,500 | ~$54,000–$58,500 |
A few notes worth internalizing: putting less than 20% down on a conventional loan triggers private mortgage insurance, which adds a monthly cost until your equity crosses that threshold. FHA loans carry both an upfront mortgage insurance premium and an ongoing annual premium — they are accessible at lower credit scores and smaller down payments, but they are not free. VA and USDA loans offer 0% down for eligible borrowers (veterans and qualifying rural-area buyers respectively), and some Grants Pass-area properties within the Urban Growth Boundary may qualify for USDA financing — worth confirming with your lender if you're open to properties on the city's edges.
Oregon also offers a First-Time Home Buyer Savings Account that allows a deduction of up to $6,125 annually from Oregon taxable income on contributions or earnings — worth discussing with a tax advisor if you're still in the savings phase. ACCESS, a regional nonprofit serving Josephine County, runs a HUD-approved homebuyer education course and one-on-one counseling that can connect qualified buyers with additional resources; completing that coursework is a condition of several assistance pathways, so it's worth doing early in the process regardless of whether you ultimately use a program.
Looking to buy in Grants Pass? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Grants Pass quote.
Common First-Time Buyer Mistakes in Grants Pass
Touring Before You're Pre-Approved
This is the single most common mistake, and it's more costly here than in slower markets. Portland-area and California buyers relocating to Grants Pass often arrive pre-approved and ready to move fast. If you fall in love with a home and then spend a week getting your paperwork together, the home is likely gone. Sellers in Grants Pass treat the pre-approval letter as a basic condition of engagement, not a formality — see Step 1 above, and do it before you schedule a single tour.
Ignoring Wildfire and Flood Zone Status
Properties in parts of Grants Pass and its Urban Growth Boundary sit in elevated wildfire exposure areas, and homes near the Rogue River or Fruitdale Creek can carry flood risk. First-timers often discover this at the insurance quote stage, after they've already emotionally committed to a home. Request flood zone status and check the city's wildfire at-risk map before making an offer — not after. Budget for flood insurance separately if the property requires it; the cost is real and not included in a standard homeowner's policy.
Underestimating the Cash Needed at Closing
First-timers often focus on saving the down payment and treat closing costs as an afterthought. In Grants Pass, closing costs typically run 2–3% of the purchase price on top of your down payment. On a $400,000 home, that's an additional $8,000 to $12,000 you need in liquid cash — on top of the down payment — before you get the keys. The table in the section above shows the full picture for common scenarios. If you arrive at closing short on cash, the transaction collapses.
Skipping the Sewer Scope and Inspection Contingency
Competition from out-of-area buyers who waive contingencies to win can pressure local first-timers into doing the same. Don't. The housing stock in Grants Pass includes a significant share of older construction where deferred maintenance is real and not always visible. Waiving your inspection contingency means you own every problem the seller didn't disclose — and in Oregon, that liability can be substantial. A thorough inspection and a sewer scope on older homes are the two steps you should never trade away, regardless of how competitive the offer environment feels. The inspection fee is not trivial, but it is modest compared to the cost of discovering a failing sewer lateral after closing.
Misreading School Boundaries
Grants Pass School District 7 serves the city, but attendance boundaries don't always align neatly with neighborhood names or ZIP codes. A home in a desirable part of Fruitdale might feed into a different school than the one a few blocks away. If you have school-age children and a particular school matters to you, verify the actual attendance boundary for the specific address — not the neighborhood — directly with the district before making an offer. The schools page has more on the district overall, but the boundary check has to happen at the address level.
Local Expert Takeaway: Grants Pass is genuinely accessible for first-time buyers relative to most Oregon metros, but the entry point is higher than the median household income can comfortably carry without a strategic approach to loan type and down payment. The buyers who navigate this market well are the ones who get fully pre-approved before they tour, budget honestly for closing costs on top of the down payment, and never waive the inspection — even when competition feels intense. The inbound migration from Portland and California is real and ongoing, which means well-priced, move-in-ready homes don't sit. Know your number, have your paperwork ready, and check wildfire and flood zone status on any property near the Rogue River or the city's wooded edges before you fall in love with it.
Quick Takeaways & FAQs
✅ At $404,270 (July 2026), Grants Pass home prices sit noticeably below most Pacific Coast metros, making it a realistic first purchase for buyers with dual income or location-independent work.
⚠️ The gap between the local median household income and what's needed to carry the typical home here is roughly $46,000 — low-down-payment loan programs and honest cash budgeting are essential, not optional.
📍 Sellers in Grants Pass treat the pre-approval letter as a baseline requirement before scheduling tours — get it done first, every time.
What credit score do I need to buy a home in Grants Pass, Oregon?
How much do I need for a down payment on a home in Grants Pass?
Do I need a pre-approval letter to see homes in Grants Pass?
Are there wildfire or flood risks I should know about before buying in Grants Pass?
How does buying in Grants Pass compare to buying in Medford?
Moving to Oregon?
Tell us what you need help with and we'll connect you with local resources.
