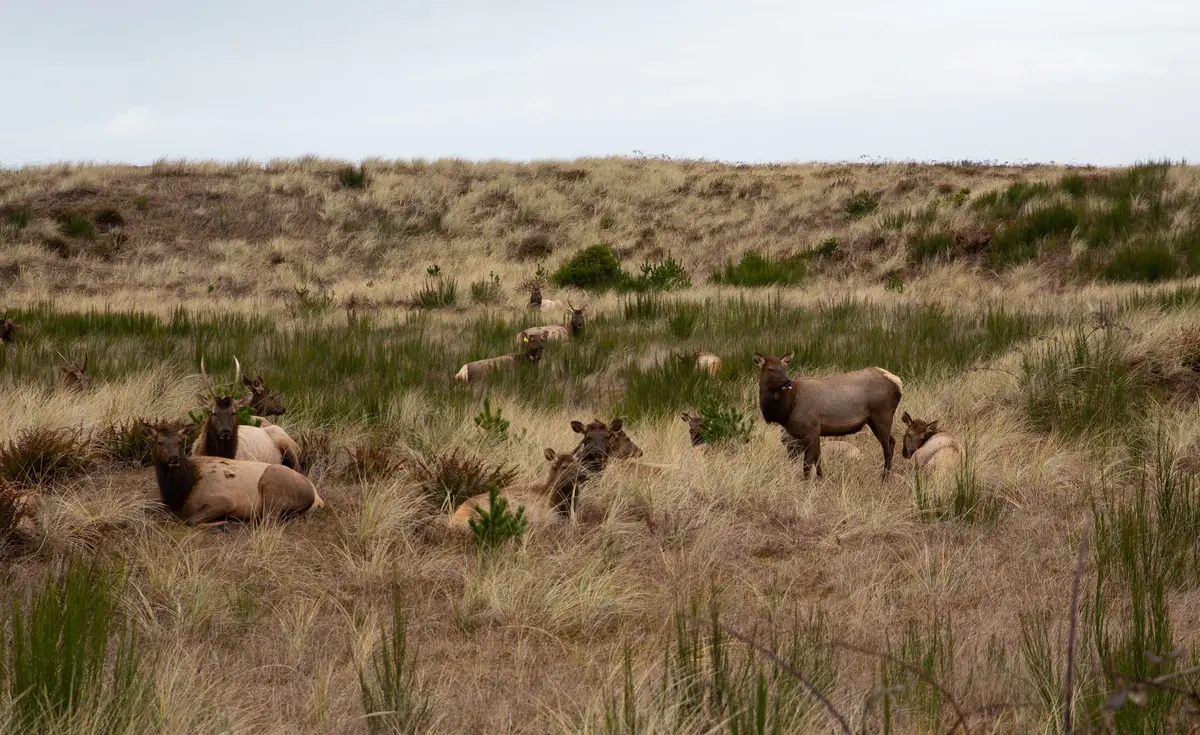
Maybe someone told you Gearhart was the quieter alternative to Cannon Beach, or you priced yourself out of Seaside and kept driving north. Either way, you've landed on one of the smallest incorporated cities on the Oregon coast — 1,872 people, no traffic lights, and a herd of more than 150 Roosevelt elk that walks through residential streets on its own schedule. The surprise isn't that the town is beautiful. The surprise is how seriously you have to take the finances before you can own a piece of it.
The typical home price in Gearhart sits at $619,942 (Zillow Home Value Index, July 2026), and the median household income of $85,682 falls well short of what it takes to carry that price comfortably — by roughly $33,000. That gap is the central reality for any first-timer here. The town's stock includes century-old cottages alongside newer construction, but a meaningful share of what's listed at any moment is a vacation home or second property, not a primary residence being sold to another owner-occupant. That compresses the pool of listings that fit a first-timer's circumstances and budget.
What you get in exchange is worth being clear-eyed about. Under Oregon's Beach Bill, every buyer here acquires a home within walking distance of permanently public beachfront — that is not a marketing line, it is state law. US-101 runs through town and puts Seaside about ten minutes away and Portland about 95 minutes to the north. A significant share of the workforce here works remotely, and the broadband infrastructure is considered solid for coastal living. The outdoor life — Gearhart Beach, Del Rey Beach State Recreation Site, the Necanicum Estuary, the golf course that has been here since 1892 — is part of what keeps prices where they are.
Whether you're a remote worker who has decided coastal Oregon beats another year of city renting, or a local looking to stop paying someone else's mortgage, the sections below walk through what your budget actually buys here, the step-by-step buying process in Clatsop County, a plain-math budget table, and the mistakes first-timers most commonly make in this specific market.
The Gearhart First-Time Buyer Reality
The typical home price in Gearhart is $619,942 (July 2026), and that number does real work: it tells you this is not a starter-market in the traditional sense. Entry-level here — older cottages, smaller footprints, properties that need updating — tends to start in the low-to-mid $400,000s when they appear. Well-maintained primary-residence homes move through the $500,000s and into the $600,000s quickly. For context, Seaside and Warrenton both run noticeably lower, while Cannon Beach runs noticeably higher — so Gearhart sits in the middle of the coastal tier, closer to the expensive end than the affordable one.
The vacation-and-second-home dynamic is the thing most first-timers don't anticipate. Because a significant portion of Gearhart's housing stock is held as investment or vacation property, the supply of primary-residence listings is thinner than the city's size would suggest. When a well-priced home does come to market, it rarely sits. You are not competing only against other first-timers — you may be up against cash buyers with no financing contingency, buyers trading down from a pricier coastal market, and remote workers who have already sold a home somewhere more expensive. That reality shapes everything about how you need to show up.
The neighborhoods guide covers the character of specific areas — West Gearhart, The Highlands, Pinehurst Estates, and the others — but the price picture across those neighborhoods is worth understanding through the city-wide lens first. The affordability gap here is real, and buyers who come in with a clear-eyed budget and a lender letter already in hand are the ones who actually close.
The Homebuying Process in Gearhart, Step by Step
Step 1: Get Pre-Approved Before You Tour Anything
In a market this small, touring before you have a pre-approval letter is not just inefficient — it can cost you the house. Inventory can be genuinely limited at any given moment, and listing agents in a town of 1,872 people know each other and know the buyer pool. A pre-approval from a lender who understands Oregon coastal properties, including flood-zone requirements, puts you in a different category than a buyer who "just wants to look."
Step 2: Work With an Agent Who Knows the Coast
Coastal real estate in Clatsop County has specific wrinkles that a Portland-focused agent may not flag automatically: flood-zone determinations, the Beach Bill's public access easement, and the difference between a vacation-use-zoned property and a residential one. Ask your agent directly how many Gearhart transactions they've closed in the past two years.
Step 3: Make an Offer — and Understand What You're Signing
Oregon is an escrow state; transactions close through title companies rather than courtrooms. Your offer will include a purchase price, earnest money, and contingencies — financing, inspection, and appraisal being the standard three. In a competitive situation, sellers may push back on contingency timelines. A first-timer's single most important negotiating chip is speed: a clean offer with a short but reasonable inspection window is more competitive than a higher price with a slow timeline.
Step 4: The Inspections — Don't Shortcut This Step on the Coast
For Clatsop County properties, the recommended inspection package goes beyond a standard home inspection. A roof inspection and a sewer scope are both worth doing. More importantly, your lender will likely require a flood-zone determination — FEMA Flood Insurance Rate Maps cover the Seaside-Gearhart area, and your specific parcel may or may not fall within a designated flood zone. If it does, the cost of flood insurance becomes part of your monthly carrying cost, and that needs to be in your budget before you close, not after.
Step 5: Closing
Oregon buyers typically pay closing costs of 2%–5% of the purchase price, covering lender origination fees, appraisal, title search and insurance, escrow, and prepaid items including property taxes and homeowners insurance. Budget for the full 5% range if you want to avoid surprises at the table.
How Much Home Can You Afford in Gearhart
The table below shows what different purchase prices and down payment strategies mean for your cash needs at closing. Closing costs are estimated at 2%–5% of the purchase price — use the higher end for your planning unless your lender gives you a specific Loan Estimate to work from. These are approximations; your actual figures will depend on your lender, your loan program, and the specific property.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (2%–5%) | Est. Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5% down) — entry tier | $420,000 | ~$14,700 (3.5%) | ~$8,400–$21,000 | ~$23,100–$35,700 |
| Conventional (3% down) — entry tier | $420,000 | ~$12,600 (3%) | ~$8,400–$21,000 | ~$21,000–$33,600 |
| FHA (3.5% down) — mid tier | $520,000 | ~$18,200 (3.5%) | ~$10,400–$26,000 | ~$28,600–$44,200 |
| Conventional (5% down) — mid tier | $520,000 | ~$26,000 (5%) | ~$10,400–$26,000 | ~$36,400–$52,000 |
| Conventional (10% down) — city median | $620,000 | ~$62,000 (10%) | ~$12,400–$31,000 | ~$74,400–$93,000 |
| Conventional (20% down) — city median | $620,000 | ~$124,000 (20%) | ~$12,400–$31,000 | ~$136,400–$155,000 |
The 20%-down scenario eliminates private mortgage insurance and meaningfully reduces the monthly carrying cost — but it requires a cash reserve that exceeds the median household income here by a wide margin. Most first-timers in this market target the entry tier and accept PMI as a short-term cost of getting in.
The interactive calculator below this section lets you adjust the purchase price, down payment percentage, and current rate to model your specific monthly payment — use it alongside these cash-needed estimates to get the full picture. For property tax, the effective rate in Gearhart is approximately 0.71%, which you can also fold into your affordability math on the cost of living page.
Looking to buy in Gearhart? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Gearhart quote.
Common First-Time Buyer Mistakes in Gearhart
Shopping Before You Have a Pre-Approval Letter
In a city this size, the inventory of primary-residence homes can be thin enough that a desirable listing and a competing offer can appear within the same week. Buyers who tour first and arrange financing second are often the ones who lose a home they wanted. Get your lender letter before you call an agent to schedule a showing — not after.
Waiving the Inspection Contingency to Win a Bidding Situation
The coastal environment does specific things to homes: salt air accelerates certain kinds of deterioration, older cottages may have deferred maintenance that isn't visible on a walkthrough, and sewer laterals in a town built around a century-old grid can surprise you. A roof inspection and sewer scope are not optional extras on the Oregon coast — they are the two items most likely to surface a costly problem before you own it. Waiving inspection entirely to strengthen an offer is a gamble that experienced coastal buyers rarely take.
Ignoring the Flood-Zone Question Until After the Offer
Many first-timers in Gearhart don't ask about flood-zone status until they're under contract, and by then the flood insurance premium is already a surprise. FEMA Flood Insurance Rate Maps cover the Seaside-Gearhart area specifically, and your parcel's zone designation directly affects your insurance cost and possibly your lender's requirements. Ask your agent and your lender about flood-zone status before you make an offer — not at the inspection stage.
Underbudgeting the Cash Needed at Closing
The down payment is only part of what you need. Oregon closing costs run 2%–5% of the purchase price, and on a $500,000 home that range spans $10,000 to $25,000 — a difference that catches buyers who planned for the low end and arrived at the high one. Budget at 5% unless your Loan Estimate gives you a specific reason to revise downward. The cash-needed column in the table above is the honest version of what showing up at a Gearhart closing actually requires.
Local Expert Takeaway: Gearhart is a first-timer's market only in the sense that it is technically possible — not in the sense that it is easy. The vacation-home dynamic, the limited primary-residence inventory, and the gap between local incomes and local prices mean the buyers who succeed here come in prepared: pre-approved, flood-zone-aware, and budgeted for the full 5% closing cost range rather than the optimistic 2%. The elk crossing the golf links at dusk is real, and so is the math. Get the math right first.
Quick Takeaways & FAQs
✅ Every home in Gearhart is within walking distance of permanently public beachfront under Oregon's Beach Bill — that access is guaranteed by state law, not subject to a homeowners association or a seller's permission.
⚠️ The vacation-and-second-home share of Gearhart's housing market is higher than in a typical Oregon town, which means primary-residence inventory can be genuinely thin — first-timers need a pre-approval letter before they tour, not after.
📍 Coastal Clatsop County properties often require a flood-zone determination in addition to a standard inspection — ask about your specific parcel's FEMA flood zone status before making an offer, because it directly affects your insurance cost.
What is the typical home price for first-time buyers in Gearhart, Oregon?
Do I need a flood insurance policy to buy a home in Gearhart?
What closing costs should I budget for when buying in Gearhart?
Is Gearhart a competitive market for first-time buyers?
How far is Gearhart from Portland, and does that matter for first-time buyers?
Moving to Oregon?
Tell us what you need help with and we'll connect you with local resources.
