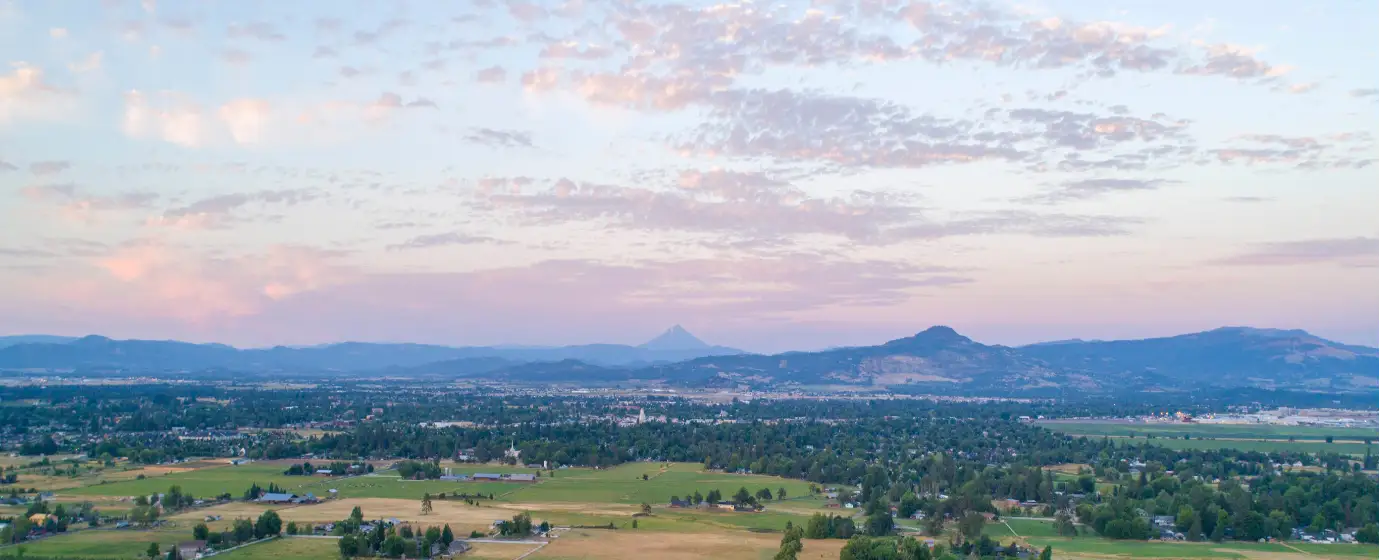
Maybe you've been renting in Medford and watching prices hold steady while your landlord's renewal letter sits on the counter. Maybe you moved to Southern Oregon for the lifestyle — the sun, the access to the outdoors, the slower pace — and you're now doing the math on whether buying here actually makes sense. Central Point sits about 10 minutes to Medford by interstate, which means you get a smaller city's prices and community feel without giving up access to the region's jobs, hospitals, and shopping. That proximity is the first thing first-time buyers discover — and one of the main reasons they choose Central Point over a more expensive Medford zip code.
The honest version of the market here: single-family detached homes make up roughly two-thirds of the housing stock, and the homeownership rate sits at approximately 67% — above the national average. This is a city of owners, not renters, which means listings move and the buyer pool is real. Jackson County has remained in seller's-market territory without a balanced stretch since winter 2019. For a first-timer, that's the environment you're entering — not impossible, but not forgiving to buyers who show up unprepared or without a pre-approval letter already in hand.
Prices are meaningful here without being brutal. The typical home price is $423,657 (Zillow Home Value Index, July 2026), which is roughly comparable to Medford and noticeably above White City. The catch is that the median household income of $86,819 falls short of what's needed to carry that price comfortably — by roughly $25,000 — which means most first-timers are stretching, budgeting carefully, or bringing in a dual income. Oregon closing costs typically run 3%–5% of the purchase price, so the cash you need at the table is larger than many buyers expect going in.
Whether you're six months away from making an offer or just running numbers for the first time, the sections below break down what the Central Point market actually looks like for first-time buyers, how the homebuying process works in Oregon, what your budget buys at different price points, and the specific mistakes that cost local buyers the most.
The Central Point First-Time Buyer Reality
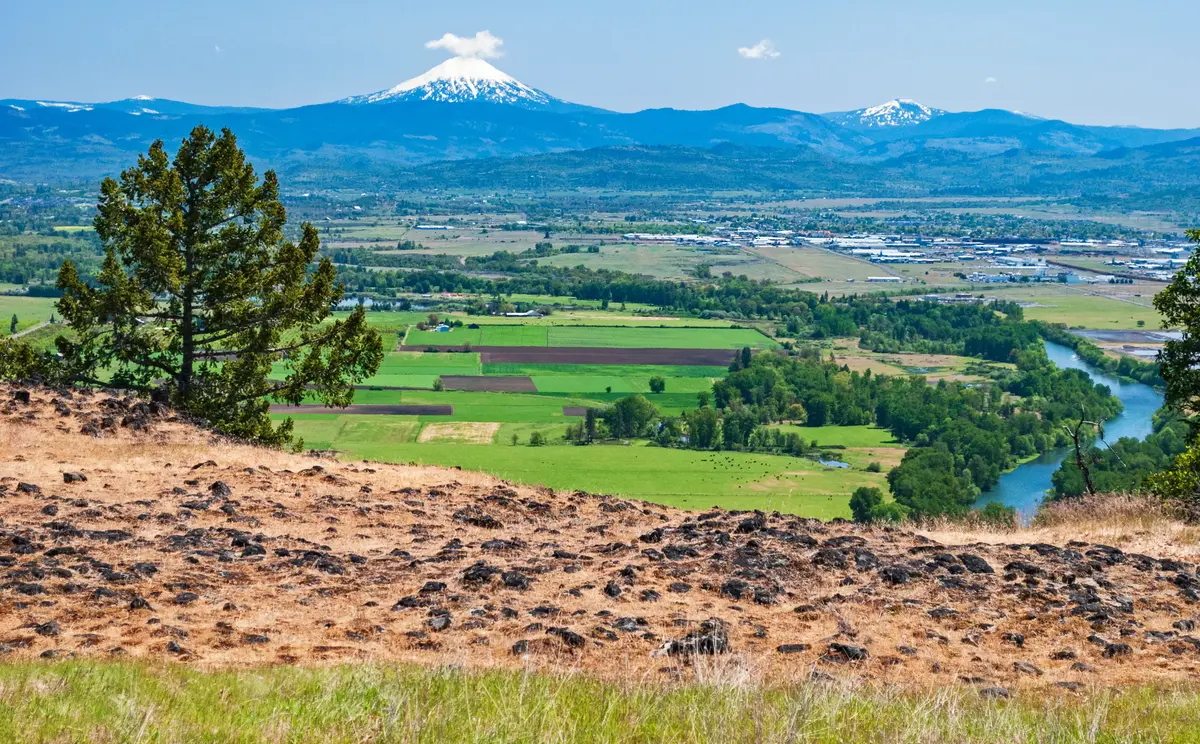
The typical home price in Central Point is $423,657 (July 2026), and that figure lands in a market that skews heavily toward single-family detached homes. If you're picturing a starter condo at $280,000 — that's not this market. The entry-level product here tends to be older construction or smaller footprints in areas like Central Point East or Beebe Woods, and those homes still require meaningful cash at closing.
The ten-year appreciation picture is worth understanding before you decide renting is safer: home values here have roughly doubled over the past decade, averaging about 7% annually — a pace that ranks Central Point's appreciation above 90% of Oregon cities. Waiting isn't automatically the conservative move. The more honest constraint for most first-timers is cash, not income: getting to the down payment and closing costs simultaneously is the gap most buyers underestimate.
Jackson County's inventory has remained lean. Homes that are well-priced and in reasonable condition don't sit. That doesn't mean you'll lose every offer or face a bidding war on every house — but it does mean you won't have the luxury of browsing casually, sleeping on it for two weeks, and coming back with a lowball. For a first-time buyer in Central Point, preparation before you ever step inside a house is what separates people who close from people who keep losing offers and eventually give up.
The Homebuying Process in Central Point, Step by Step
Step 1: Get Pre-Approved — Before You Tour Anything
Oregon sellers expect a pre-approval letter before they take an offer seriously. This is not a formality — it's table stakes. To get pre-approved, you'll submit tax returns, recent pay stubs, and bank statements. Lenders evaluate your credit score and debt-to-income ratio. If you're rate-shopping across multiple lenders, all credit inquiries within a 45-day window count as a single hit to your score, so shop in a concentrated window rather than spreading it over months.
Step 2: Find a Local Buyer's Agent
Oregon real estate transactions run through escrow and title companies, not attorneys — so your buyer's agent carries more of the process than you might expect if you've bought elsewhere. A buyer's agent who works regularly in Jackson County will know which neighborhoods are moving, which listings have been price-reduced more than once, and what a realistic offer looks like for Central Point specifically versus nearby Medford or Eagle Point.
Step 3: Shop Within Your Pre-Approved Range
Your pre-approved amount is a ceiling, not a target. Many first-timers in Central Point make the mistake of shopping at the top of their range and then feeling the squeeze once property taxes, insurance, and maintenance enter the picture. The cost of living breakdown is worth reviewing before you set your shopping ceiling.
Step 4: Make an Offer — and Understand Oregon's Paperwork
Oregon uses a standard Residential Real Estate Sale Agreement. Your offer will include a purchase price, earnest money deposit (typically 1%–2% of the purchase price), and contingencies for inspection, financing, and appraisal. In a competitive situation, buyers sometimes consider waiving certain contingencies — the section on common mistakes covers why that gets first-timers burned locally.
Step 5: Inspection, Appraisal, and Closing
Never skip the home inspection in Central Point. Older construction in neighborhoods like Beebe Woods or Central Point East can carry deferred maintenance that isn't visible at a showing. Your lender will order an appraisal independently. If the appraisal comes in below your offer price, you'll either need to negotiate with the seller, cover the gap in cash, or walk. Oregon's escrow process typically takes 30–45 days from accepted offer to keys in hand. Closing costs — the step that surprises most first-timers — are covered in detail in the next section.
How Much Home Can You Afford in Central Point
Oregon closing costs typically run 3%–5% of the purchase price. Because Oregon is an escrow state, buyers pay both title insurance and escrow settlement fees on top of the standard lender charges. That means the cash you need at the table is the sum of your down payment plus closing costs — two separate line items that both require real money on the same day. The table below shows estimated cash requirements at several realistic Central Point price points. All figures are estimates; your actual costs will depend on your loan type, lender, and negotiated terms.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (3%–5%) | Est. Cash Needed at Table |
|---|---|---|---|---|
| FHA loan (3.5% down) | $350,000 | ~$12,250 | ~$10,500–$17,500 | ~$22,750–$29,750 |
| Conventional (3% down) | $350,000 | ~$10,500 | ~$10,500–$17,500 | ~$21,000–$28,000 |
| FHA loan (3.5% down) | $420,000 | ~$14,700 | ~$12,600–$21,000 | ~$27,300–$35,700 |
| Conventional (3% down) | $420,000 | ~$12,600 | ~$12,600–$21,000 | ~$25,200–$33,600 |
| Conventional (5% down) | $420,000 | ~$21,000 | ~$12,600–$21,000 | ~$33,600–$42,000 |
| Conventional (10% down) | $450,000 | ~$45,000 | ~$13,500–$22,500 | ~$58,500–$67,500 |
FHA loans require a minimum FICO score of 580 for the 3.5% down option and carry an upfront mortgage insurance premium of 1.75% of the base loan amount — typically rolled into the loan — plus ongoing annual premiums. Conventional loans at 3% down also require private mortgage insurance until you reach 20% equity. Use the mortgage calculator below to model your specific payment based on current rates and your down payment amount.
Oregon also offers a First-Time Home Buyer Savings Account (FTHBSA) — a state-level tax tool administered by the Oregon Department of Revenue, available at any bank or credit union since January 2025. Eligible buyers (no home ownership in the prior three years) can subtract up to $6,125 per year from Oregon taxable income on deposits and earnings, or $12,245 for joint filers, with a cumulative cap of $50,000 over ten years. This isn't a grant or a loan — it's a tax subtraction that reduces what you owe Oregon while you save — but for first-timers building a down payment fund, it's worth setting up before you start serious house-hunting.
Looking to buy in Central Point? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Central Point quote.
Common First-Time Buyer Mistakes in Central Point
Touring Homes Before Getting Pre-Approved
This one costs people offers, not just time. In Jackson County's lean inventory environment, a well-priced home in Twin Creeks or Cascade Meadows can draw serious attention quickly. If you've toured it without a pre-approval letter and decide you want it, you're going home to gather documents while another buyer — who did the prep work — submits an offer that afternoon. Sellers aren't obligated to wait. Get pre-approved first, then tour.
Waiving the Inspection Contingency to Win a Competitive Offer
Some buyers in tighter offer situations are tempted to waive the inspection contingency to look more attractive to sellers. In Central Point's older housing stock — particularly in neighborhoods with homes built in the 1970s through 1990s — that's a risk that can turn into a very expensive lesson. Roof conditions, aging electrical panels, and HVAC systems that are past their service life are the categories that come up most often. Waiving inspection to win is a decision that occasionally works out; it also occasionally hands you a $20,000 problem you can't unsee.
Underestimating the Total Cash Needed at Closing
Nearly half of all buyers report that purchasing a home cost more than they expected. In Oregon, that surprise usually comes from closing costs. Buyers who've been laser-focused on saving a down payment often arrive at the closing table underprepared for the title insurance, escrow fees, prepaid homeowner's insurance, and property tax reserves that sit on top of it. Budget 3%–5% of the purchase price in closing costs — in addition to your down payment — and treat that as a floor, not a ceiling.
Ignoring School Boundaries and Commute Before Making an Offer
Central Point School District 6 holds a C+ rating, according to Niche, and some families will weigh that against the district serving their alternatives in Medford or Eagle Point. School attendance boundaries in Jackson County don't always follow the logic of which neighborhood feels closest to a particular campus — worth verifying before you fall in love with a specific address. Similarly, Central Point's access to I-5 and OR-99 makes most Medford-area commutes manageable, but buyers who end up in parts of the city farther from the main corridors sometimes find the daily drive adds up more than they anticipated. Check the actual route, not just the city name, before you write an offer on a house in a less-connected part of town.
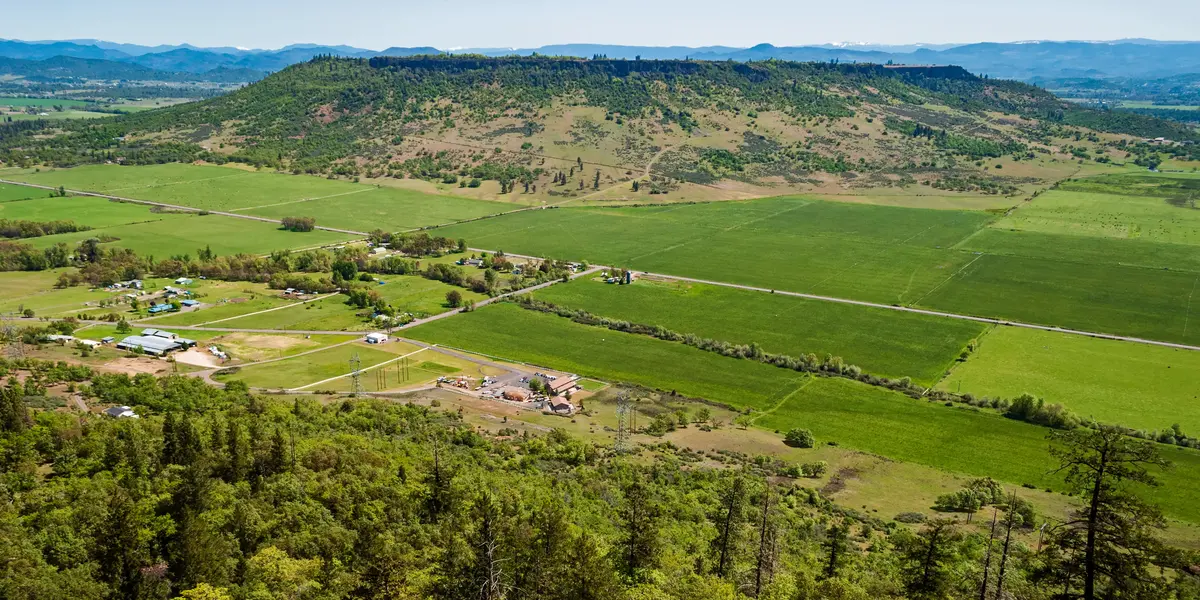
Local Expert Takeaway: Central Point is a genuine first-time buyer market — not because it's cheap, but because it's priced below the state's most competitive metros while sitting close enough to Medford's jobs and services to make it practical. The buyers who succeed here do two things right: they get pre-approved before they ever schedule a showing, and they budget honestly for the full cash requirement at closing, not just the down payment. If you're saving now, Oregon's First-Time Home Buyer Savings Account is worth opening at your bank or credit union — it won't close the gap on its own, but it reduces your state tax bill while you build the reserves you'll need.
Quick Takeaways & FAQs
✅ Central Point's homeownership rate of approximately 67% is above the national average, and ten-year home appreciation has averaged around 7% annually — making ownership here a historically sound long-term decision.
⚠️ The median household income falls short of what's needed to comfortably carry the typical home price by roughly $25,000, so most first-time buyers are stretching — careful budgeting and a realistic price ceiling matter more here than in cheaper markets.
📍 Oregon is an escrow state, not an attorney state — your buyer's agent carries more of the transaction than you might expect, and a local agent with Jackson County experience is worth prioritizing over someone who primarily works Medford or Ashland.
What credit score do I need to buy a home in Central Point?
How long does it take to buy a home in Central Point once I find one I want?
Are there any Oregon-specific tax benefits for first-time buyers in Central Point?
Is it better to buy or rent in Central Point right now?
What does the entry-level market in Central Point actually look like?
Moving to Oregon?
Tell us what you need help with and we'll connect you with local resources.
