Maybe you've been priced out of Rexburg and someone mentioned St. Anthony. Maybe you work in Idaho Falls and ran the numbers and realized that a commute on U.S. Route 20 could cut your housing costs dramatically. Either way, you probably weren't expecting to find a market where a median home price still sits below $300,000 in 2026. That figure is real — $290,325 per the Zillow Home Value Index as of May 2026 — and it's the single most important fact about buying here. For a first-time buyer, St. Anthony may be one of the last genuinely accessible ownership markets in Eastern Idaho.
St. Anthony is a working city of about 4,081 people in Fremont County, anchored by employers like Grand Peaks Healthcare, Broulim's Fresh Foods, and the City of St. Anthony itself. It sits on U.S. Route 20 with Rexburg roughly 17 minutes west — close enough that many buyers here commute to the larger retail and healthcare corridor there. The community draws first-timers who want ownership without the bidding-war culture that defines markets closer to Jackson Hole or even downtown Idaho Falls.
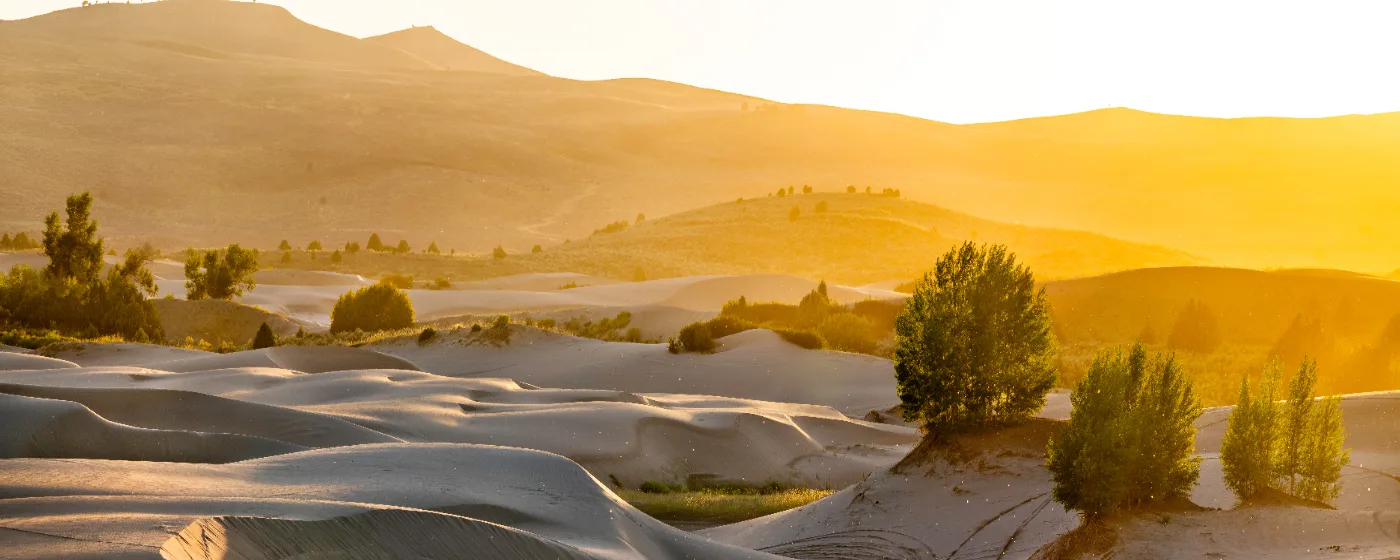
The lifestyle trade-off is real: St. Anthony is small, and the amenities reflect that. You get the Henry's Fork of the Snake River at the edge of town, the St. Anthony Sand Dunes nearby, and a historic downtown that has independent character without being a restaurant row. What you don't get is a Trader Joe's or a major hospital within city limits — Grand Peaks Healthcare handles primary care, and anything more specialized means a drive. For buyers whose priority is owning rather than renting, that's usually an acceptable compromise. For those who want walkable urban life, it isn't. See the cost of living page for a full breakdown of day-to-day expenses here.
Whether you're making your first offer or still deciding whether St. Anthony fits your life, the sections below walk through what your budget actually buys here, the step-by-step purchase process, an honest affordability snapshot, and the four mistakes that cost first-time buyers the most in this specific market.
The St. Anthony First-Time Buyer Reality
At a city-wide median sold price of $290,325 (Zillow Home Value Index, May 2026), St. Anthony is one of the few Eastern Idaho markets where a household earning close to the area median can realistically enter homeownership without a six-figure down payment. That figure has climbed 4.6% year-over-year, so the window isn't frozen open — but compared to the Rexburg market or anything along the Teton Valley corridor, it remains meaningfully lower.
What does that price actually buy? Older construction from the mid-twentieth century — ranch homes that need cosmetic updating or deferred maintenance work — represents the entry end of the market. In the mid-range, inventory opens up to move-in-ready three-bedroom homes on established lots. Above $320,000, you start seeing newer builds, larger lots, and properties with more storage and outbuilding space that appeals to buyers with equipment or animals.
Active listings on the Snake River Regional MLS numbered around 90 to 91 in late May 2026, with average list prices running slightly above the Zillow Home Value Index — a normal pattern when listed homes skew larger than the typical sale. That inventory level gives first-timers more breathing room than they'd have in a 20-listing market, but well-priced homes in the $250,000–$290,000 range still move. Coming in without pre-approval and a clear budget is the fastest way to lose the house you actually want.
The Homebuying Process in St. Anthony, Step by Step
Step 1: Get Pre-Approved — Before You Tour Anything
This is not a suggestion here — it's a practical requirement. St. Anthony's inventory is thin enough that when a well-priced three-bedroom hits the market, sellers are fielding offers within days. Bank of Idaho maintains a branch directly in St. Anthony, so you don't have to drive to Rexburg or Idaho Falls to sit down with a community lender who knows Fremont County appraisals and local comps. Get your pre-approval letter in hand before you schedule a single showing.
Step 2: Define Your Search with a Local Agent
St. Anthony's neighborhoods vary in ways that aren't obvious from a Zillow map. Properties near the Henry's Fork sit in a different flood-zone conversation than those on higher ground. An agent who regularly closes in Fremont County will flag those distinctions before you fall in love with a house that carries additional insurance requirements. Identify your must-haves — garage, lot size, outbuilding potential — before touring, and stick to them.
Step 3: Make an Offer with All Your Contingencies Intact
FHA and conventional loans both require an appraisal, and St. Anthony appraisals can come in conservatively when there aren't enough recent comparable sales nearby. Build your inspection and appraisal contingencies into every offer. The one step first-timers most often get wrong here is waiving the inspection contingency to compete — in a market at this price point, that's rarely necessary, and older housing stock in a rural Idaho city can hide deferred maintenance that a $400 inspection would have caught.
Step 4: Inspection and Appraisal
Idaho is a caveat emptor state — seller disclosure obligations exist but are limited. Hire a licensed inspector and attend the inspection in person. Older homes may have original plumbing, outdated electrical panels, or insulation that doesn't meet modern standards. None of those are deal-killers, but they're negotiating points. Your lender's appraiser will independently value the home; if it appraises below the purchase price, you'll need to renegotiate, cover the gap in cash, or walk away using your contingency.
Step 5: Closing
Idaho closings typically happen at a title company. Expect to sign a significant stack of documents and to bring your closing funds via wire transfer or certified check — personal checks are not accepted. Closing costs in Idaho typically run 2% to 3% of the purchase price, covering lender fees, title insurance, prepaid property taxes, and homeowners insurance escrow. Budget for that figure on top of your down payment; many first-timers underestimate it and arrive at the closing table short.
How Much Home Can You Afford in St. Anthony
The table below shows estimated cash requirements at closing across several realistic purchase scenarios for St. Anthony buyers. Down payment percentages reflect common loan program minimums; closing costs are estimated at approximately 2.5% of the purchase price. These are approximations — your lender will provide a Loan Estimate with exact figures after pre-approval.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs | Cash Needed at Table |
|---|---|---|---|---|
| FHA minimum (3.5%) — entry-level fixer | $210,000 | $7,350 (3.5%) | ~$5,250 | ~$12,600 |
| Conventional (3%) — entry-level fixer | $210,000 | $6,300 (3%) | ~$5,250 | ~$11,550 |
| FHA minimum (3.5%) — near median | $270,000 | $9,450 (3.5%) | ~$6,750 | ~$16,200 |
| Conventional (3%) — near median | $270,000 | $8,100 (3%) | ~$6,750 | ~$14,850 |
| Conventional (5%) — at city median | $290,325 | ~$14,516 (5%) | ~$7,258 | ~$21,774 |
| Conventional (10%) — newer construction | $325,000 | $32,500 (10%) | ~$8,125 | ~$40,625 |
FHA loans carry an upfront mortgage insurance premium (typically 1.75% of the loan amount, often rolled into the loan) plus ongoing monthly mortgage insurance — your lender's Loan Estimate will show both. Conventional loans with less than 20% down include private mortgage insurance, which falls off once you reach 20% equity.
The effective property tax rate in St. Anthony is approximately 0.43%, among the lowest in Idaho — see the cost of living page for how that compares to surrounding counties. The interactive mortgage calculator below will build out a full monthly payment estimate once you enter your price, down payment, rate, and loan term.
Looking to buy in St. Anthony? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a St. Anthony quote.
Common First-Time Buyer Mistakes in St. Anthony
Shopping Before You're Pre-Approved
In a market with roughly 90 active listings across all price points, the homes that fit a first-timer's budget are a subset of that pool — and they move. Showing up with a pre-qualification (a soft estimate) instead of a pre-approval letter (verified income, assets, and credit) signals to sellers that you're not ready. Any seller who has another offer in hand will take it over a buyer who still needs to complete underwriting steps.
Waiving the Inspection Contingency on Older Stock
St. Anthony has real inventory of homes built between the 1940s and 1970s. These properties can carry aging infrastructure — older wiring, original cast-iron drain lines, swamp-cooler setups, or foundations that have shifted over decades of Eastern Idaho freeze-thaw cycles. Waiving inspection to win a bidding situation on a home in this age range is rarely worth it. The market here generally doesn't require it, and the downside risk on a $220,000 fixer is disproportionate to any competitive edge you gain.
Ignoring the Flood Zone Question Near the Henry's Fork
Properties close to the Henry's Fork of the Snake River may fall within FEMA-designated flood zones, which triggers a mandatory flood insurance requirement on top of your standard homeowners policy. That's not a reason to avoid riverside areas, but it is a reason to ask your agent for the flood zone determination before you fall in love with a property — and to budget the additional insurance premium into your monthly cost calculation.
Underbudgeting the Cash at Closing
First-timers consistently undercount what they need at the table. Down payment gets all the attention during saving, but closing costs — lender origination fees, title insurance, prepaid homeowners insurance, prepaid property tax escrow, and recording fees — add another 2% to 3% on top. On a $270,000 purchase that's roughly $5,400 to $8,100 in additional cash, due at the same moment as the down payment. Build that figure into your savings target from day one, not as a surprise two weeks before closing.
Local Expert Takeaway: St. Anthony is one of the few Eastern Idaho cities where a first-time buyer earning close to the median household income can genuinely reach ownership without extraordinary savings. The $290,325 city-wide median (Zillow Home Value Index, May 2026) puts a move-in-ready three-bedroom within reach at FHA minimums for a household that has saved diligently. The practical moves: get pre-approved at Bank of Idaho's local branch or with a lender who knows Fremont County comps, keep your inspection contingency on any older home, and ask your agent about flood zone status before touring anything near the Henry's Fork. The market rewards buyers who arrive prepared — and has patience for those who don't.
Quick Takeaways & FAQs
✅ St. Anthony's city-wide median home price of $290,325 (May 2026) makes it one of the most accessible ownership markets in Eastern Idaho for first-time buyers.
⚠️ Older housing stock throughout the city can carry deferred maintenance costs that first-timers underestimate — never waive the inspection contingency here.
📍 Bank of Idaho maintains a branch directly in St. Anthony, so buyers can complete mortgage pre-approval with a community lender without driving to Rexburg or Idaho Falls.
What credit score do I need to buy a home in St. Anthony, Idaho?
How long does it take to close on a house in St. Anthony?
Are there enough homes for sale in St. Anthony for a first-time buyer?
Is St. Anthony a good place to buy if I work in Rexburg or Idaho Falls?
What are closing costs like when buying in St. Anthony?
Moving to Idaho?
Tell us what you need help with and we'll connect you with local resources.
