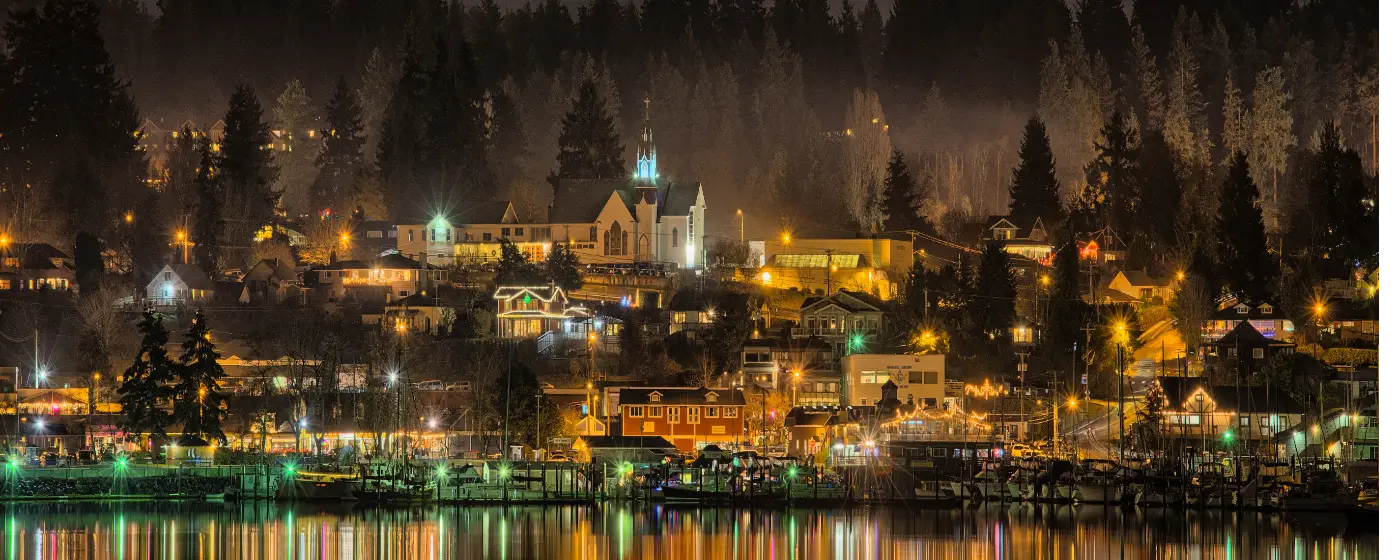
Maybe you've been priced out of Bainbridge Island — where prices run noticeably higher — and someone mentioned Poulsbo as the more affordable alternative across the inlet. Maybe you're stationed at Naval Base Kitsap and trying to figure out if buying makes more sense than renting in this market. Either way, Poulsbo's first-time buyer landscape is more nuanced than its small-town, Scandinavian-bakery exterior suggests. With a Zillow Home Value Index of $672,676 (2026), this is not an entry-level market in the traditional sense, and the competition is real: Redfin scores Poulsbo an 83 out of 100 on its Compete Score, rating it "Very Competitive." Homes go pending in roughly 8 days on average. You need a plan before you start scrolling Zillow.
The buyers who succeed here typically share one trait: they understood the Kitsap County context before they made an offer. Poulsbo sits on the western shore of Liberty Bay, connected to Highway 305 and the Kingston ferry route — two corridors that shape where people live and how far they're willing to commute toward Seattle (roughly 60 minutes on a normal day). The market draws a real mix: military families taking advantage of VA loan eligibility near the base, remote workers who traded a Seattle apartment for a three-bedroom with a yard, and Kitsap County locals moving up from rental. Single-family detached homes make up about 67% of the housing stock, with three- and four-bedroom homes the most common configuration — useful to know when you're budgeting, because condos and townhomes that might ease entry-level access in other markets are genuinely scarce here.
Poulsbo's overall cost of living runs approximately 16% above the national average, which matters for first-timers building a total monthly budget. The mortgage payment is the headline number, but property insurance, utilities, and day-to-day expenses in a market like this add up faster than buyers from lower-cost regions expect. The upside: inventory has expanded significantly, with roughly 210 active listings in mid-2026 — up about 54% year-over-year — giving you more choices than buyers had in 2022 or 2023. And a spring 2026 market update noted some softening in Poulsbo specifically, creating pockets of negotiating room that didn't exist before. For a fuller look at what living here costs beyond the mortgage, that page has the complete breakdown.
Whether you're trying to figure out what your budget actually buys, how the local offer process works, or what mistakes to avoid, the sections below walk through Poulsbo's buying reality step by step — from first pre-approval call to closing day at a Kitsap County title company.
The Poulsbo First-Time Buyer Reality
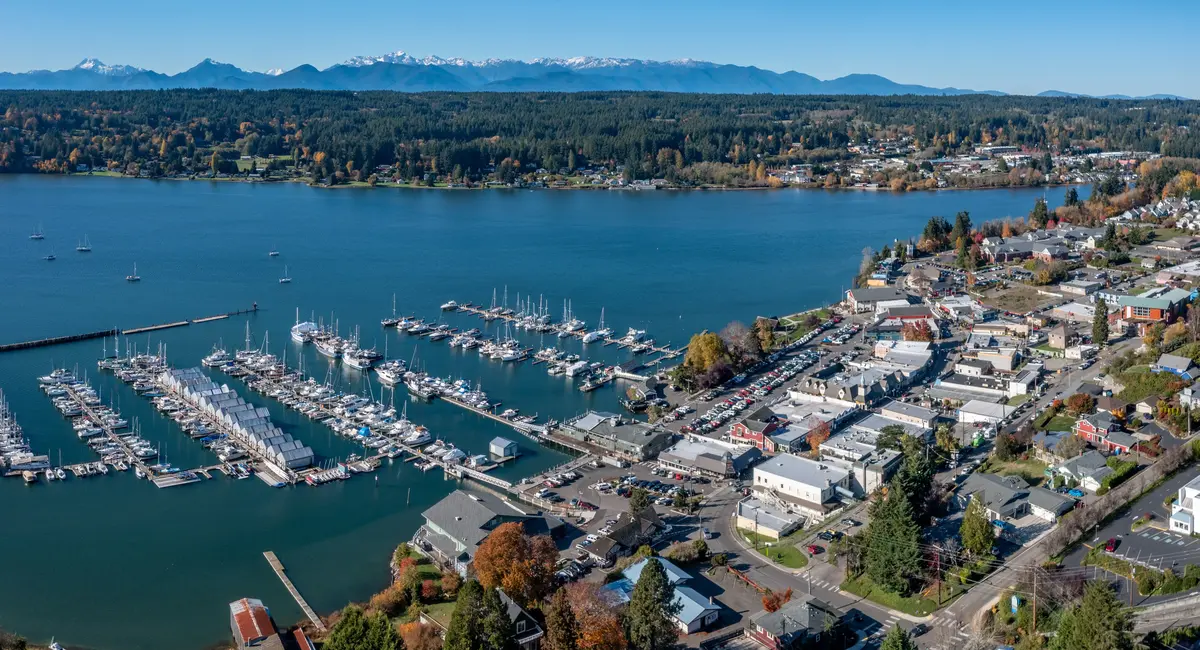
The Zillow Home Value Index for Poulsbo sits at $672,676 (2026) — a figure that lands most first-timers in a different category than they expected. This is not a market where a 3% conventional down payment gets you into a turnkey three-bedroom near Liberty Bay Waterfront Park without stretching your finances. It's a market where your down payment strategy, your pre-approval ceiling, and your willingness to move fast all determine what you actually get to choose from.
Entry-level in Poulsbo typically means the low-to-mid $500,000s for older construction, smaller lots, or homes in areas like Bond Road or Olhava that trade some of the walkable downtown character for more space and lower price points. Below $500,000, options are thin and competition is sharp — roughly 29% of all Poulsbo homes sell above list price, and the hottest listings go pending in as few as 3 days. At the median and above, the market opens up to three- and four-bedroom detached homes that represent the bulk of what's available.
The one structural advantage in Poulsbo that many first-timers overlook: a meaningful share of buyers here are VA-loan eligible due to proximity to Naval Base Kitsap. If that applies to you, it changes your calculus significantly — no private mortgage insurance (PMI) requirement, no down payment mandate, and potentially a stronger offer position depending on seller circumstances. For buyers without VA eligibility, the math centers on how much cash you can bring to closing and whether FHA or conventional financing fits your credit and debt profile better. Neither path is easy at Poulsbo price points, but both are real options with the right preparation.
The Homebuying Process in Poulsbo, Step by Step
Step 1: Get Pre-Approved — Before You Tour Anything
In Poulsbo's market, showing up to a tour without a pre-approval letter is not just inefficient — it's a liability. Sellers and listing agents here expect to see a lender letter with any offer. More importantly, the pre-approval process often reveals surprises (debt-to-income ratios, credit score gaps, or a lower ceiling than expected) that take weeks to address. Do this first, before you fall in love with a house on Front Street.
FHA loans allow down payments as low as 3.5% with a credit score of 580 or above, and carry a more flexible debt-to-income ceiling (up to 57%) than most conventional options. Conventional loans start at 3% down but require stronger credit and tighter DTI ratios — typically 45–50%. If you put less than 20% down on a conventional loan in Washington, you'll carry PMI until you reach the required equity threshold. Run both scenarios with your lender; the monthly difference can shift which price range actually makes sense for your household.
Step 2: Shop With a Clear Scope
With 210+ active listings in mid-2026, there's more to see than in recent years — but Poulsbo is still a small market. Establish your must-haves early: proximity to Highway 305 for a Bainbridge Island ferry connection, a garage, a minimum lot size. Without clear filters, you'll spend weeks touring homes in different parts of town that are fundamentally different buying decisions.
Step 3: The Offer — Speed and Structure Matter
Poulsbo homes average 2 offers and go pending in roughly 8–12 days. That's fast enough that a same-day offer on a well-priced home is not unusual. Your agent should pull recent comparable sales — not just list prices — and advise on whether an escalation clause makes sense. In a market where 29% of homes sell above list, assuming you can come in low is often the first mistake.
Step 4: Inspection and Appraisal
Do not waive your inspection in Poulsbo. Older homes in the Downtown/Front Street area and Lemolo can carry deferred maintenance, septic considerations, or moisture issues that are common in the Pacific Northwest climate and invisible to an untrained eye. An inspection contingency is your protection; the cost to remove it rarely saves a deal in a market where sellers are already getting multiple offers.
The appraisal is lender-ordered and largely out of your control, but understand this: if you've offered above list price and the home appraises low, you'll need to cover the gap in cash, renegotiate, or walk. Know your limit before you write an above-list offer.
Step 5: Closing
Washington is an escrow state — closings are handled through a title or escrow company, not a closing attorney. Expect the process to take 30–45 days from mutual acceptance to keys. The Washington State Housing Finance Commission requires an approved homebuyer education course (available free online or for $50 as a self-study option) if you're accessing any state mortgage programs — complete this early, before you're in escrow and scrambling. Budget time for it alongside your pre-approval process.
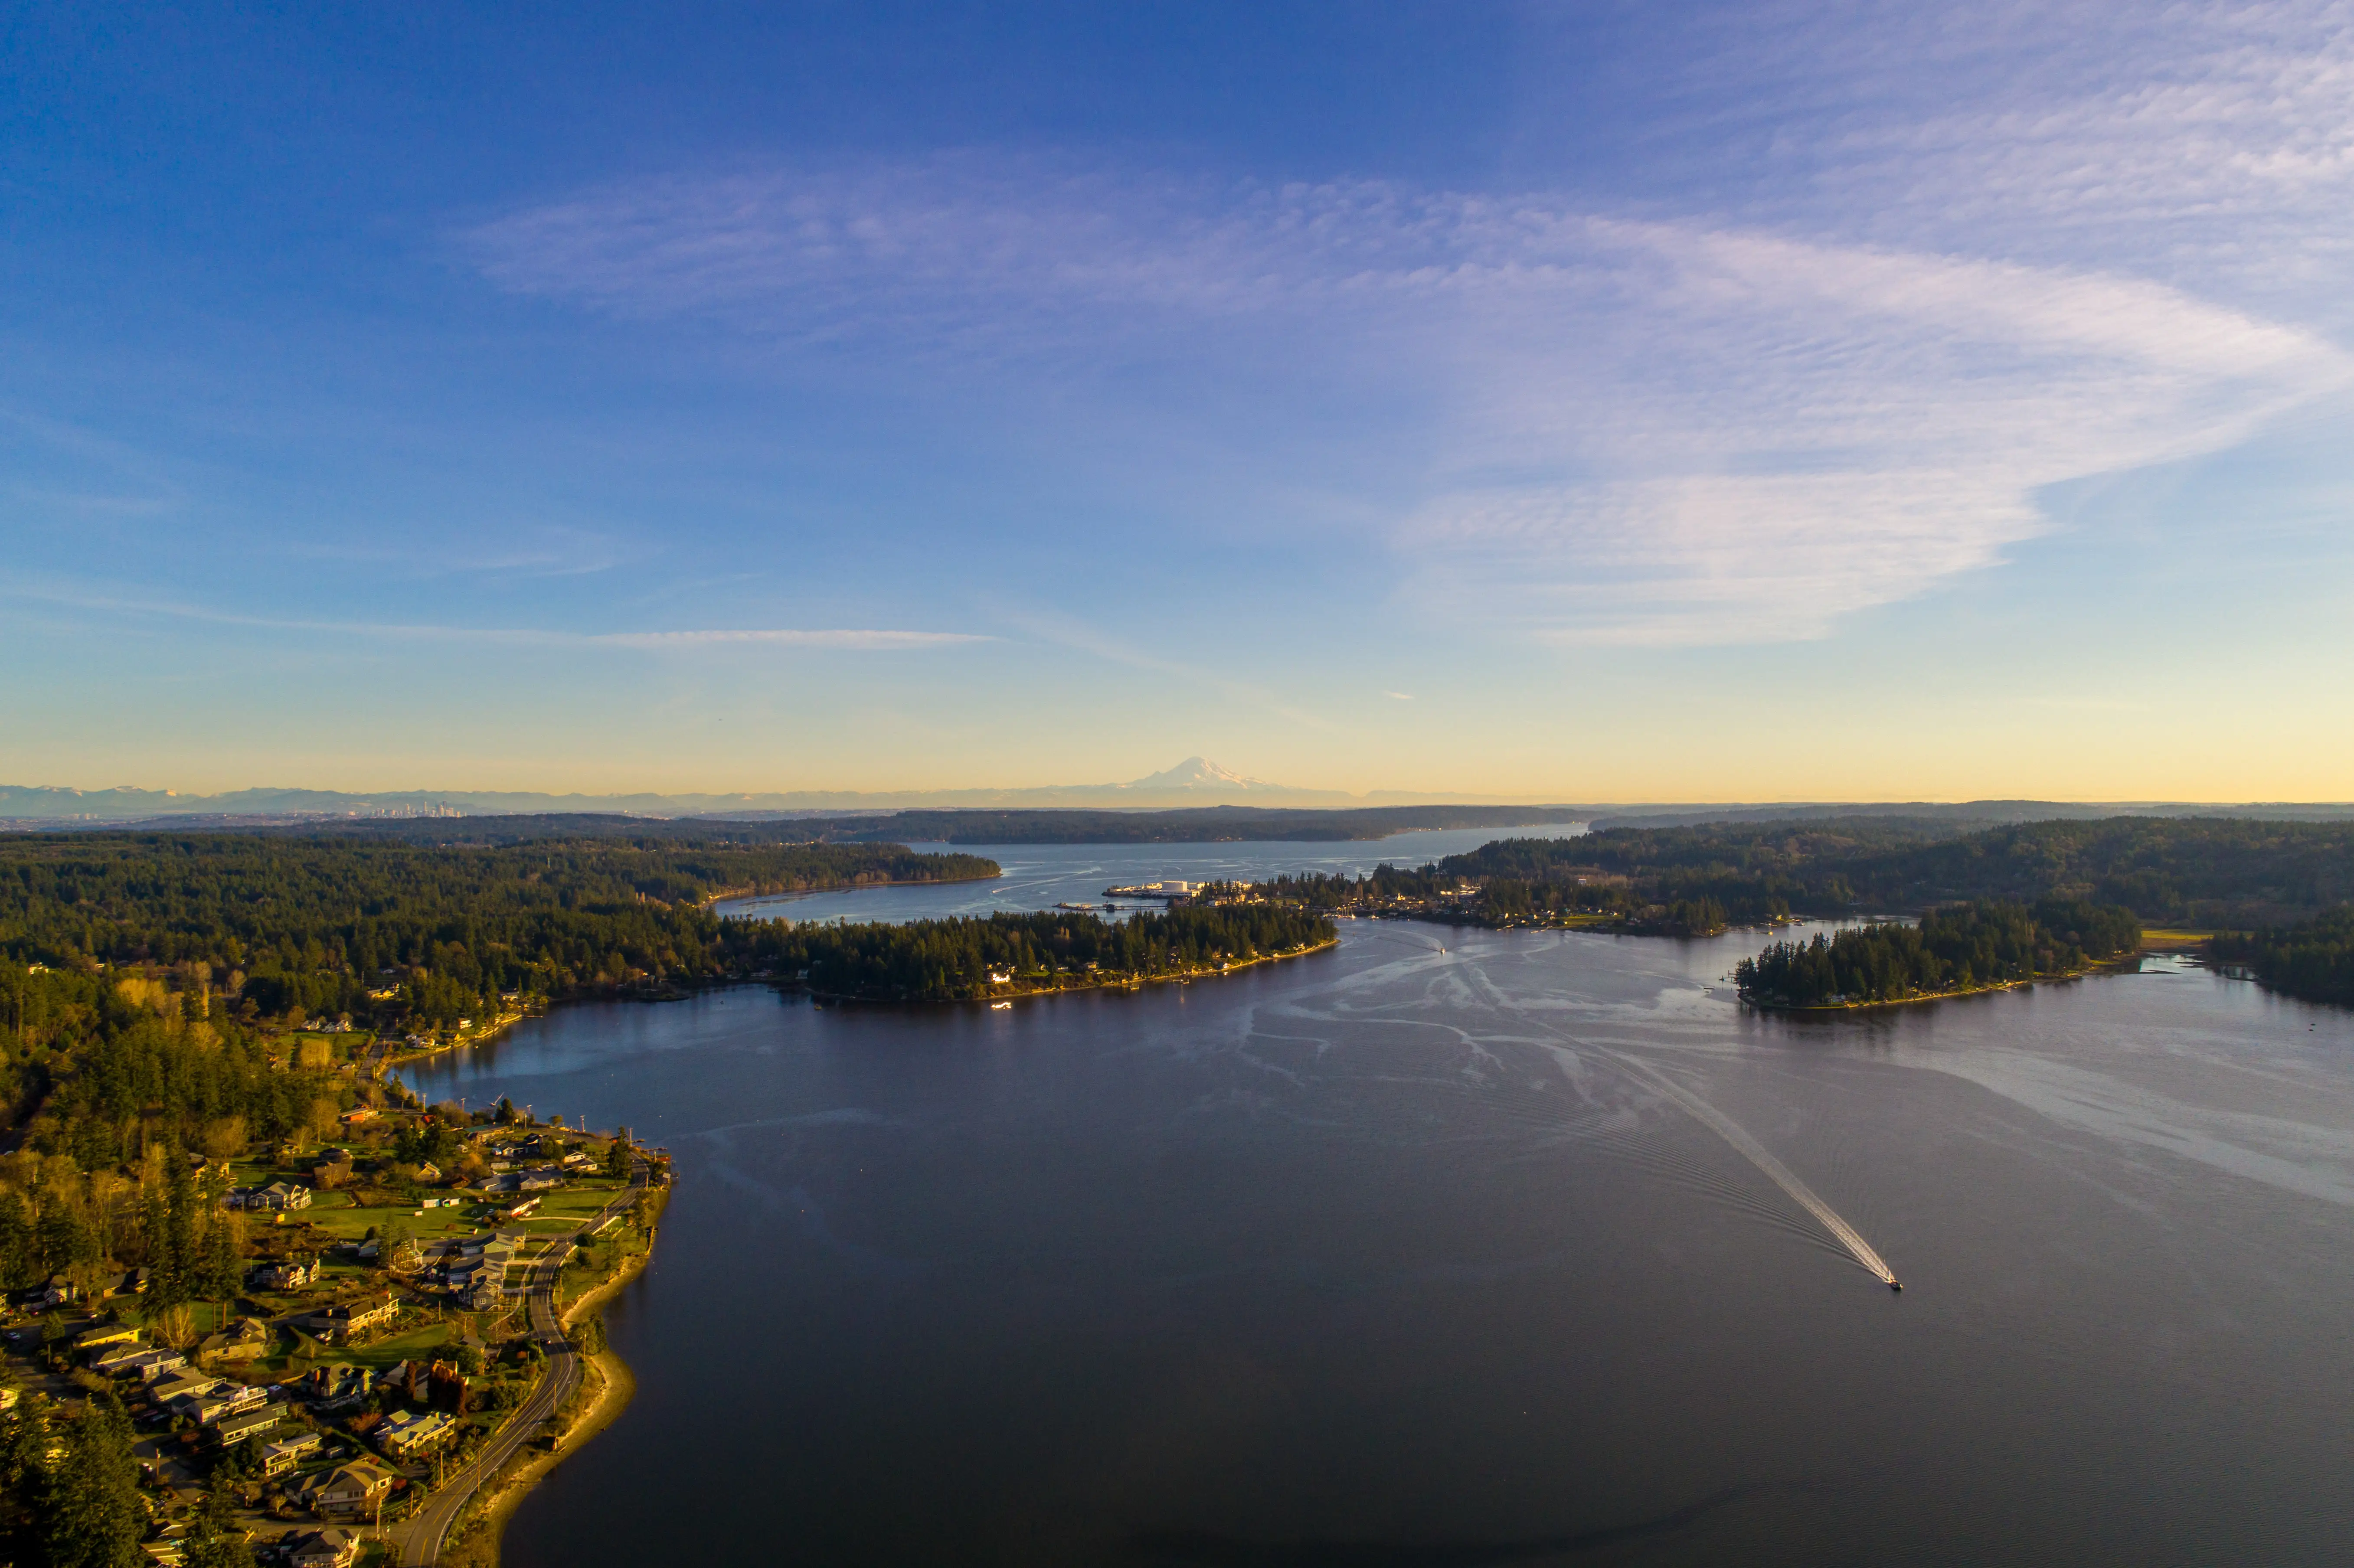
How Much Home Can You Afford in Poulsbo
The table below lays out five realistic purchase scenarios for a Poulsbo first-time buyer. Closing costs in Kitsap County typically run 2–3% of the purchase price, covering title, escrow, lender fees, and prepaid items. The "Cash Needed at Table" column combines down payment and estimated closing costs — this is the figure to match to your actual savings before you tour a single home.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (2–3%) | Cash Needed at Table |
|---|---|---|---|---|
| FHA — 3.5% down, entry-level | $500,000 | $17,500 (3.5%) | $10,000–$15,000 | ~$27,500–$32,500 |
| Conventional — 3% down, entry-level | $500,000 | $15,000 (3%) | $10,000–$15,000 | ~$25,000–$30,000 |
| FHA — 3.5% down, near-median | $600,000 | $21,000 (3.5%) | $12,000–$18,000 | ~$33,000–$39,000 |
| Conventional — 5% down, near-median | $650,000 | $32,500 (5%) | $13,000–$19,500 | ~$45,500–$52,000 |
| Conventional — 10% down, at median | $672,676 | $67,268 (10%) | $13,500–$20,200 | ~$80,700–$87,500 |
| Conventional — 20% down, at median | $672,676 | $134,535 (20%) | $13,500–$20,200 | ~$148,000–$154,700 |
All figures are estimates; your actual closing costs depend on lender, loan type, and negotiated seller concessions. Note that Kitsap County's effective property tax rate is approximately 0.80% annually — a line item many first-timers underestimate when building their true monthly housing cost. The interactive calculator below this section will let you model specific monthly payment scenarios once you've identified your target purchase price and down payment amount.
One structural note: buyers putting less than 20% down on a conventional loan will carry PMI — an added monthly cost that disappears once equity reaches the required threshold. VA loans available to eligible service members and veterans carry no PMI requirement, which can meaningfully lower the monthly payment at any of the price points above.
Looking to buy in Poulsbo? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Poulsbo quote.
Common First-Time Buyer Mistakes in Poulsbo
Shopping Before You Have a Pre-Approval Letter
In Poulsbo, a home you see on Monday can be under contract by Wednesday. First-timers who tour first and get pre-approved second routinely lose homes they wanted — sometimes by hours. The pre-approval process also surfaces issues (a credit card balance affecting your DTI, a student loan on income-based repayment that counts differently than you expected) that take real time to resolve. Start with the lender, not the listing.
Waiving the Inspection to Win an Offer
The pressure to compete can push first-time buyers toward waiving contingencies they shouldn't touch. In Poulsbo specifically, older homes in the Downtown/Front Street corridor and parts of Lemolo and Vinland were built in eras before modern moisture management standards. The Pacific Northwest climate is unforgiving on crawl spaces, rooflines, and older foundations. An inspection contingency costs you nothing if the home is solid, and saves you tens of thousands if it isn't. A pre-inspection (where allowed by the seller before offers are submitted) is a smarter competitive move than simply waiving.
Underbudgeting the Cash Needed at Closing
The down payment number is the one that gets all the attention, but closing costs in Kitsap County — title, escrow, lender origination fees, prepaid homeowners insurance, and property tax reserves — typically add another 2–3% of the purchase price on top. On a $600,000 home with a 3.5% FHA down payment, you need roughly $33,000–$39,000 in the bank, not $21,000. First-timers who calculate only the down payment routinely hit a wall in escrow. Run the full cash-to-close number with your lender before you fall in love with a price point.
Ignoring the Commute Reality Until After the Offer
Poulsbo is genuinely appealing — Sluys Poulsbo Bakery on Front Street, the Liberty Bay waterfront, a real small-town main street — and that appeal can cause buyers to underweight what the daily commute actually looks like. If your job requires in-person time in Seattle, your route runs through the Bainbridge Island ferry connection or south through Silverdale — neither of which is a casual commute. Drive it on a Tuesday morning, not a Saturday afternoon, before you commit. Buyers who skip this step and buy in Olhava or Bond Road for the price savings sometimes find themselves spending more time commuting than they budgeted, which changes the lifestyle math entirely.
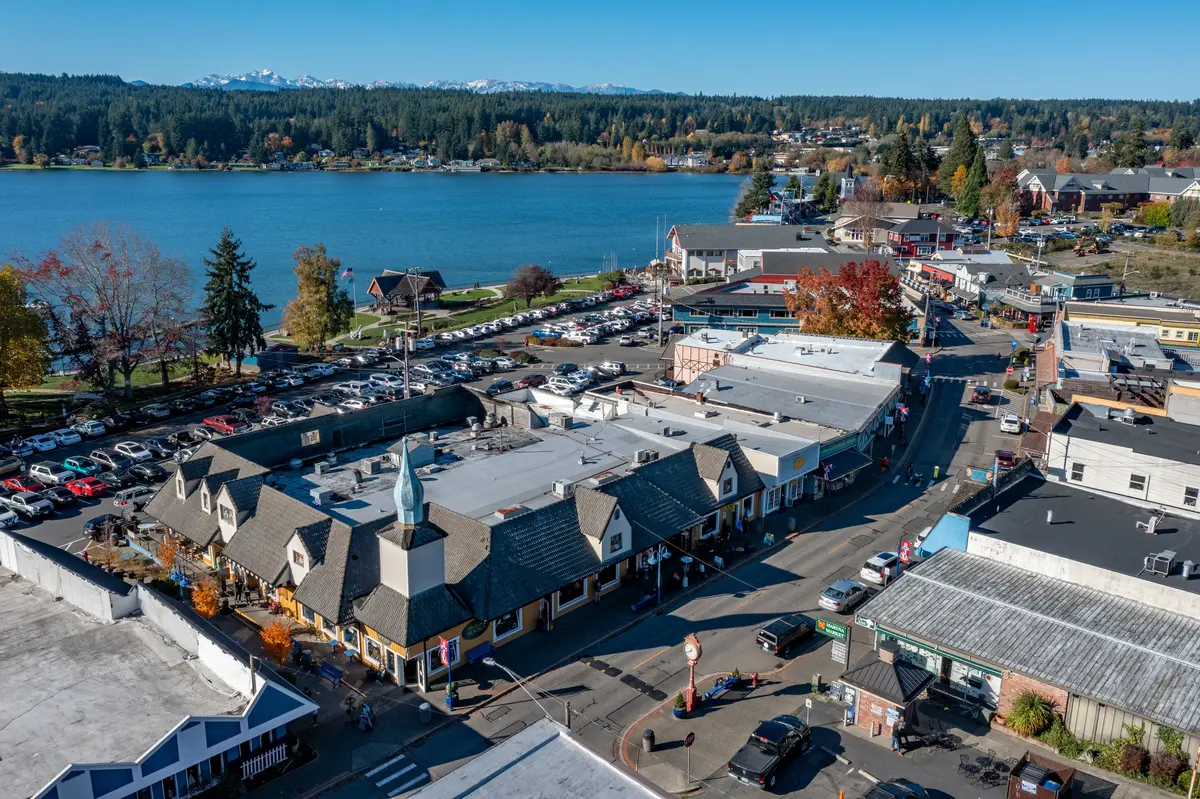
Local Expert Takeaway: Poulsbo's inventory expansion in 2026 is real — there are more homes to choose from than at any point in recent years — but the market still moves fast enough that showing up unprepared costs you deals. Get your pre-approval done before you tour. Know your total cash-to-close number, not just your down payment. If you're VA-eligible, lean into it: at Poulsbo price points, skipping PMI is a material monthly advantage. And before you write an offer on anything east of Highway 305 near Bond Road or Olhava, drive your actual commute on an actual workday — the small-town appeal of Front Street and the Poulsbo Marina looks very different from 45 miles away at 7 a.m.
Quick Takeaways & FAQs
✅ Poulsbo's mid-2026 inventory is up roughly 54% year-over-year, giving first-time buyers more options than the market has offered in years.
⚠️ The cash needed at closing in Poulsbo typically runs $25,000–$90,000+ depending on price point and loan type — budgeting only the down payment is one of the most common first-timer errors here.
📍 VA loan eligibility is unusually common in this market given Naval Base Kitsap's proximity, and the no-PMI benefit is especially significant at Poulsbo's $672,676 median price point.
What credit score do I need to buy a home in Poulsbo?
How much do I realistically need saved to buy in Poulsbo?
Is Poulsbo a buyer's or seller's market right now?
Can I use a VA loan to buy in Poulsbo?
How long does it take to close on a home in Poulsbo?
Moving to Washington?
Tell us what you need help with and we'll connect you with local resources.
