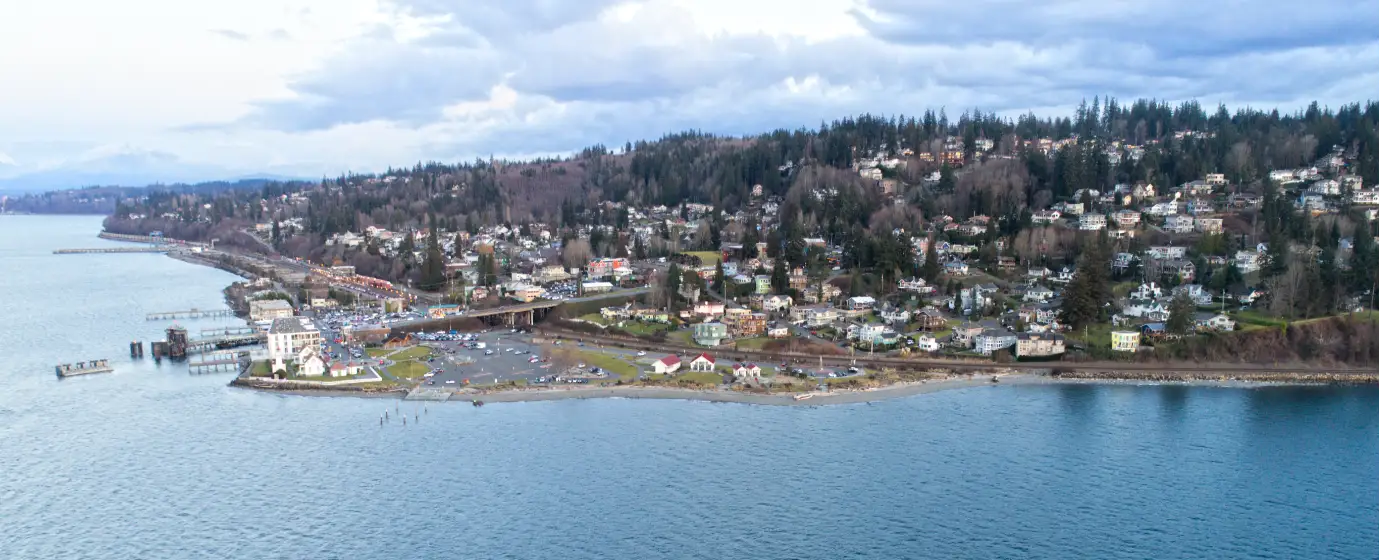
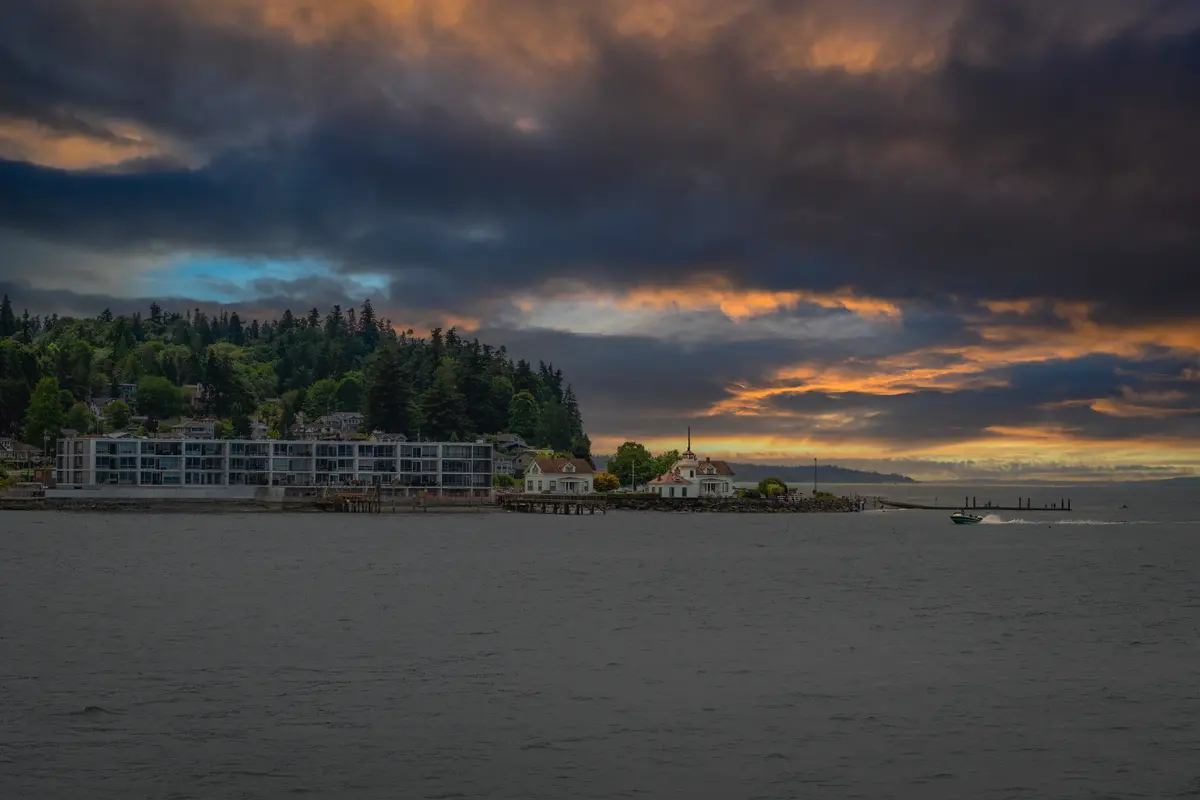
Maybe you've been priced out of Seattle and someone pointed you toward Mukilteo. Maybe you work at Boeing's Everett complex or at Electroimpact and you're done with the commute from farther south. Either way, you've landed on a city that delivers real Puget Sound waterfront character — the Mukilteo Lighthouse, the ferry terminal, the kind of Front Street scene where an independent brewery and a waterfront seafood spot sit a short walk apart — at prices that are high by national standards but meaningfully below Seattle proper. The catch is that "below Seattle" still means serious money, and first-time buyers who arrive without a clear-eyed plan often lose ground fast.
The city's Zillow Home Value Index for 2026 sits at $863,937, which tells you immediately that this is not a soft entry market. Snohomish County's high-cost designation is a structural advantage worth understanding: it pushes both conventional and FHA loan ceilings to $1,063,750 for a single-family home, which means most Mukilteo purchases at or near the Zillow Home Value Index midpoint stay within reach of standard loan programs rather than requiring specialty financing. Boeing and Electroimpact anchor a technically skilled workforce, and the roughly 30-minute run to Seattle via I-5 or SR-525 draws buyers who want waterfront living without a full Seattle price tag. For a fuller picture of what daily costs look like once you're here, see the cost of living in Mukilteo page.
The inventory picture is the part that will shape your experience most directly. Washington State entered 2026 with roughly a 2.2-month supply of homes statewide — well below the six months that defines a balanced market — and Mukilteo is tighter than that average. Well-priced homes routinely go under contract within a week. Homes that debut overpriced can sit for two months. That spread matters: it means knowing your price range, your financing structure, and your target neighborhoods before you ever schedule a showing.
Whether you're setting a budget for the first time or ready to make your first offer, the sections below break down what a first-timer's budget actually buys in Mukilteo, the local buying process step by step, an affordability snapshot table, and the specific mistakes that cost first-time buyers the most in this market.
The Mukilteo First-Time Buyer Reality
The Zillow Home Value Index for Mukilteo stands at $863,937 (2026) — and that figure is not a ceiling, it's a midpoint. Actual closed transactions through May 2026 have run closer to $949,000, which means a buyer whose budget tops out near the Zillow Home Value Index is competing for the lower half of available inventory. That's not disqualifying, but it shapes every decision you make from pre-approval onward.
Entry points exist, and they're concentrated in specific product types. Condos and townhomes offer comparatively accessible footholds in Mukilteo, and they're often eligible for standard financing given Snohomish County's high-cost loan ceiling. That's where most first-timers start their search. View-corridor properties and waterfront-adjacent homes are a different conversation — those frequently exceed $1 million and draw move-up competition that most first-timers can't match on contingency terms alone.
Speed is the other reality. Homes here sell in approximately 7 days on average, faster than the broader Snohomish County average of roughly 12 days. A well-priced townhome can go under contract before a buyer who toured on the weekend even has time to sleep on it. First-timers who treat Mukilteo like a slower, deliberate market — taking a week to discuss whether to make an offer — will consistently lose to buyers who came in prepared.
The Homebuying Process in Mukilteo, Step by Step
Step 1: Get Fully Pre-Approved — Before You Tour Anything
In most markets, pre-approval is a formality you complete before making an offer. In Mukilteo, it's a prerequisite for touring. A listing agent receiving multiple offers will not take a buyer seriously without a fully documented pre-approval letter — not a pre-qualification, not a soft credit pull. Your lender needs W-2s, tax returns, pay stubs, and bank statements in hand before you step foot in a showing.
Lenders who can close quickly — 21 to 25 days instead of 30 to 45 — are a genuine competitive advantage here. Ask your lender directly what their average close time looks like in the current volume environment. That answer matters as much as the rate quote.
Step 2: Define Your Loan Structure and Credit Position
Conventional loans in this market typically require a credit score of 620 or higher. FHA loans can work with scores as low as 580 for the 3.5%-down option, and Snohomish County's $1,063,750 FHA ceiling covers nearly every Mukilteo purchase at or near the Zillow Home Value Index. Private mortgage insurance (PMI) applies when you put less than 20% down on a conventional loan — understand when it drops off relative to your purchase price before you finalize your structure.
Your debt-to-income ratio matters as much as your credit score. Most programs cap total monthly debt obligations at just under 50% of gross income; FHA and VA loans have some flexibility above that threshold. Model this before you tour, not after you fall in love with a property.
Step 3: Shop with a Focused Criteria List
Because Mukilteo inventory is thin, going in with a five-neighborhood, five-feature wish list will leave you perpetually watching deals close on homes that were 80% of what you wanted. Narrow to two or three priority areas and decide in advance which concessions you can accept. Condos and townhomes are your most realistic entry point; detached single-family homes near the water are where the competition gets sharpest.
Step 4: Write a Clean, Competitive Offer
Multiple-offer situations are the norm, not the exception, for well-priced Mukilteo listings. A clean offer means a strong earnest money deposit (typically 2–3% of purchase price), a realistic closing timeline, and contingencies that don't look like escape hatches. The two most commonly negotiated contingencies here are inspection and financing — more on which one to protect and which one to sharpen in the mistakes section below.
Step 5: Inspection, Appraisal, and the Path to Closing
Washington State requires a home inspection, and in Mukilteo's older Goat Trail and Norma Beach neighborhoods — where homes can date to the 1950s and 1960s — inspection findings are rarely clean. Budget time and mental energy for a negotiation after inspection. The appraisal comes shortly after mutual acceptance; because Snohomish County's loan ceiling is high, appraisal gaps are less common here than in markets where purchases routinely bump against lower loan limits, but they do occur in bidding-war situations.
Closing in Washington runs through a title and escrow company, not an attorney. Closing costs typically run 2–3% of the purchase price and include lender fees, title insurance, escrow fees, and prepaid items — see the budget table in the next section for scenario-level estimates.
How Much Home Can You Afford in Mukilteo
The table below shows six purchase scenarios relevant to Mukilteo's first-time buyer market. Closing cost estimates assume approximately 2.5% of the purchase price. These are estimates — your actual figures will vary based on your lender, loan type, and negotiated terms. The interactive calculator below the table will let you model monthly payments against these down payment levels.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs | Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5%) — condo/townhome entry | $650,000 | $22,750 (3.5%) | ~$16,250 | ~$39,000 |
| Conventional (3%) — condo/townhome entry | $650,000 | $19,500 (3%) | ~$16,250 | ~$35,750 |
| FHA (3.5%) — near ZHVI midpoint | $864,000 | ~$30,240 (3.5%) | ~$21,600 | ~$51,840 |
| Conventional (5%) — near ZHVI midpoint | $864,000 | $43,200 (5%) | ~$21,600 | ~$64,800 |
| Conventional (10%) — detached single-family | $950,000 | $95,000 (10%) | ~$23,750 | ~$118,750 |
| Conventional (20%) — no PMI, detached | $950,000 | $190,000 (20%) | ~$23,750 | ~$213,750 |
* ZHVI = Zillow Home Value Index.
The 20%-down scenario eliminates private mortgage insurance entirely and meaningfully reduces your monthly obligation — but it requires keeping roughly $214,000 liquid at closing, which most first-timers in Mukilteo simply don't have. FHA at 3.5% down is the most common path to entry here, and the county's high-cost loan ceiling makes it viable across the full Zillow Home Value Index range.
One number worth tracking: Mukilteo's effective property tax rate is approximately 0.79%. That figure feeds directly into your lender's debt-to-income calculation as part of your total housing payment — see the cost of living page for more on Mukilteo's broader tax picture.
Looking to buy in Mukilteo? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Mukilteo quote.
Common First-Time Buyer Mistakes in Mukilteo
Touring Without a Pre-Approval in Hand
This is the mistake that stings the most, because it's invisible until it's too late. A buyer who tours without pre-approval, finds a home they love, then spends a week getting their documents together will almost always lose that home. In a market where the average days-on-market is 7, the documentation gap is the whole timeline. Get pre-approved first — fully documented, not just a quick estimate from an online form.
Waiving the Inspection Contingency Without a Strategy
In competitive offer situations, some buyers waive their inspection contingency entirely to look cleaner. In Mukilteo's older neighborhoods — particularly Goat Trail, Norma Beach, and Boulevard Bluffs, where mid-century construction is common — that's a real risk. A better approach: keep the inspection contingency but shorten the inspection period to 5 days instead of 10, or conduct a pre-inspection before submitting your offer. Waiving entirely on a 1960s home without a prior walk-through is the kind of decision buyers regret after closing when the crawlspace tells a different story.
Skipping School Boundary Verification
Buyers with school-age children often purchase based on a district-level impression without verifying which specific school serves a given address. In Mukilteo, two homes a half-mile apart can have different assignments based on where they fall within attendance boundaries. Confirm the boundary for any property you're seriously considering — don't assume proximity to a school means assignment to it.
Underbudgeting Closing Cash
The down payment is the number buyers fixate on. Closing costs — lender origination fees, title insurance, escrow fees, and prepaids — add another 2–3% of the purchase price on top of it. On an $864,000 purchase, that's roughly $17,000–$26,000 that needs to be liquid on closing day, separate from your down payment. Many first-timers in Mukilteo arrive at mutual acceptance with a down payment sized correctly and closing costs only partially covered, which requires a scramble or a renegotiation. Build both into your savings target from day one.
Waiting for Rates to Drop Before Buying
The prevailing 30-year fixed rate in the Mukilteo area is approximately 6.67% (as of April 2026), with forecasters projecting only modest movement through year-end. Buyers who arrived in 2022 expecting a sharp drop spent three years watching prices climb while rates stayed elevated. The local inventory shortage — roughly 2.2 months statewide, tighter in Mukilteo specifically — means waiting for a rate environment that may not arrive is a strategy that costs you in purchase-price appreciation. The more durable approach: buy at a price your budget supports today, and refinance if rates meaningfully improve.
Local Expert Takeaway: Mukilteo rewards buyers who arrive prepared and penalizes those who improvise. Get fully documented pre-approval from a lender who can close in under 25 days, narrow your search to two target areas — condos and townhomes as entry points, or detached single-family homes if your budget stretches above the Zillow Home Value Index midpoint — and treat Snohomish County's $1,063,750 FHA loan ceiling as the structural advantage it is. A well-priced home here goes under contract in under a week; you won't have time to deliberate once you find the right one. Celebrate your offer acceptance with a walk along Front Street to the waterfront — it's the kind of moment that confirms why you chose Mukilteo over somewhere easier to buy but less worth living in.
Quick Takeaways & FAQs
✅ Snohomish County's high-cost loan designation pushes the 2026 FHA ceiling to $1,063,750, meaning most Mukilteo purchases at or near the $863,937 Zillow Home Value Index are financeable without specialty loan products.
⚠️ Mukilteo homes average just 7 days on market — buyers who haven't completed full pre-approval documentation before they start touring will routinely lose homes they could have had.
📍 Condos and townhomes are the city's most accessible first-time entry points, while waterfront and view-corridor properties regularly clear $1 million and draw competing offers from buyers trading up.
What credit score do I need to buy a home in Mukilteo?
How much cash do I need to buy a home in Mukilteo as a first-timer?
Is Mukilteo a competitive market for first-time buyers?
What types of homes are most accessible for first-time buyers in Mukilteo?
Should I wait for mortgage rates to drop before buying in Mukilteo?
Moving to Washington?
Tell us what you need help with and we'll connect you with local resources.
