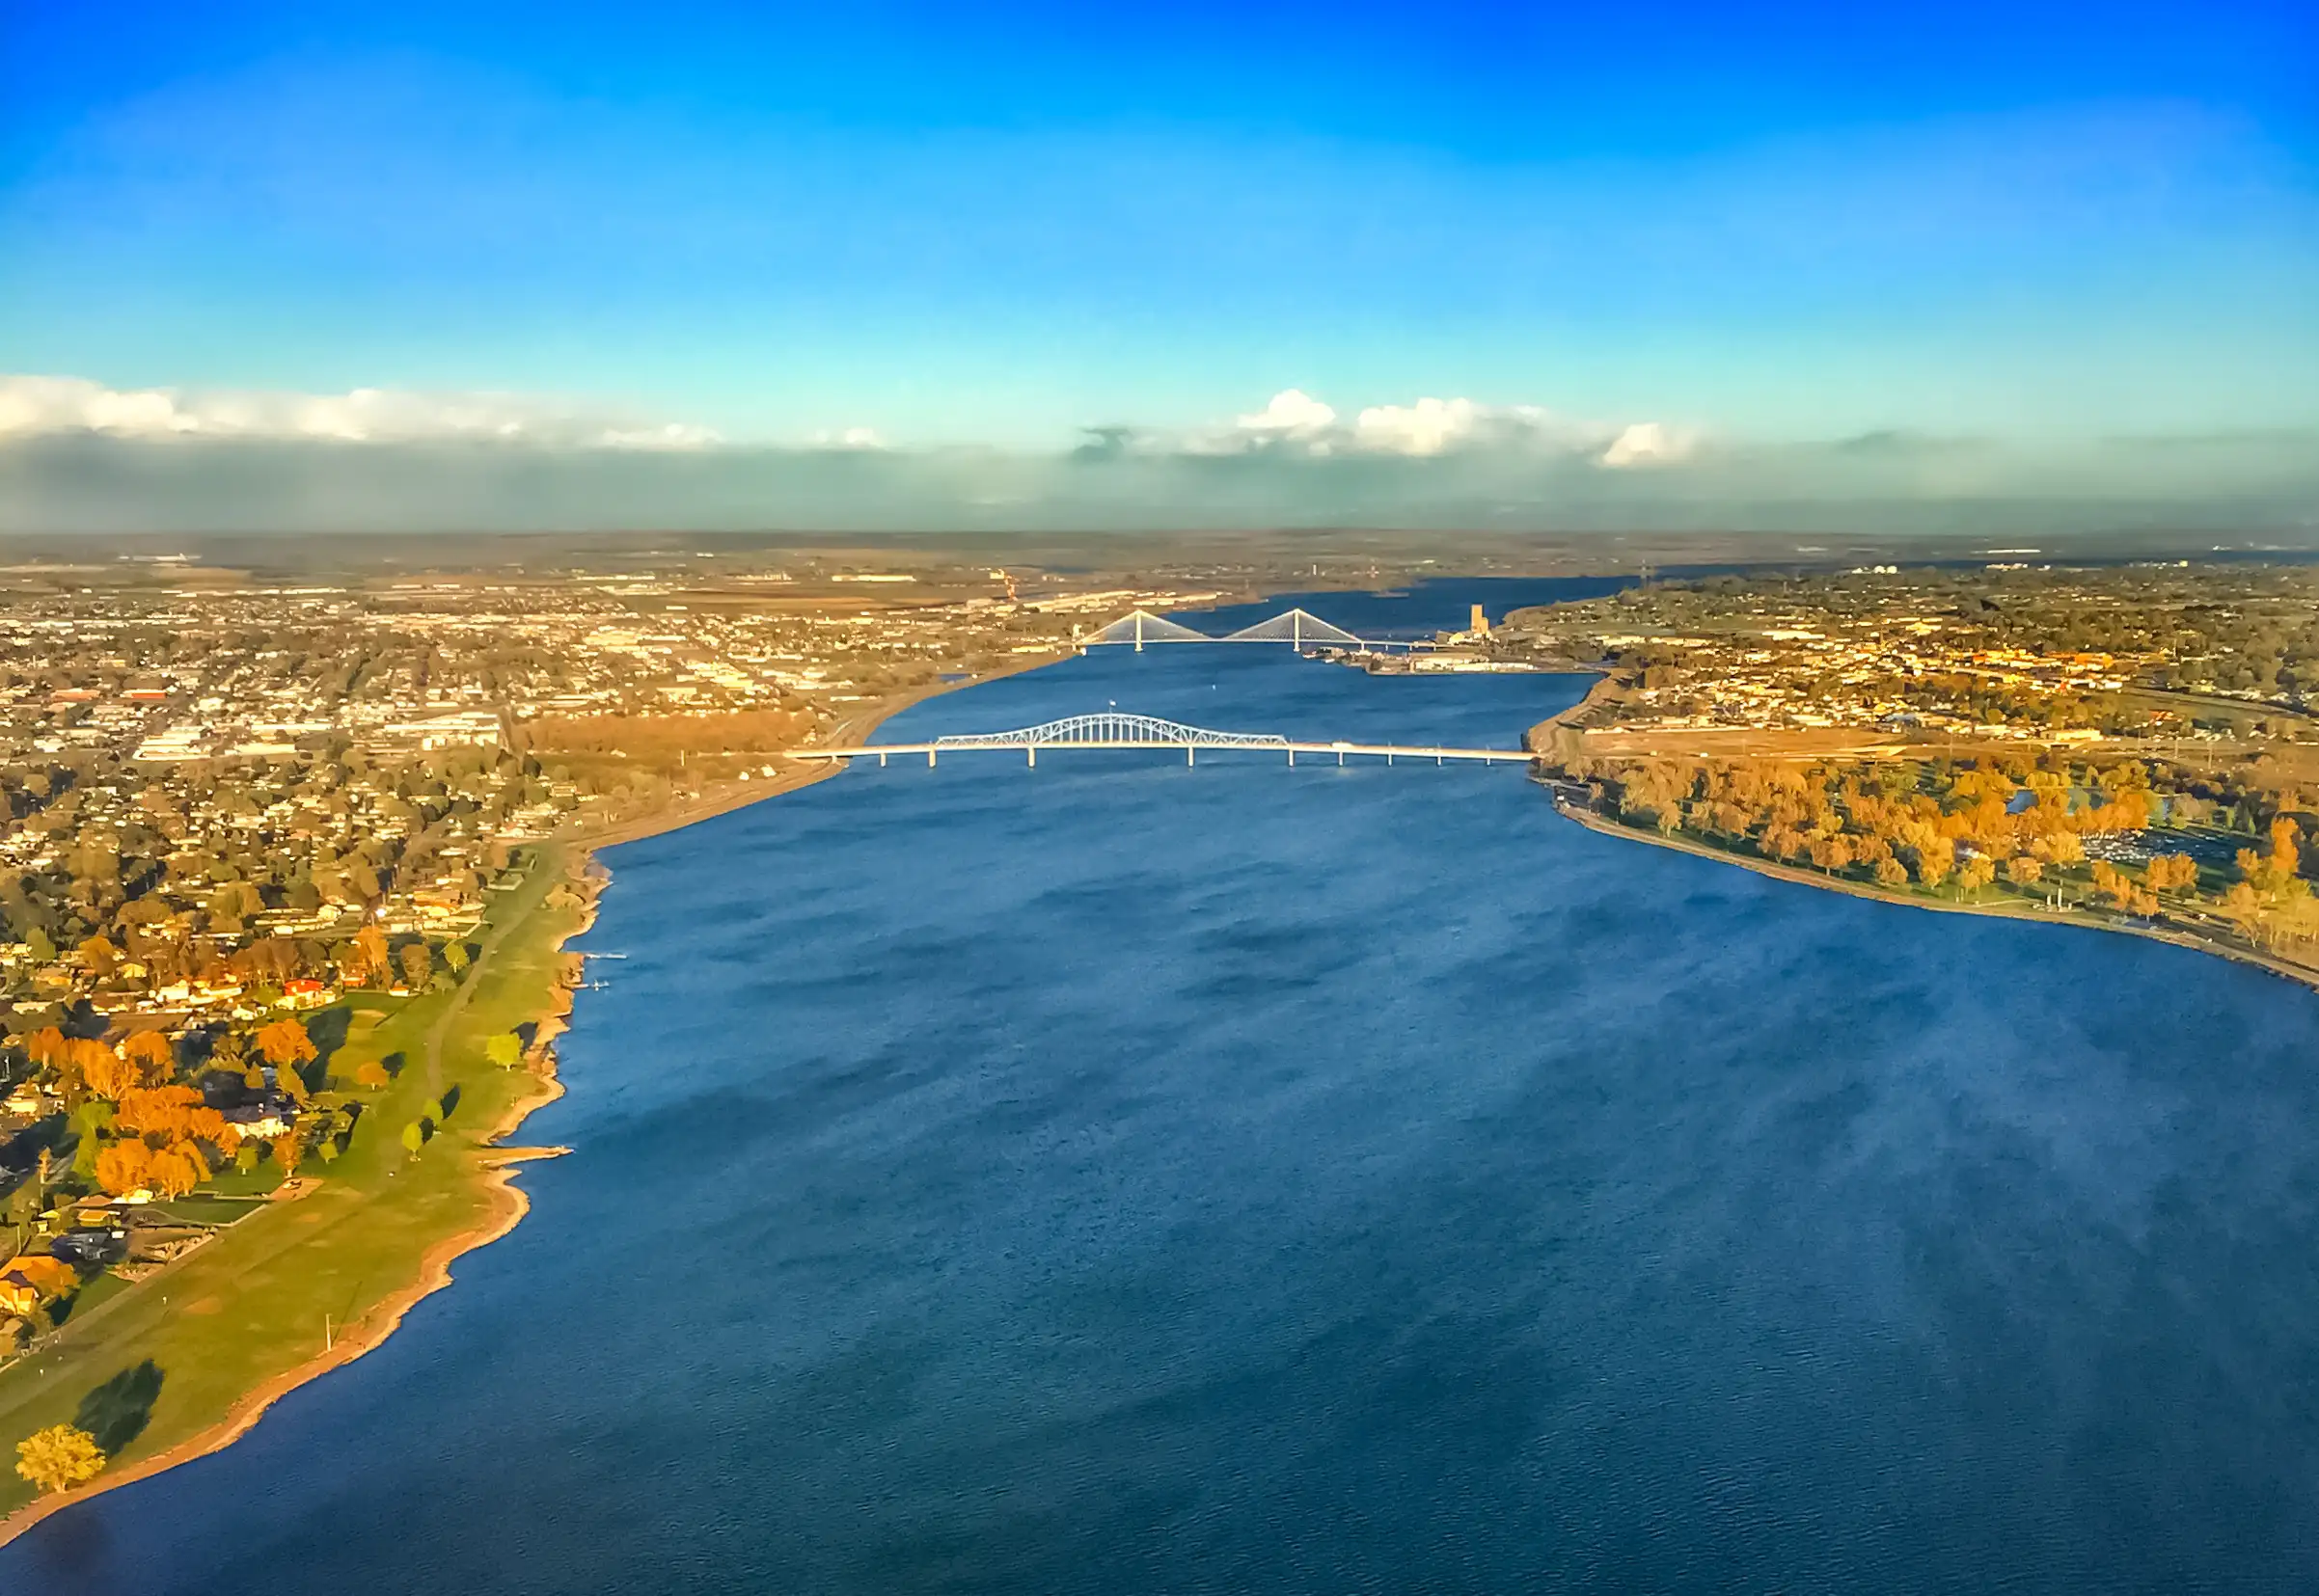
Maybe your company is relocating you to the Tri-Cities. Maybe you've been watching Seattle prices climb for years and someone mentioned Kennewick as a place where a first-time buyer can still actually close. Either way, the thing that surprises most newcomers is how competitive a mid-$400s market can feel. Kennewick sits along the Columbia River in Benton County in south-central Washington, and the access logic of the whole region — Richland to the north, Pasco across the river — shapes which neighborhoods go fast and which sit longer.
The economic foundation here is genuinely diverse for a city of under 90,000 people. Lamb Weston and Tyson Fresh Meats anchor the food-processing sector; Numerica Credit Union and a range of regional employers round out the local job base; and a significant slice of buyers work at federal science and energy facilities nearby. That employment mix means demand holds up even when broader market sentiment softens — which is exactly why first-timers who show up without pre-approval in hand consistently lose to buyers who did the paperwork first.
On price, Kennewick sits noticeably below western Washington metros — a fact that has not gone unnoticed. Seattle-area buyers were among the largest out-of-metro groups searching here in late 2025, followed by buyers from Yakima and further afield. For a full picture of what your dollar buys here relative to your take-home pay, see the cost of living in Kennewick breakdown. Day-to-day life revolves around the Columbia River Riverfront Trail, the Vista Field mixed-use district (a former airport now mid-redevelopment), and a growing dining and coffee scene along West Kennewick Avenue.
Whether you're making your first offer or still figuring out how much you need in the bank, the sections below walk through the Kennewick market reality for first-timers, the step-by-step buying process, an honest budget table, and the specific mistakes that cost local buyers deals.
The Kennewick First-Time Buyer Reality
The Zillow Home Value Index for Kennewick stood at $433,734 as of June 2026 — up modestly year-over-year and confirmed by Redfin's median sale price of approximately $432,000 for the three months ending May 2026. That figure is not a ceiling; it's the middle of the market. Entry-level homes — think older ranch-style construction in West Hill or Hansen Park, sometimes with deferred maintenance — start closer to the low-to-mid $300s, while newer builds in Southridge or Canyon Lakes push well above the city-wide figure.
The competitive pressure is real but not punishing. Homes went to pending in around 24 days as of June 2026 (Zillow Home Value Index), and Redfin tracked an average of 41 days on market for the same general period — down from 50 days the prior year. That narrowing window means well-priced homes in move-in condition move fast, often within the first weekend. Overpriced or dated listings sit, which creates opportunity for buyers willing to look past cosmetics.
First-timers targeting the $320,000–$380,000 range will find the most competition. That band captures the bulk of inventory accessible to buyers using low-down-payment loan programs, and everyone in that income tier is fishing in the same pond. Going in pre-approved, with a flexible closing timeline, genuinely shifts how sellers perceive your offer — especially against buyers who've written letters but haven't done the loan paperwork.
The Homebuying Process in Kennewick, Step by Step
Step 1: Get Pre-Approved Before You Tour Anything
This is not a formality in Kennewick — it's a filter. A listing agent here will often ask a buyer's agent whether their client is pre-approved before scheduling a showing on a competitively priced property. Pre-approval in Washington requires a full loan application: pay stubs, W-2s or two years of tax returns if self-employed, two to three months of bank statements, and a government-issued ID. Most lenders turn the review around in one to three business days once documents are submitted.
Shop at least two lenders. Multiple mortgage credit inquiries made within approximately 45 days count as a single inquiry for credit-scoring purposes, so the comparison costs you almost nothing on your score. For conventional loans, lenders typically look for a credit score of 620 or higher and pay close attention to your debt-to-income ratio — not just the number, but what's driving it.
Step 2: Define Your Search Before You Fall in Love
Kennewick's neighborhoods read very differently from each other. Decide before your first showing whether proximity to the riverfront, access to major corridors, or the character of the surrounding streets matters more — those priorities will point you toward different parts of the city. Your agent should be able to pull active inventory filtered by those criteria, not just price.
Step 3: Writing the Offer
In a market where desirable homes go pending in under a month, your offer needs to be clean: pre-approval letter attached, earnest money that signals commitment (typically 1–2% of purchase price in this market), and a realistic closing timeline. Sellers in Kennewick are often simultaneously buying or have already purchased — flexibility on your close date can matter as much as a few thousand dollars in price.
Step 4: Inspection and Appraisal
Washington State strongly favors keeping an inspection contingency. The first-timer mistake here is treating inspection as a deal-killer search rather than an information-gathering exercise. A good inspector on a 1980s West Hill ranch will find things — aging HVAC, original plumbing, minor foundation settling. Most of those findings inform a repair request or a price negotiation, not a reason to walk. The appraisal is ordered by your lender and protects both parties; if the appraised value comes in below purchase price, you'll need to negotiate a price reduction, make up the gap in cash, or walk away with your earnest money intact (if you have an appraisal contingency).
Step 5: Closing
Closings in Washington are handled through an escrow company — you won't sit across a table from the seller. You'll sign documents a day or two before the recorded closing date, funds transfer on closing day, and keys are released once recording is confirmed. Budget for closing costs of 2% to 5% of the purchase price; at the city-wide typical price point, that range runs roughly $8,700 to $21,700 in addition to your down payment.
How Much Home Can You Afford in Kennewick
The table below uses Kennewick's current market price points and Washington State's standard closing-cost range (2%–5% of purchase price) to show what you'll need in liquid cash at the table for several realistic scenarios. Closing costs here include lender fees, appraisal, title insurance, escrow, recording fees, and prepaid taxes and insurance — they don't include moving costs or immediate repairs. Use the mortgage calculator below the table to model monthly principal and interest for any of these scenarios.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (2%–5%) | Est. Total Cash Needed |
|---|---|---|---|---|
| FHA (3.5%) — entry-level | $320,000 | $11,200 (3.5%) | $6,400–$16,000 | ~$17,600–$27,200 |
| Conventional (3%) — entry-level | $320,000 | $9,600 (3%) | $6,400–$16,000 | ~$16,000–$25,600 |
| FHA (3.5%) — city median | $433,734 | $15,181 (3.5%) | $8,675–$21,687 | ~$23,856–$36,868 |
| Conventional (3%) — city median | $433,734 | $13,012 (3%) | $8,675–$21,687 | ~$21,687–$34,699 |
| Conventional (5%) — mid-market | $400,000 | $20,000 (5%) | $8,000–$20,000 | ~$28,000–$40,000 |
| Conventional (10%) — upper entry | $480,000 | $48,000 (10%) | $9,600–$24,000 | ~$57,600–$72,000 |
All figures are estimates based on Washington State closing-cost norms (Sammamish Mortgage, August 2026) and Kennewick market price points as of mid-2026. Actual closing costs vary by lender, loan type, and transaction specifics.
One figure first-timers consistently underestimate: Washington State has no income tax, which helps monthly cash flow, but closing costs here are on the higher end of the national range because of mandatory title insurance and escrow fees. Budget toward the 3%–4% midpoint rather than the 2% floor and you'll avoid a last-minute scramble.
Looking to buy in Kennewick? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Kennewick quote.
Common First-Time Buyer Mistakes in Kennewick
Shopping Before Pre-Approval
Walking open houses on a Saturday morning feels productive. It isn't — not in Kennewick's current market. Homes at the $350,000–$400,000 price point regularly go pending before a second weekend. If you've toured a home and fallen for it without pre-approval in hand, you're almost certainly too late, and the rushed pre-approval process that follows often surfaces document issues that could have been resolved weeks earlier.
Waiving Inspection to Win a Bidding Situation
Buyers occasionally waive the inspection contingency in competitive offer situations here, treating it as a negotiating chip. On a home built before 1990 in West Hill or Downtown Kennewick, that's a meaningful financial risk. Older construction in this market commonly carries deferred HVAC service, original aluminum wiring in some homes, or settling that looks cosmetic but masks drainage issues. Keeping the inspection contingency and being specific about what's negotiable versus deal-breaking is the cleaner approach.
Underbudgeting the Cash Needed at Closing
The down payment number is the one first-timers rehearse. The closing costs — which run 2% to 5% of purchase price in Washington — are the number that blindsides them at final disclosure. On a $430,000 purchase, that's potentially $21,000 on top of your down payment. Factor this in during your savings target phase, not the week before closing.
Ignoring the Effective Property Tax Rate
Washington has no state income tax, and Kennewick's effective property tax rate is approximately 0.80% — not a punishing number, but real. First-time buyers laser-focused on the purchase price sometimes don't model the full monthly housing cost until after pre-approval. That figure — along with homeowner's insurance — belongs in your budget math from day one, not as an afterthought once you're already shopping. The cost of living page has more context on how taxes here compare across the region.
Locking In a Neighborhood Without Verifying Boundaries
Buyers sometimes commit to a specific area of Kennewick based on a street name or general neighborhood label, then discover that practical service boundaries — utility districts, HOA coverage areas, even certain city service zones — don't line up with the informal name they've been using. Before making an offer, verify exactly which jurisdiction and district apply to the specific address, not just the broader area it's loosely associated with. Your agent can pull this from county records before you're under contract.
Local Expert Takeaway: Kennewick's first-time buyer window is real but narrowing at the entry-level price point. The buyers who close are the ones who treated pre-approval as step one — not step three — gathered documents before they found a house they loved, and budgeted for the full cash stack including closing costs. Being ready here means pre-approved, cash for 3%–5% above your down payment, and an inspection contingency you're prepared to use rather than waive. The buyers overheard debriefing at a coffee shop along the Riverfront after a day of showings are almost always the ones who got beat because they weren't ready yet.
Quick Takeaways & FAQs
✅ Kennewick's Zillow Home Value Index of $433,734 (June 2026) sits noticeably below comparable western Washington markets, giving first-timers real purchasing power — especially buyers relocating from the Seattle metro.
⚠️ Homes at the entry-level price point ($320,000–$380,000) are the most competitive segment in the market, going pending in under a month — buyers without pre-approval in hand consistently lose these deals.
📍 Washington State closing costs run 2%–5% of purchase price; on a $430,000 home that's up to $21,500 on top of your down payment — budget for the midpoint of that range, not the floor.
What credit score do I need to buy a home in Kennewick, WA?
How long does it take to buy a home in Kennewick once I find one I want?
What are typical closing costs for buyers in Kennewick, WA?
Is Kennewick a buyer's or seller's market right now?
Can I shop multiple lenders for pre-approval without hurting my credit score?
Moving to Washington?
Tell us what you need help with and we'll connect you with local resources.
