Maybe someone priced you out of Kirkland and a coworker mentioned Kenmore. Maybe you've been tracking SR-522 corridors on Zillow for six months and the numbers finally look possible — until you look harder. Kenmore sits at the north end of Lake Washington, where the lake drains into the Sammamish River, and that geography does two things simultaneously: it makes the city genuinely beautiful, and it keeps prices within striking distance of Bothell and Lake Forest Park while still reflecting the Seattle metro premium. The Zillow Home Value Index for Kenmore stood at $1,024,151 in June 2026 — a figure that surprises first-timers who expected lake-adjacent to mean cheaper than Kirkland, not marginally below it.
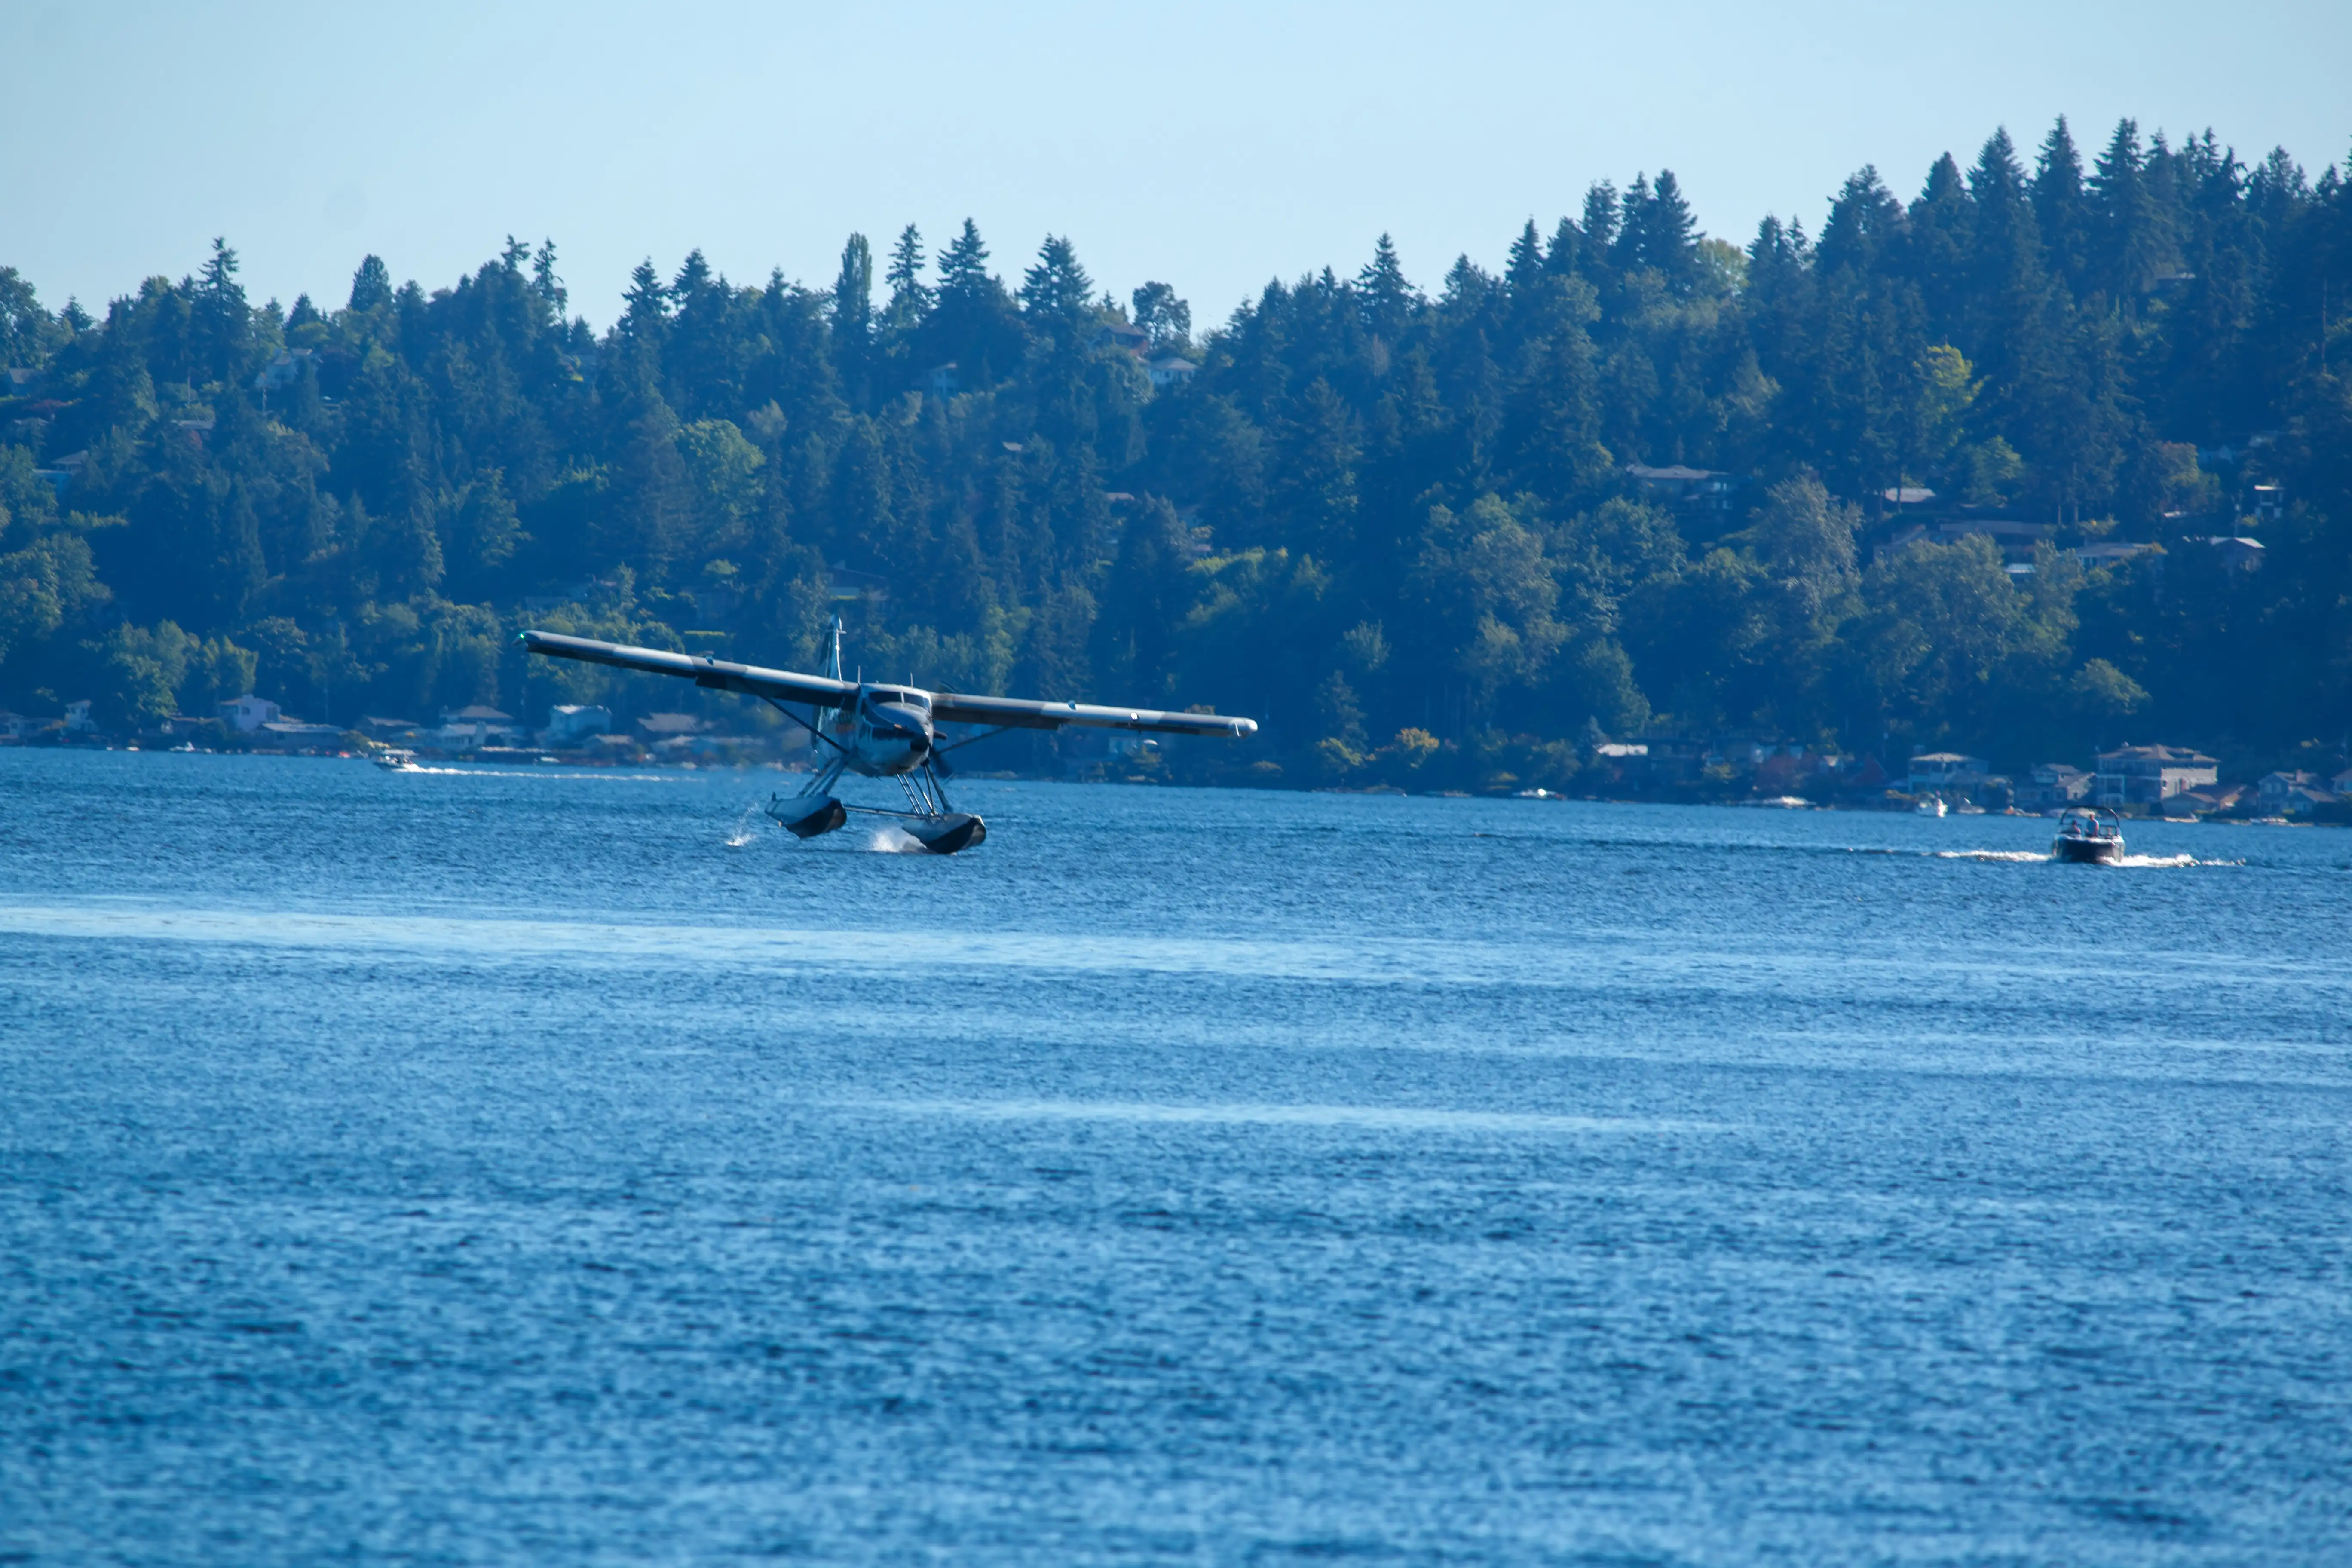
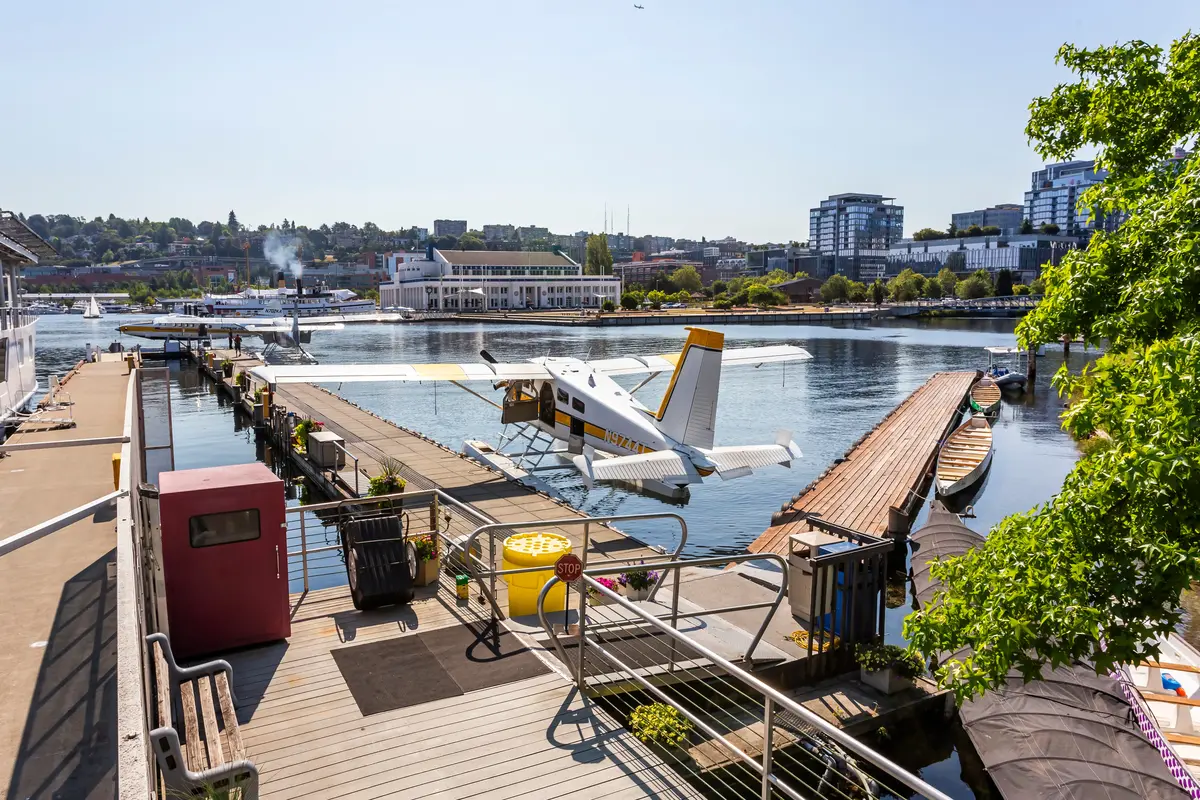
What keeps the buyer pool deep here is access. SR-522 gives commuters a 30-minute shot into Seattle and a quick flip onto I-405 toward the Eastside. Bastyr University and Kenmore Air Harbor anchor a small but stable local employment base, and the combination of commute convenience and lakefront amenity means Kenmore doesn't sit on the market long. Homes were going pending in approximately 19 days as of June 2026, and sellers were receiving 99.5% of list price. This is not a market where you show up casually.
For first-time buyers, Kenmore's housing stock is genuinely varied — mid-century hillside ramblers in Moorlands and Inglewood, newer townhome communities near The Hangar at Town Square, and the occasional older condo that can bring the entry point meaningfully lower than the city-wide median. The Burke-Gilman Trail, Log Boom Park, and the brewery and distillery taprooms along NE 175th St — anchored by Postdoc Brewing and Copperworks Distilling — give the city a lifestyle argument that holds up at resale. That's the real Kenmore equation: you pay close to seven figures, but you get a lake, a trail, and a usable downtown strip that future buyers will bid up for you.
Whether you're six months from making an offer or just running the math, the sections below break down what your budget actually buys in Kenmore, how the buying process works step by step, a cash-needed snapshot for realistic entry points, and the specific mistakes that cost first-timers here — sometimes their offer, sometimes tens of thousands of dollars.
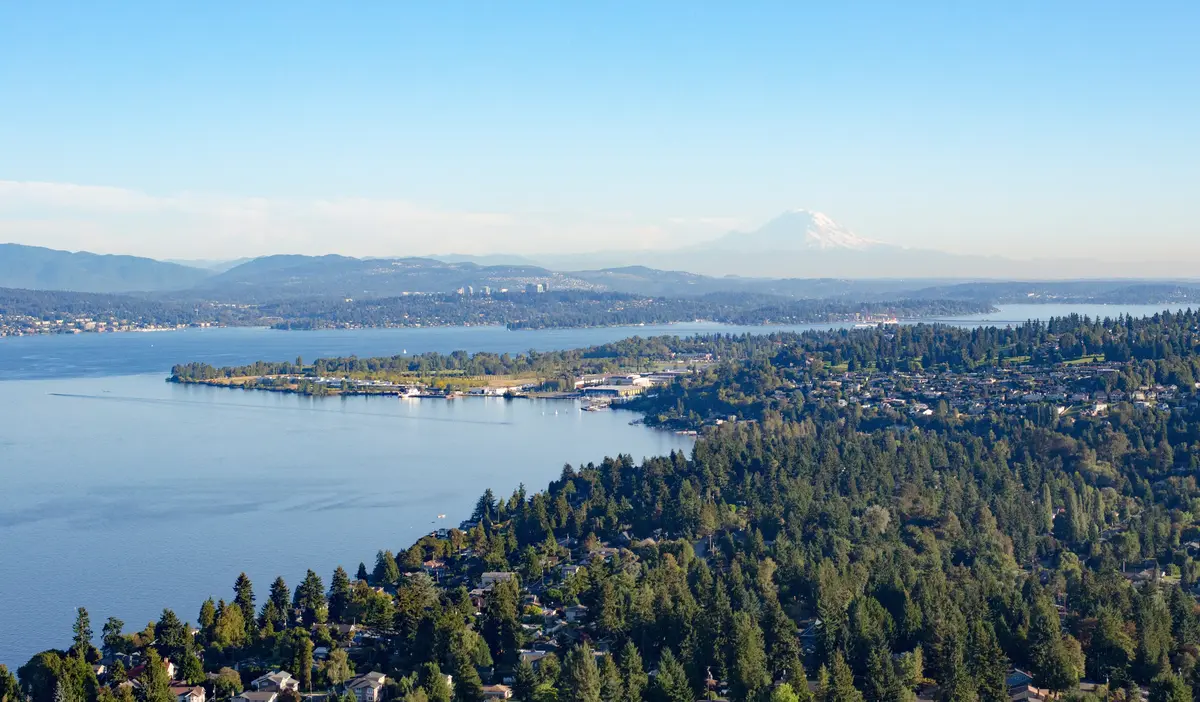
The Kenmore First-Time Buyer Reality
The Zillow Home Value Index for Kenmore reached $1,024,151 in June 2026 — and that figure is the central fact every first-time buyer here needs to internalize before anything else. It means the median transaction in this city is just above seven figures, and the entry point for a detached single-family home rarely starts at what most first-timers budget for. For most, that math points immediately toward townhomes and attached homes in the lower price bands, or older hillside ramblers that need work. Those exist, but you have to move fast. See the full cost-of-living breakdown for context on how Kenmore compares to neighboring cities.
Townhomes and newer attached homes near the Town Square corridor represent the most accessible entry point, but inventory is limited and competition is real. Buyers who set a hard ceiling and expect to find a detached home in move-in condition at that price will be disappointed — the detached stock that opens below the median is typically older, steeper, or in need of updating.
What first-timers often discover around month three: the listings that look affordable at first glance are priced that way because they need significant updating or sit on a busy SR-522 frontage road. The hillside neighborhoods — Moorlands, Arrowhead, Inglewood — offer more square footage per dollar, but the lots are steep and some streets are genuinely difficult to navigate in snow or ice. Kenmore gets enough winter weather that this matters. Buy with your eyes open about what you're accepting in exchange for a lower price point.
The Homebuying Process in Kenmore, Step by Step
Step 1: Get Pre-Approved — Before You Tour
In Kenmore, pre-approval is not a formality you handle after you find a house you love. With homes going pending in roughly 19 days, you will not have time to start the lender conversation once you're already emotionally attached to a listing. Pre-approval requires tax returns from the last two years, recent pay stubs, two to three months of bank statements, and employment verification. A pre-qualification letter — where a lender takes your word for your income — will not be taken seriously by a Kenmore seller receiving multiple offers.
Pre-approval also tells you something critical: the exact price ceiling you can credibly offer. In a market where the median is above $1,000,000, knowing your ceiling before you fall in love with a property prevents the most common and most painful first-timer mistake here.
Step 2: Find a Local Agent and Start Shopping
An agent who knows the difference between Uplake and St. Edward access roads, which Burke-Gilman Trail-adjacent blocks move fastest, and how the city's hillside lots behave in winter is worth the time to find. Start touring with an honest list of non-negotiables versus preferences — in Kenmore, trading a garage for a trail-adjacent location is a real decision buyers face regularly.
Step 3: Writing a Competitive Offer
With a 99.5% sale-to-list price ratio, Kenmore sellers are receiving essentially full asking price. Your first offer should be your best offer. Escalation clauses — where your offer automatically beats competing bids up to a ceiling — are common in this market and worth discussing with your agent before you need one. Coming in 3–5% below asking expecting to negotiate is a strategy that gets offers rejected here.
Step 4: Inspection and Appraisal
Washington State allows buyers to waive their inspection contingency, and in heated markets some do. For a first-time buyer in a city with significant mid-century housing stock, this is a risk that deserves serious thought. Older ramblers in Moorlands and Inglewood can carry deferred maintenance that isn't visible in listing photos — roofs, electrical panels, crawl space issues. Losing an inspection contingency to win a bidding war on a home that needs $60,000 in repairs erases your down payment advantage quickly.
The appraisal is lender-ordered and non-negotiable if you're financing. If a home appraises below the purchase price, you'll need to cover the gap in cash, negotiate a price reduction, or walk. In a market this competitive, appraisal gaps are a real scenario to plan for.
Step 5: Closing
Washington State uses escrow companies rather than attorneys to close real estate transactions. Closing typically takes 30–45 days from accepted offer. Budget for closing costs beyond your down payment — lender fees, title insurance, escrow fees, and prepaid items (homeowners insurance, property tax impounds) add up to roughly 2–3% of the purchase price. On a $900,000 home, that's $18,000–$27,000 on top of your down payment. Many first-timers underestimate this figure significantly.
How Much Home Can You Afford in Kenmore
The table below maps realistic entry points in Kenmore to the cash you'll need at the closing table. Closing cost estimates are approximate (2–3% of purchase price) and cover lender fees, title, escrow, and prepaids — they do not include moving costs or immediate repairs. The calculator below the table estimates monthly payments based on current rates; use it alongside these figures to understand your full monthly picture.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs | Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5%) — townhome / attached | $750,000 | $26,250 (3.5%) | ~$15,000–$19,000 | ~$41,000–$45,000 |
| Conventional (3%) — townhome / attached | $750,000 | $22,500 (3%) | ~$15,000–$19,000 | ~$37,000–$41,000 |
| FHA (3.5%) — older detached, needs work | $850,000 | $29,750 (3.5%) | ~$17,000–$21,000 | ~$47,000–$51,000 |
| Conventional (5%) — entry detached | $875,000 | $43,750 (5%) | ~$18,000–$22,000 | ~$62,000–$66,000 |
| Conventional (10%) — move-in ready detached | $950,000 | $95,000 (10%) | ~$19,000–$24,000 | ~$114,000–$119,000 |
| Conventional (20%) — median-priced home | $1,024,151 | $204,830 (20%) | ~$20,000–$25,000 | ~$225,000–$230,000 |
Note: FHA loans carry an upfront mortgage insurance premium (typically 1.75% of the loan amount) that is usually rolled into the loan rather than paid at closing, but it affects your loan balance and monthly cost. Conventional loans with less than 20% down require private mortgage insurance until you reach sufficient equity.
Kenmore's effective property tax rate is approximately 0.83%, and King County's 2025 assessment cycle included a 15% increase for Kenmore addresses driven by a new fire district levy. Budget for taxes using current assessed values, not the seller's prior-year bill — they may look meaningfully lower.
Looking to buy in Kenmore? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Kenmore quote.
Common First-Time Buyer Mistakes in Kenmore
Shopping Without Pre-Approval
In Kenmore's market, attending open houses without a pre-approval letter is an exercise in future regret. You will find a home, you will want to make an offer, and your agent will tell you the seller is reviewing offers in 48 hours. Pre-approval takes days, sometimes longer if documents are complex. Buyers who skip this step lose offers they were otherwise qualified to win — it happens here routinely.
Waiving the Inspection Contingency on Older Stock
Kenmore's mid-century ramblers in neighborhoods like Moorlands and Inglewood are genuinely appealing — larger lots, mature trees, more square footage per dollar than newer townhomes. They're also 50–70 years old. Waiving your inspection to compete is a legitimate strategy in some markets, but first-time buyers who do it on a 1960s hillside rambler without understanding what that crawl space or electrical panel might reveal are making a gamble that can cost far more than the deal was worth. At minimum, consider a pre-inspection before waiving.
Overlooking What a Boundary Line Does to Resale
Even if you don't have children, which public district assignment covers a Kenmore address affects how fast your home will sell when it's your turn to be the seller. Buyers with school-age children bid hard for addresses in well-regarded assignment zones, and that demand keeps resale velocity high. A home just outside a favored boundary can sit noticeably longer — ask your agent to pull days-on-market comparisons by assignment area, not just by zip code, before you make an offer on two otherwise comparable homes.
Underbudgeting Cash for Closing
First-timers consistently underestimate the gap between the down payment and the full amount of cash due at closing. On a $875,000 purchase with 5% down, you're writing a check for $43,750 — and then you need another $18,000–$22,000 for closing costs on top of that. That's roughly $62,000–$66,000 leaving your account on closing day, not $43,750. Build your cash reserve around the full closing figure, not just the down payment line.
Treating the First Offer as a Starting Negotiation
The 99.5% sale-to-list price ratio in Kenmore tells you something direct: sellers are getting essentially what they asked. A buyer who writes an offer expecting meaningful room to negotiate on a competitively priced listing will likely lose to the buyer who came in near asking, clean. In a market where homes move in under three weeks, your first offer needs to be competitive enough to survive the first review — there usually isn't a counteroffer round with multiple first-time buyers in the room.
Local Expert Takeaway: Kenmore rewards buyers who do the preparation work before they fall in love with a listing. Get pre-approved with documents in hand, not just a phone call to a lender. Tour the hillside neighborhoods — Moorlands, Arrowhead, Inglewood — to understand what entry-level Kenmore actually looks like on a steep lot in February. Walk the taproom strip on NE 175th St past Postdoc Brewing and Copperworks Distilling, and check the distance to the Burke-Gilman Trail from any home you're seriously considering, because that trail access is a resale asset. The buyers who struggle here are the ones who treat Kenmore like a negotiable market. It isn't. Come prepared, come with cash reserves that cover closing costs — not just a down payment — and make your best offer first.
Quick Takeaways & FAQs
✅ Kenmore's housing stock ranges from mid-century hillside ramblers to newer townhomes, giving first-timers multiple entry points below the $1,024,151 city-wide median — if you're willing to take on older construction or attached living.
⚠️ Homes in Kenmore go pending in roughly 19 days and sell at 99.5% of list price, which means lowball opening offers and slow pre-approval timelines will cost you deals rather than money.
📍 Kenmore buyers in 2025 faced a 15% property tax increase driven by a new fire district levy — budget using current assessed values, not the seller's prior-year tax bill, which may look meaningfully lower.
What is the minimum down payment to buy a home in Kenmore, WA?
How competitive is the Kenmore housing market for first-time buyers?
What types of homes are available at the entry level in Kenmore?
Should I waive my home inspection contingency to compete in Kenmore?
How much should I budget for closing costs in Kenmore?
Moving to Washington?
Tell us what you need help with and we'll connect you with local resources.
