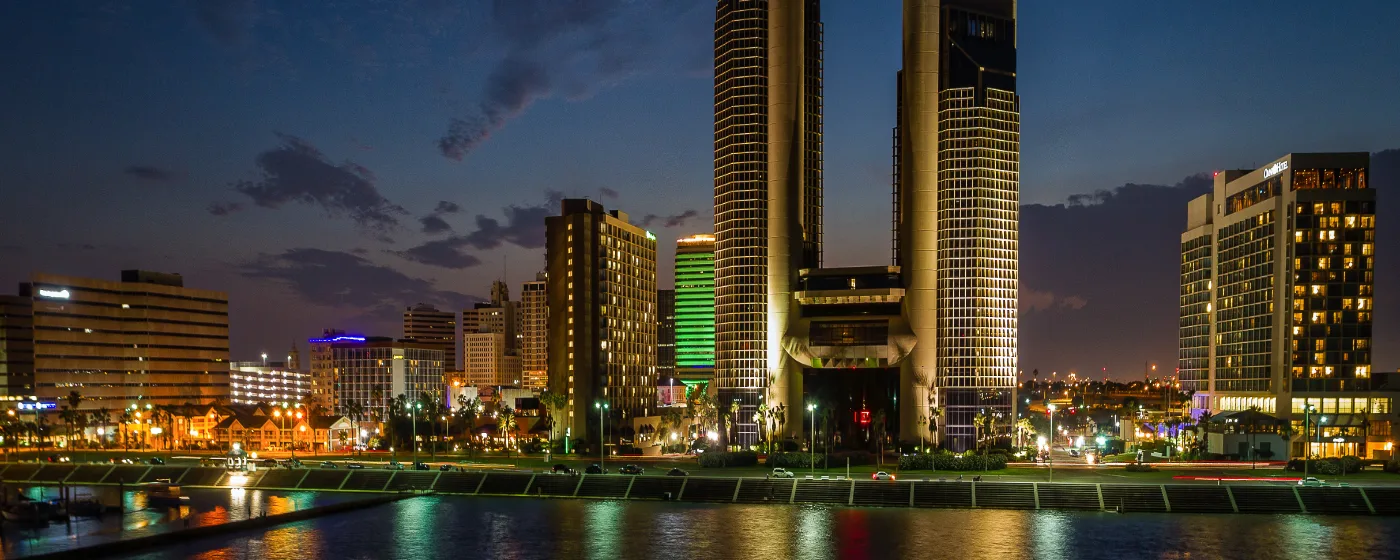
The number that surprises most first-time buyers looking at Corpus Christi is not the home price — it's the insurance bill. The typical home here sits at $224,996 (Zillow Home Value Index, July 2026), which is affordable by Texas coastal standards. But this is a Gulf Coast city that sits in hurricane country, and the combined cost of homeowners insurance, windstorm coverage through the Texas Windstorm Insurance Association (TWIA), and flood insurance can reshape a monthly budget in ways the purchase price alone never telegraphs. Understanding that full picture before you fall in love with a house is what separates a confident offer from a costly surprise.
Corpus Christi is Texas's 8th-largest incorporated city, a working port and military town of 317,247 people anchored by Naval Air Station Corpus Christi, the Corpus Christi Army Depot, CHRISTUS Spohn Health System, Valero's refinery operations, and the Corpus Christi Independent School District — which holds a B rating, according to the Texas Education Agency. These institutions create a stable, blue-collar-to-professional employment base that drives consistent housing demand across the Southside, Calallen, Flour Bluff, and Bay Area neighborhoods. The city draws buyers who are priced out of San Antonio or Austin, military families on PCS orders, and locals who are finally done renting after years of watching the market.
The median household income here is $67,394, which sits meaningfully below what it takes to carry the typical home at current rates — so budgeting precisely matters more than it does in markets where incomes have more cushion. The market is balanced rather than frenzied, meaning a well-prepared first-time buyer has genuine room to negotiate, including asking sellers to cover a portion of closing costs. For the full cost-of-living picture, see the cost of living in Corpus Christi page.
Whether you're a military spouse buying your first home near the base, a local renter finally making the leap, or a newcomer drawn by the waterfront and the relative affordability, the sections below walk through what your budget actually buys here, how the Texas purchase process works step by step, what cash you'll need at the closing table, and the specific mistakes that cost first-time Corpus Christi buyers real money.
The Corpus Christi First-Time Buyer Reality
The typical home in Corpus Christi sits at $224,996 (July 2026), which puts homeownership within reach for many buyers who could not afford a comparable home in Austin or the Houston suburbs. Entry-level product — older ranch homes in established neighborhoods, smaller townhomes near the base, modest stucco cottages in the Bay Area — can still be found below that figure. The Southside, Flour Bluff, and Calallen all run above the city median, so buyers working with tighter budgets often find their best footing in the Bay Area or in older, less-renovated pockets of the city.
The honest tension here is the insurance stack. Standard homeowners coverage for a Corpus Christi property runs well above the national average — one benchmark puts it at approximately $5,081 per year for $300,000 in dwelling coverage. Add a TWIA windstorm policy (averaging roughly $2,541 per year as of mid-2026) and separate flood insurance if your property sits in a federally designated high-risk flood zone, and the monthly cost of owning can be noticeably higher than the mortgage payment alone suggests. Any budget conversation that stops at principal and interest is incomplete.
The market here is balanced — neither the frenzied seller's market of a few years ago nor a slow buyer's market — which means a prepared buyer with pre-approval and realistic expectations is in a reasonably strong position. Sellers are willing to negotiate, and seller concessions on closing costs are genuinely available to first-timers who know to ask. The catch is that the buyers who get those concessions are the ones who arrived organized: pre-approved, with a clear sense of their price ceiling, and with an agent who knows the difference between a Flour Bluff flood-zone lot and one that isn't. Neighborhood character, school boundaries, and flood-zone status all vary more than the zip code suggests — the neighborhoods guide breaks that down in detail.
The Homebuying Process in Corpus Christi, Step by Step
Step 1: Get Pre-Approved Before You Tour Anything
This is the step most first-timers compress or skip entirely, and it costs them in two ways: they tour homes they cannot afford, and when they find the right one, they lose it to a buyer who already has a lender letter in hand. Pre-approval in Corpus Christi's balanced market is not optional — it is table stakes. Shop at least two or three lenders before committing; fees, rates, and service quality vary, and a small difference in terms compounds over thirty years.
Since the NAR settlement took effect in August 2024, buyers are now required to sign a written buyer-agent agreement before touring homes. Commission is no longer advertised on the MLS and is negotiated deal by deal. Most Corpus Christi sellers still offer buyer-agent compensation as a concession, but the amount is increasingly case-by-case. Read that agreement carefully and ask your agent exactly how they are compensated before you walk into the first showing.
Step 2: Know the Texas-Specific Contract Terms
Texas contracts include an option period that is unique to the state. A small non-refundable fee — typically $100 to $500 — buys you a window of roughly five to ten days during which you can back out of the deal for any reason and recover your earnest money. The option fee is separate from earnest money and is paid directly to the seller. This is the window in which you schedule your inspection, review the seller's disclosures, and decide whether to proceed. Do not let this period expire before your inspector has been inside the home.
Earnest money in Corpus Christi typically runs one to two percent of the purchase price. It is held in escrow and applied toward your closing costs or down payment at the table — but if you walk away outside the option period without a valid contractual out, you can lose it.
Step 3: Insurance and Flood Zone — Before the Offer, Not After
This is the step Corpus Christi first-timers most often defer too late. Before submitting an offer, ask the listing agent for the property's flood zone designation and request elevation certificate documentation if the home sits in or near a FEMA zone A, AE, or VE. Standard homeowners insurance does not cover flood damage — flood coverage is a separate policy, and lenders require it for federally backed mortgages on high-risk properties. Get insurance quotes for all three potential policies (homeowners, TWIA windstorm, flood) before you finalize your offer price. The combined premium can be the deciding factor on whether a house fits your budget.
Step 4: Inspection, Appraisal, and Clear to Close
Use the option period to hire an independent inspector — not one referred by the seller. In a coastal environment, inspectors experienced with Gulf Coast construction, pier-and-beam foundations, and salt-air corrosion are worth seeking out specifically. The appraisal is ordered by your lender and determines whether the property value supports your loan amount; a low appraisal triggers a renegotiation or requires you to make up the gap in cash.
At closing, Texas property taxes are settled in arrears: the seller will credit you for the portion of the current year's taxes they've already incurred, which appears as a credit on your settlement statement rather than a separate fee. File your homestead exemption with the Nueces Central Appraisal District (NCAD) as soon as you close — Texas law now allows you to file the day of closing, and the $140,000 school-district exemption (following Texas Proposition 13, passed in November 2025) represents real savings. The annual filing deadline is April 30, but late applications are accepted up to two years after the delinquency date.
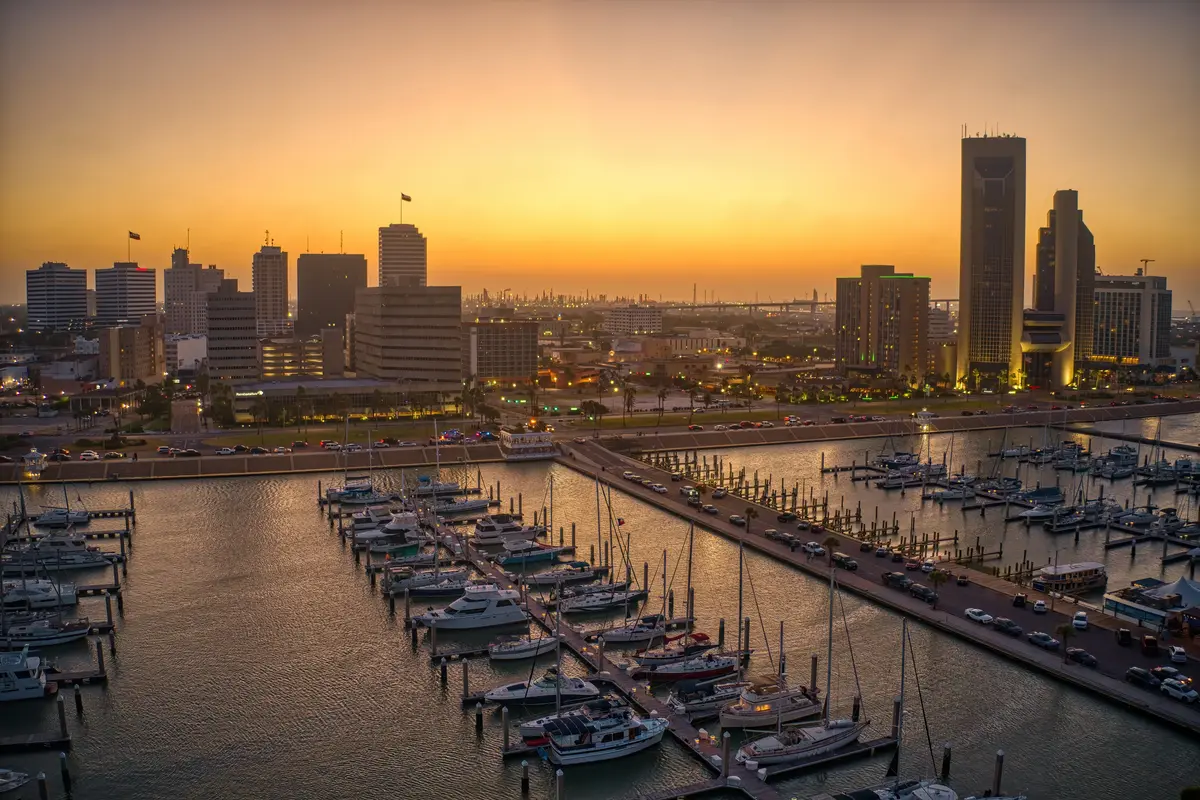
How Much Home Can You Afford in Corpus Christi
Texas buyers typically pay 2–6% of the purchase price in closing costs, covering lender fees, title, escrow, prepaid insurance, and prepaid taxes. The table below shows estimated cash needed at the closing table across several realistic Corpus Christi purchase scenarios. All figures are estimates; your lender's Loan Estimate will give you the definitive numbers for your specific situation. The interactive mortgage calculator below the table runs the monthly payment math at current rates.
One structural challenge baked into every Corpus Christi budget: coastal insurance premiums apply regardless of purchase price, and they are larger here than in most inland Texas markets.
| Scenario | Purchase Price | Loan Type / Down Payment | Down Payment Amount (Est.) | Est. Closing Costs (2–6%) | Est. Cash Needed at Table |
|---|---|---|---|---|---|
| FHA — minimum down | $160,000 | FHA / 3.5% | ~$5,600 | ~$3,200–$9,600 | ~$8,800–$15,200 |
| Conventional — low down | $160,000 | Conventional / 3% | ~$4,800 | ~$3,200–$9,600 | ~$8,000–$14,400 |
| FHA — near city median | $225,000 | FHA / 3.5% | ~$7,875 | ~$4,500–$13,500 | ~$12,375–$21,375 |
| Conventional — near city median | $225,000 | Conventional / 5% | ~$11,250 | ~$4,500–$13,500 | ~$15,750–$24,750 |
| Southside / Calallen entry | $270,000 | Conventional / 5% | ~$13,500 | ~$5,400–$16,200 | ~$18,900–$29,700 |
| Conventional — 20% (no PMI) | $225,000 | Conventional / 20% | ~$45,000 | ~$4,500–$13,500 | ~$49,500–$58,500 |
Seller concessions are genuinely on the table in Corpus Christi's balanced market — a seller covering two to three percent of your closing costs can meaningfully reduce the cash column above. Ask your agent to build that ask into the offer rather than treating it as an afterthought.
One line not in this table: insurance reserves. Lenders typically require several months of homeowners and flood insurance prepaid at closing. Budget for that separately, because it is not included in the 2–6% closing-cost range and it is larger in Corpus Christi than in most inland Texas markets.
Looking to buy in Corpus Christi? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Corpus Christi quote.
Common First-Time Buyer Mistakes in Corpus Christi
Mistake 1: Ignoring the Flood Zone Until After the Offer
The single most expensive mistake a Corpus Christi first-timer makes is treating flood zone status as a detail to sort out during the option period rather than before the offer. A home in a FEMA high-risk zone (AE or VE) requires separate flood insurance, and that premium can be several thousand dollars a year on top of homeowners and windstorm coverage. Get the flood zone designation from the listing agent before you decide what to offer — not after you're emotionally committed and racing the option-period clock.
Mistake 2: Shopping Before Pre-Approval
Corpus Christi's balanced market has enough inventory that buyers sometimes feel they have the luxury of browsing first and getting their finances in order later. That instinct is wrong. Since the 2024 NAR rule changes, you must sign a buyer-agent agreement before touring homes anyway — and any seller who receives an offer will want a lender letter alongside it. Buyers who arrive pre-approved negotiate from a fundamentally different position than those who don't, and in a market where a well-priced home on the Southside or in Calallen can attract multiple offers, the paperwork gap matters.
Mistake 3: Underbudgeting the Insurance Stack
Most first-time buyers run the math on principal, interest, and property taxes — then get the insurance quotes and feel the floor shift. Coastal homeowners insurance in Corpus Christi benchmarks well above the national average. Add a TWIA windstorm policy if your property qualifies, and flood insurance if your lender requires it, and the combined annual insurance cost can easily exceed $7,000 or more depending on the property. Build all three into your monthly budget estimate before you fall in love with a house, not after you've already submitted an offer.
Mistake 4: Skipping the Homestead Exemption Filing
Texas now allows you to file your homestead exemption with the Nueces Central Appraisal District the day you close. The $140,000 school-district exemption — expanded under Texas Proposition 13 in November 2025 — represents real, recurring savings on your tax bill. And once the exemption is in place, your taxable value cannot rise more than 10% per year regardless of what the market does around you. First-time buyers who don't know about the same-day filing rule sometimes wait until the following January, leaving prorated savings for that tax year on the table. File with NCAD promptly; the annual deadline is April 30 but the exemption is prorated from your actual closing date, so waiting costs money. For more on property taxes and their long-term impact on your budget, see the cost of living page.
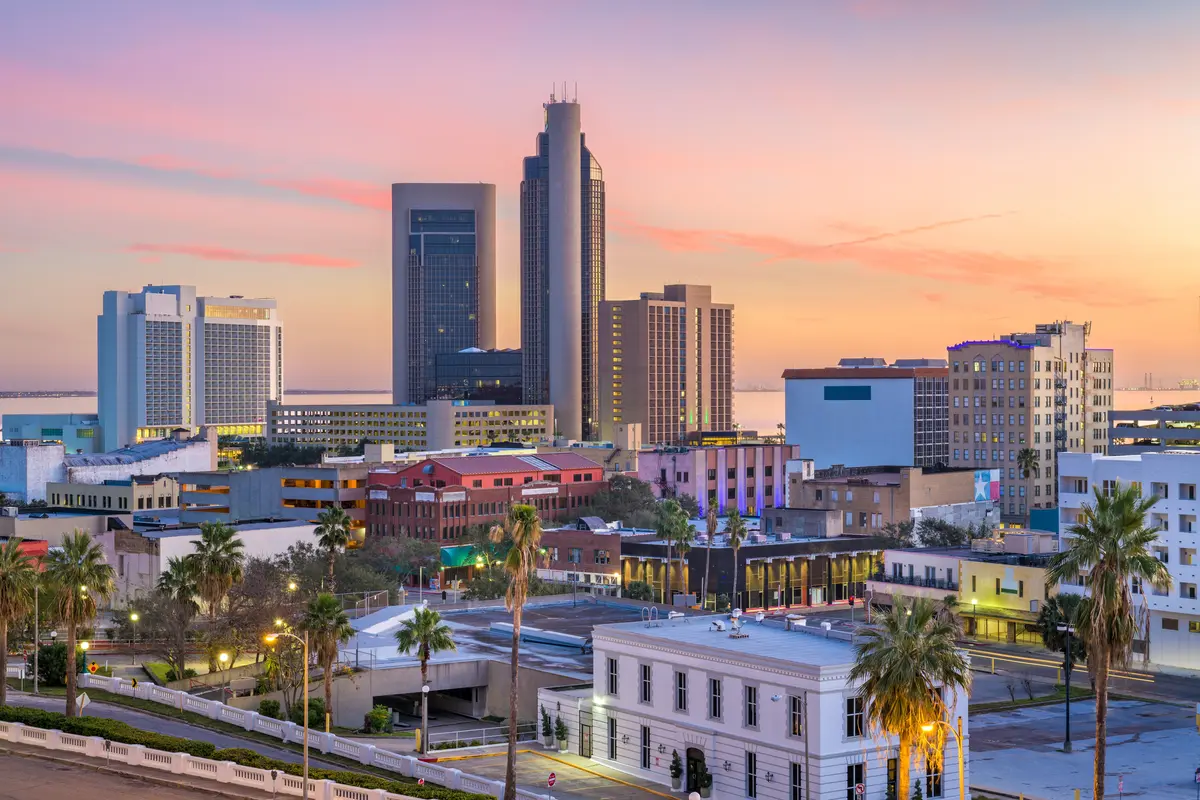
Local Expert Takeaway: Corpus Christi is one of the more genuinely affordable coastal cities in Texas, and the balanced market gives a prepared first-time buyer real leverage — including the ability to ask sellers to cover closing costs. But the insurance stack here is not a footnote. Before you write an offer on anything, you need a flood zone designation, a homeowners insurance quote, and a TWIA windstorm quote in hand. The buyers who get burned are the ones who did the mortgage math correctly and ignored the insurance math entirely. Get all three quotes, file your homestead exemption with NCAD the day you close, and you'll be ahead of most first-timers who've moved here in the last few years.
Quick Takeaways & FAQs
✅ The typical Corpus Christi home price of $224,996 (July 2026) is accessible by Texas coastal standards, and a balanced market means sellers are open to concessions on closing costs.
⚠️ Coastal insurance — homeowners, TWIA windstorm, and potentially flood — can add thousands of dollars annually beyond the mortgage payment; budget for all three before making an offer.
📍 Texas law lets you file your homestead exemption with the Nueces Central Appraisal District the day you close, which immediately begins reducing your school-district tax bill.
What is the typical home price for first-time buyers in Corpus Christi?
Do I need flood insurance to buy a home in Corpus Christi?
What are closing costs for buyers in Corpus Christi, Texas?
What is the Texas option period and how does it work for Corpus Christi buyers?
What is the homestead exemption in Texas and how do I file it in Corpus Christi?
Moving to Texas?
Tell us what you need help with and we'll connect you with local resources.
