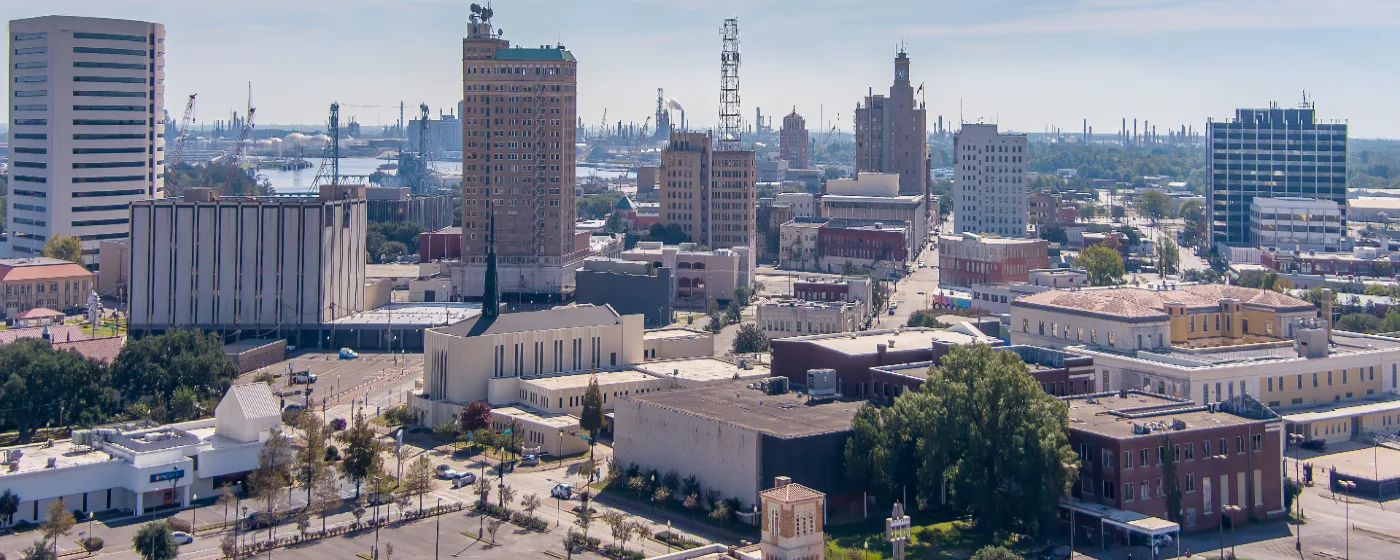
You've probably already done the math and noticed something that surprises most people comparing Texas housing markets: Beaumont is one of the most affordable entry points in the entire state. The Beaumont–Port Arthur metro consistently ranks among the three lowest-priced housing markets in Texas, which means a first-time buyer with modest savings can own a real house here — not a condo, not a townhome squeezed into a dense development — while a comparable budget in Houston would buy an hour of commuting and a bidding war. That affordability gap is Beaumont's biggest selling point for first-timers, and it's genuine.
The honest counterweight is this: Beaumont carries flood risk that Houston-area buyers expect but that out-of-state first-timers often underestimate. Jefferson County has recorded billions in federal flood insurance payouts since the late 1970s — one of the highest tallies in Texas. The Neches River floods on roughly a 5-to-10-year cycle. Flood zone designation can shift block by block inside the city, so the three-bedroom house in one part of a neighborhood may carry a mandatory flood insurance requirement while the one around the corner does not. Understanding this before you tour homes — not after you're under contract — is the single most important piece of local knowledge a first-timer in Beaumont needs.
The city's economy rests on a backbone of petrochemicals, healthcare, education, and Lamar University. The median household income sits at $56,997, which puts the typical home price within reach for buyers who budget carefully and understand the full cost stack — property taxes, flood insurance, and homeowner's insurance are all real line items here. The good news is that Texas's homestead exemption meaningfully reduces the taxable assessed value on your primary residence, and Jefferson County caps annual appraisal increases at 10% per year once that exemption is on file — real structural protections for owner-occupants that renters never get.
Whether you're a lifelong Beaumont renter finally ready to buy or relocating to Southeast Texas for work, this guide walks through what your budget actually buys here, the local buying process step by step, a clear-eyed affordability snapshot, and the mistakes that cost first-timers the most in this specific market.
The Beaumont First-Time Buyer Reality
The typical home price in Beaumont is $174,566 (Zillow Home Value Index, July 2026) — a figure that puts genuine detached single-family ownership within reach for buyers who can qualify for a loan and cover the cash needed at closing. That's not a starter condo price in a dense urban core; it's the citywide middle of the market, and it means entry-level homes begin well below it. See the full cost-of-living breakdown for context on how that price compares to nearby markets.
At that price point, a 3.5% FHA down payment is roughly $6,100. Even a conventional 5% down payment lands under $9,000. The cash-to-close hurdle in Beaumont is low by Texas standards, which is why the metro consistently attracts first-time buyers who've been priced out of the Houston market or who've been renting locally and finally run the numbers.
The catch isn't the purchase price — it's the ongoing cost stack. Beaumont's effective property tax rate of 1.53% is real, and flood insurance is a separate, mandatory cost for any home in a Special Flood Hazard Area. Beaumont participates in FEMA's Community Rating System at a Class 7 rating, which earns flood insurance policyholders in the flood zone up to a 15% discount on premiums — but even discounted flood insurance adds a meaningful annual line item that your mortgage payment won't cover. Budget for it before you fall in love with a house.
Neighborhoods like South Park, Charlton-Pollard, and Pear Orchard sit below the city median and represent the most accessible entry points. The neighborhoods guide covers the character and tradeoffs of each. The most important local reality: the Beaumont Independent School District holds a D rating, according to the Texas Education Agency, which is a factor many families weigh carefully when choosing a neighborhood and a school zone.
The Homebuying Process in Beaumont, Step by Step
Step 1: Get Pre-Approved Before You Tour Anything
Local agents are direct about this: pre-approval is not optional preparation in Beaumont — it's step one. In active price bands, sellers here often require pre-approval before they'll schedule a showing at all. A pre-approval letter tells you the actual loan amount you can close on, not just an estimate based on income, and it makes your offer competitive the moment you find the right house.
Pre-approval is not the same as pre-qualification. Pre-qualification is a five-minute estimate; pre-approval involves a lender pulling your credit, verifying income and assets, and issuing a conditional commitment. First-timers who skip to the open-house stage without it often lose homes to buyers who were ready to move immediately.
Step 2: Define Your Target Neighborhoods First
In Southeast Texas, neighborhood selection is especially critical because flood zone designation, school zone, and neighborhood trajectory can vary block by block. Local agents consistently recommend narrowing your target neighborhoods — based on commute, school zone, flood zone, and resale trajectory — before selecting individual homes. A house that looks like a deal may sit in a higher flood zone or a school boundary that matters to you.
Step 3: Make an Offer and Understand the Texas Option Period
Texas uses a TREC-standard contract that includes an option period — typically 7 to 10 days — during which you have an unrestricted right to back out of the deal in exchange for a non-refundable option fee. This is your inspection window. Use it. A financing contingency of roughly 21 days follows, with closing typically landing 21 to 30 days after that.
Texas sellers of previously occupied single-family homes must complete a Seller's Disclosure Notice covering known defects, past insurance claims, and — as of January 2025 — any mold remediation within the prior five years. Read it carefully. Sellers aren't required to fix what the disclosure or the inspection reveals, but knowing what you're buying is your right and your responsibility.
Step 4: Inspection, Flood Zone Check, and Appraisal
In Beaumont, a standard home inspection must be paired with a flood zone determination. Ask your lender or agent to confirm the property's FEMA flood zone designation early — before the option period expires, not after. If the home is in a Special Flood Hazard Area, get a flood insurance quote during the option period so you know the actual annual cost before you're committed.
The appraisal is ordered by your lender and happens independently. If the appraisal comes in below purchase price, you'll need to renegotiate, pay the difference in cash, or walk. In Beaumont's price range, this is less common than in hotter markets, but it happens.
Step 5: File Your Homestead Exemption Promptly After Closing
This step surprises most first-timers. Texas law requires school districts to provide a $140,000 homestead exemption on your primary residence — confirm the current figure with the Jefferson Central Appraisal District at the time of purchase, as the Legislature may adjust it. Filing promptly in the year you purchase captures that exemption sooner and triggers the 10% annual cap on appraisal increases, one of the most durable financial protections Texas owner-occupants have.
How Much Home Can You Afford in Beaumont
The table below shows approximate cash requirements at closing for several realistic Beaumont purchase scenarios. Closing costs are estimated at 2–3% of the purchase price — the actual figure varies by lender, title company, and negotiated seller concessions. These are estimates, not quotes. The interactive calculator below the table handles monthly payment estimates at current rates.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs | Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5%) — entry-level | ~$120,000 | ~$4,200 (3.5%) | ~$2,400–$3,600 | ~$6,600–$7,800 |
| FHA (3.5%) — city median | ~$174,566 | ~$6,110 (3.5%) | ~$3,490–$5,240 | ~$9,600–$11,350 |
| Conventional (3%) — city median | ~$174,566 | ~$5,240 (3%) | ~$3,490–$5,240 | ~$8,730–$10,480 |
| Conventional (5%) — city median | ~$174,566 | ~$8,730 (5%) | ~$3,490–$5,240 | ~$12,220–$13,970 |
| Conventional (10%) — above-median | ~$220,000 | ~$22,000 (10%) | ~$4,400–$6,600 | ~$26,400–$28,600 |
| Conventional (20%) — above-median | ~$220,000 | ~$44,000 (20%) | ~$4,400–$6,600 | ~$48,400–$50,600 |
A 20% down payment eliminates private mortgage insurance, which meaningfully reduces your monthly payment — but in Beaumont's price range, many first-timers find the PMI cost manageable enough that preserving cash reserves makes more sense than eliminating it entirely.
One Beaumont-specific budget item that every scenario above omits: flood insurance. If the home is in a Special Flood Hazard Area, lenders will require it, and it is not folded into the closing cost estimate. Get a quote during your option period and add it to your monthly budget alongside property taxes and homeowner's insurance. The property tax rate — and how the homestead exemption reduces your taxable value — is covered in detail on the cost-of-living page.
Also worth knowing: under the federal definition used by most Texas loan programs, you qualify as a first-time homebuyer if you haven't owned a primary residence in the past three years — not just if you've never owned at all. Previous owners who've been renting may still be eligible for first-time buyer loan products.
Looking to buy in Beaumont? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Beaumont quote.
Common First-Time Buyer Mistakes in Beaumont
Skipping the Flood Zone Check Until It's Too Late
The most expensive mistake first-timers make in Beaumont is falling in love with a house before checking its flood zone designation. Jefferson County's flood history is substantial, and the cost difference between a home in the Special Flood Hazard Area and one just outside it can be hundreds of dollars per year in insurance — every year you own the house. Check the FEMA flood map and get a flood insurance quote during the option period, not after it expires.
A significant share of Jefferson County households carry flood insurance, despite the area's documented flood exposure — and many who do not are simply hoping the loss never comes. Don't structure your budget around that hope.
Shopping Before Pre-Approval
Beaumont's lower price point makes some first-timers assume the market is slow and forgiving. It isn't uniformly so. In the entry-level range where most first-time buyers are looking, sellers in solid neighborhoods often receive multiple inquiries quickly. Showing up without a pre-approval letter means you can't make an offer when the right house appears, and in some cases you can't even get a showing scheduled.
Ignoring School Zone Boundaries When Choosing a Neighborhood
The Beaumont ISD serves the city, but individual school assignments depend on where your house sits — and those boundaries don't always follow neighborhood lines intuitively. First-timers who choose a home based on its street or general area sometimes discover mid-transaction that the school zone isn't what they assumed. If school assignment matters to your decision, confirm the exact boundary for any specific property before making an offer, not after. The schools page has the full district picture.
Underestimating Cash Needed at Closing
The down payment is the number first-timers focus on. Closing costs are the number that surprises them. At 2–3% of purchase price, closing costs on a $174,566 home run roughly $3,500 to $5,200 — on top of the down payment, on top of the option fee (non-refundable), and on top of any upfront escrow setup for taxes and insurance. Buyers who drain their savings to hit the minimum down payment sometimes arrive at closing short. Build a cash cushion beyond the down payment figure before you start touring.
One partial offset: the Texas homestead exemption reduces the taxable assessed value of your primary residence by $140,000 for school district taxes — confirm the current figure with the Jefferson Central Appraisal District when you purchase, as the Legislature may adjust it. File the exemption paperwork promptly after closing. It won't help you at the closing table, but it will lower your tax bill in the first full year of ownership.
Local Expert Takeaway: Beaumont is a genuinely accessible market for first-time buyers — one of the most affordable in Texas — but affordability at the purchase price doesn't mean affordability is simple. The combination of flood insurance requirements, property taxes at 1.53%, and closing costs means your real cash-to-close number is higher than the down payment alone suggests. Get pre-approved before you tour, check every property's FEMA flood zone designation during the option period, and file your homestead exemption with the Jefferson Central Appraisal District the year you close. Those three habits separate the first-timers who land smoothly from the ones who call their agent in a panic two weeks before closing.
Quick Takeaways & FAQs
✅ Beaumont's typical home price of $174,566 (July 2026) makes it one of the most accessible first-time buyer markets in Texas, with FHA down payments starting around $6,100.
⚠️ Flood zone designation varies block by block in Beaumont, and Jefferson County carries one of the highest federal flood insurance claim totals in Texas — every buyer must check flood zone status and budget for flood insurance before committing.
📍 Texas's option period (typically 7–10 days) is your unrestricted exit window after going under contract — use it to complete your inspection and get a flood insurance quote before it expires.
What credit score do I need to buy a home in Beaumont, TX?
Do I need flood insurance to buy a home in Beaumont?
How long does it take to close on a home in Beaumont?
What is the homestead exemption and how do I file it in Jefferson County?
I owned a home years ago but have been renting since. Can I still qualify as a first-time buyer?
Moving to Texas?
Tell us what you need help with and we'll connect you with local resources.
