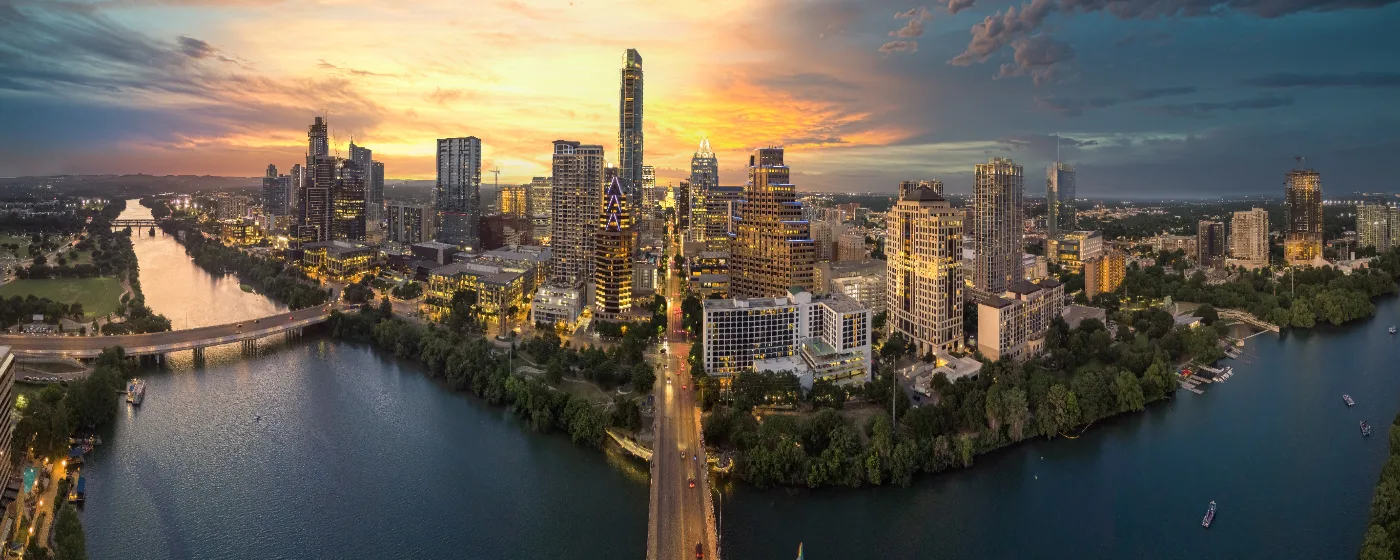
Maybe your company is relocating you to Austin. Maybe you've been renting for three years and watching the market, waiting for a moment that feels like yours. Here is the honest version of what you're walking into: Austin is a city of 1,002,632 people anchored by the Texas State Capitol, the University of Texas at Austin, and a technology and government job base that has made it one of the most sought-after metros in the country. The good news is that conditions have shifted meaningfully from the frenzy of 2022. The catch is that the typical home price — $504,148 as of July 2026 — still sits well above what the median Austin household income can comfortably carry, which means preparation, not just enthusiasm, is what separates buyers who close from buyers who keep watching.
The economic picture here is genuinely strong. Austin's metro-area employment topped 1.4 million nonfarm jobs as of early 2026, with the unemployment rate running below the national average. Employers ranging from the Austin Independent School District and the State of Texas to Tesla's Gigafactory Texas and Ascension Seton anchor a broad range of incomes across the city. That diversity of employers is a real long-term stability argument for owning here. The Austin Independent School District holds a C rating, according to the Texas Education Agency, with 69,074 students enrolled in 2025-26 — a scale that makes school boundary research essential before you fall in love with a house.
On the cost side, Texas has no state income tax, which softens the sting of property taxes that run above the national average. The effective rate in Austin runs approximately 1.54%, and first-time buyers should understand that their lender will likely require a property tax escrow deposit at closing — typically three to six months of taxes held upfront. The upside: Texas voters approved an expansion of the school district general homestead exemption to $140,000 of assessed value, effective for tax years 2025 and 2026, which provides real relief once you're an owner-occupant. First-time buyers who find the city median stretching their budget will want to explore nearby communities where prices run noticeably lower — see the full breakdown on the best neighborhoods page.
Whether you're deciding between a condo near Lady Bird Lake and a house in Circle C Ranch, or simply trying to understand what pre-approval really means here, the sections below break down Austin's first-time buyer reality, the step-by-step process, how to build a realistic budget, and the specific mistakes that cost local buyers the most.
The Austin First-Time Buyer Reality
The National Association of Realtors reported that the share of first-time homebuyers nationwide sank to an all-time low of 21 percent in 2025 — compared with a historic national average of 40 percent. Austin is part of why that number looks the way it does. The typical home price of $504,148 (July 2026, Zillow Home Value Index) means that even with a modest down payment, your monthly carrying costs are real. Entry-level inventory — condos, townhomes, and older single-family homes in outer neighborhoods — tends to start in the low-to-mid $300,000s, though options at that price point require patience and move quickly when they appear.
The geography of affordability matters here. Neighborhoods priced above the city median include East Austin, Hyde Park, Mueller, and Allandale — all desirable, all competitive, and none of them the place to stretch a first-time budget to its absolute limit. For a detailed look at which parts of the city offer more room for your dollar, see the best neighborhoods page.
The market has genuinely shifted from its 2022 peak. Inspection contingencies and seller concessions — credits toward closing costs — have returned to Austin transactions, giving first-time buyers negotiating tools that were largely absent a few years ago. That does not mean Austin is a buyer's market in the traditional sense, but it does mean you have more room to ask questions, request repairs, and take the time to make a sound decision. The buyers who succeed here are the ones who treat this as a process, not a competition.
The Homebuying Process in Austin, Step by Step
Step 1: Get Pre-Approved Before You Tour a Single Home
In Austin, this is not optional advice — it is the price of admission. Sellers and their agents routinely decline to schedule showings for buyers without a pre-approval letter in hand. Pre-approval means a lender has verified your income, assets, employment, and credit — not just run a soft estimate. Do this before you fall in love with a house on a drive through Mueller or spend a weekend walking open homes in Allandale.
Step 2: Align on Budget and Neighborhood Before Shopping
Know your ceiling before you walk in a door. The gap between what you're pre-approved for and what you're comfortable spending monthly can be significant in a city where property taxes add meaningfully to the payment. Use the interactive calculator below this section as your baseline. Then research school boundaries: the Austin Independent School District's attendance zones do not always follow neighborhood lines, and a house one block outside a preferred zone is a different purchase than one inside it.
Step 3: Make an Offer with the Right Contingencies
Austin currently supports including an inspection contingency as a standard part of most offers — use it. A general home inspection is non-negotiable for a first-time buyer; it is the one step people most often underestimate or, under competitive pressure, talk themselves into skipping. Skipping it does not make your offer stronger in today's market — it just removes your ability to negotiate repairs or walk away with your earnest money.
Also negotiate clearly on the appraisal contingency. If the home appraises below your offer price, this contingency lets you renegotiate or exit. In a market where seller concessions have returned, you can sometimes ask for a credit toward closing costs rather than a price reduction — both accomplish a similar goal.
Step 4: Navigate Inspection, Appraisal, and Title
After the offer is accepted, you'll have a negotiated option period — typically a few days — during which you pay a small option fee for the right to walk away for any reason. Use that window to complete your inspection and review the results carefully. The appraisal is ordered by your lender and typically takes one to two weeks. Title review runs concurrently; Texas uses title companies (rather than attorneys) to handle closings, so your title company is your primary closing coordination point.
Step 5: Close — and Understand What You're Signing
Closing in Texas happens at the title company. Plan to spend one to two hours reviewing and signing documents. You'll bring a cashier's check or wire for your down payment and closing costs — personal checks are rarely accepted. Lenders typically require a property tax escrow deposit of three to six months upfront, so your cash at the table will be higher than your down payment alone. Budget for it explicitly.
How Much Home Can You Afford in Austin
Closing costs in Austin typically run 2% to 5% of the purchase price, covering lender origination fees, title insurance, appraisal, county recording fees, and prepaid property taxes and homeowners insurance. The table below uses that range to show realistic cash-to-close estimates across several price points — from entry-level to near the city median. These are estimates; your exact figures depend on your lender, the specific property, and how you negotiate seller concessions.
| Scenario | Purchase Price | Down Payment | Est. Closing Costs (2–5%) | Est. Cash Needed at Table |
|---|---|---|---|---|
| FHA (3.5% down) — entry level | $325,000 | $11,375 (3.5%) | $6,500–$16,250 | ~$18,000–$28,000 |
| Conventional (3% down) — entry level | $325,000 | $9,750 (3%) | $6,500–$16,250 | ~$16,000–$26,000 |
| FHA (3.5% down) — mid-range | $425,000 | $14,875 (3.5%) | $8,500–$21,250 | ~$23,000–$36,000 |
| Conventional (3% down) — mid-range | $425,000 | $12,750 (3%) | $8,500–$21,250 | ~$21,000–$34,000 |
| Conventional (5% down) — near city median | $504,148 | $25,207 (5%) | $10,083–$25,207 | ~$35,000–$50,000 |
| Conventional (10% down) — near city median | $504,148 | $50,415 (10%) | $10,083–$25,207 | ~$60,000–$76,000 |
A note on property taxes that every Austin first-timer should read: at the effective rate of approximately 1.54%, annual taxes on a $504,148 home are a real line item. File your homestead exemption in the first year of ownership — the school district exemption now covers $140,000 of assessed value, which delivers meaningful savings starting in your first full tax year. Once filed, Texas's 10% appraisal cap limits how fast your assessed value can grow annually, which becomes a significant long-term protection in neighborhoods that appreciate quickly. Use the interactive calculator below to model your specific payment at current rates.
Looking to buy in Austin? Estimate your payment.
Enter your numbers to see an estimated monthly mortgage payment.
Estimate only. Excludes HOA fees and mortgage insurance. The interest rate above is a starting point, not a quoted rate — replace it with your own to see real numbers. Insurance is a flat placeholder, not a Austin quote.
Common First-Time Buyer Mistakes in Austin
Touring Homes Before Getting Pre-Approved
This happens constantly, and it costs buyers in two ways. First, you lose time: a home you love goes under contract while you scramble to gather documents. Second, you anchor to price points before you know your real ceiling. In Austin, where well-priced homes in neighborhoods like Mueller or East Austin attract multiple offers, arriving without pre-approval is not a minor oversight — it disqualifies you from the conversation before it starts.
Waiving the Inspection Contingency to Win
During the 2022 peak, buyers waived inspections routinely to compete. That market is not this market. Sellers in Austin are currently accepting offers with inspection contingencies, and in many cases offering concessions. A first-time buyer who waives an inspection to shave a few days off the timeline is trading their one substantive due-diligence tool for a marginal competitive edge they probably don't need. The option fee is a small cost; a foundation issue discovered after closing is not.
Ignoring School Boundary Reality
The Austin Independent School District serves 69,074 students enrolled in 2025-26 across a city with irregular, sometimes counterintuitive attendance boundaries. Two houses on the same block can feed different elementary schools. If school assignment matters to your family — and for most buyers with children it does — verify the specific address against the district's boundary tool before making an offer, not after. Buying in Allandale or Hyde Park and assuming you know which school you'll get is one of the most common post-closing surprises agents see.
Underbudgeting Closing Cash — Especially the Escrow Deposit
First-time buyers typically focus on the down payment and forget that closing costs add another 2% to 5% on top. What surprises them further is the property tax escrow deposit: lenders routinely require three to six months of taxes held in escrow at closing, which adds thousands to the cash you need at the table. At Austin's effective property tax rate of approximately 1.54%, this is not a rounding error on a $450,000 purchase — it is a real line item that needs to be in your savings plan well before you make an offer. Build the full table above into your budget, not just the down payment row.
Local Expert Takeaway: Austin's first-time buyer window is more open than it was two years ago — inspection contingencies are back, sellers are negotiating, and more listings are available. But the math is still genuinely hard: the typical home price of $504,148 (July 2026) sits well above what the median Austin household income can carry without a meaningful down payment and disciplined budgeting. Get pre-approved first, research school boundaries for any specific address before you fall in love with it, file your homestead exemption the year you close, and build your property tax escrow deposit into your cash-to-close estimate from day one. Buyers who do those four things arrive at the closing table ready; buyers who skip any one of them tend to learn it the hard way.
Quick Takeaways & FAQs
✅ Inspection contingencies and seller concessions have returned to Austin transactions, giving first-time buyers real negotiating leverage that was largely gone during the 2022 frenzy.
⚠️ The typical Austin home price of $504,148 (July 2026) sits well above what the median household income can comfortably support — budget honestly and explore nearby communities if the city median stretches you too thin.
📍 File your homestead exemption in your first year of ownership: the school district exemption now covers $140,000 of assessed value and, combined with Texas's 10% annual appraisal cap, delivers lasting tax protection in a city where values move.
What credit score do I need to buy a home in Austin?
How much do I need saved before buying a home in Austin?
Is Austin still a good time to buy for first-timers?
What is the homestead exemption and how do I file it in Austin?
Should I buy in Austin proper or in a nearby city like Round Rock or Cedar Park?
Moving to Texas?
Tell us what you need help with and we'll connect you with local resources.
